


What Designer Brands Doubters Got Wrong Before A 79% Rally
If Designer Brands sat on your watchlist instead of in your account, the result may feel painful in hindsight. Holding Designer Brands over the past year would have returned 79.2%, including dividends. That outcome looks even more interesting alongside the later report that revenue slipped while net income and net margin improved. If analysts already expected tighter cost control and higher private label mix back in October 2025, what signal in that margin story might have justified more confidence?
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
The easy part of this move is behind Designer Brands. Zero in on 29 high quality undervalued stocks for companies trading below our estimates.
The Two Designer Brands Stories Investors Had To Weigh
The shares cost US$3.7 at the start, and you were effectively choosing between two competing stories about Designer Brands.
On the optimistic side, the bullish narrative put Fair Value at US$5, or 35% above the start price, hinging on revenue growth of 1.1% and profit margin reaching 4.4% over three years.
The bearish view pointed to a Fair Value of US$3, or 19% below the start price, stressing weak consumer demand, declining store traffic, and pressure from heavy promotions on profitability.
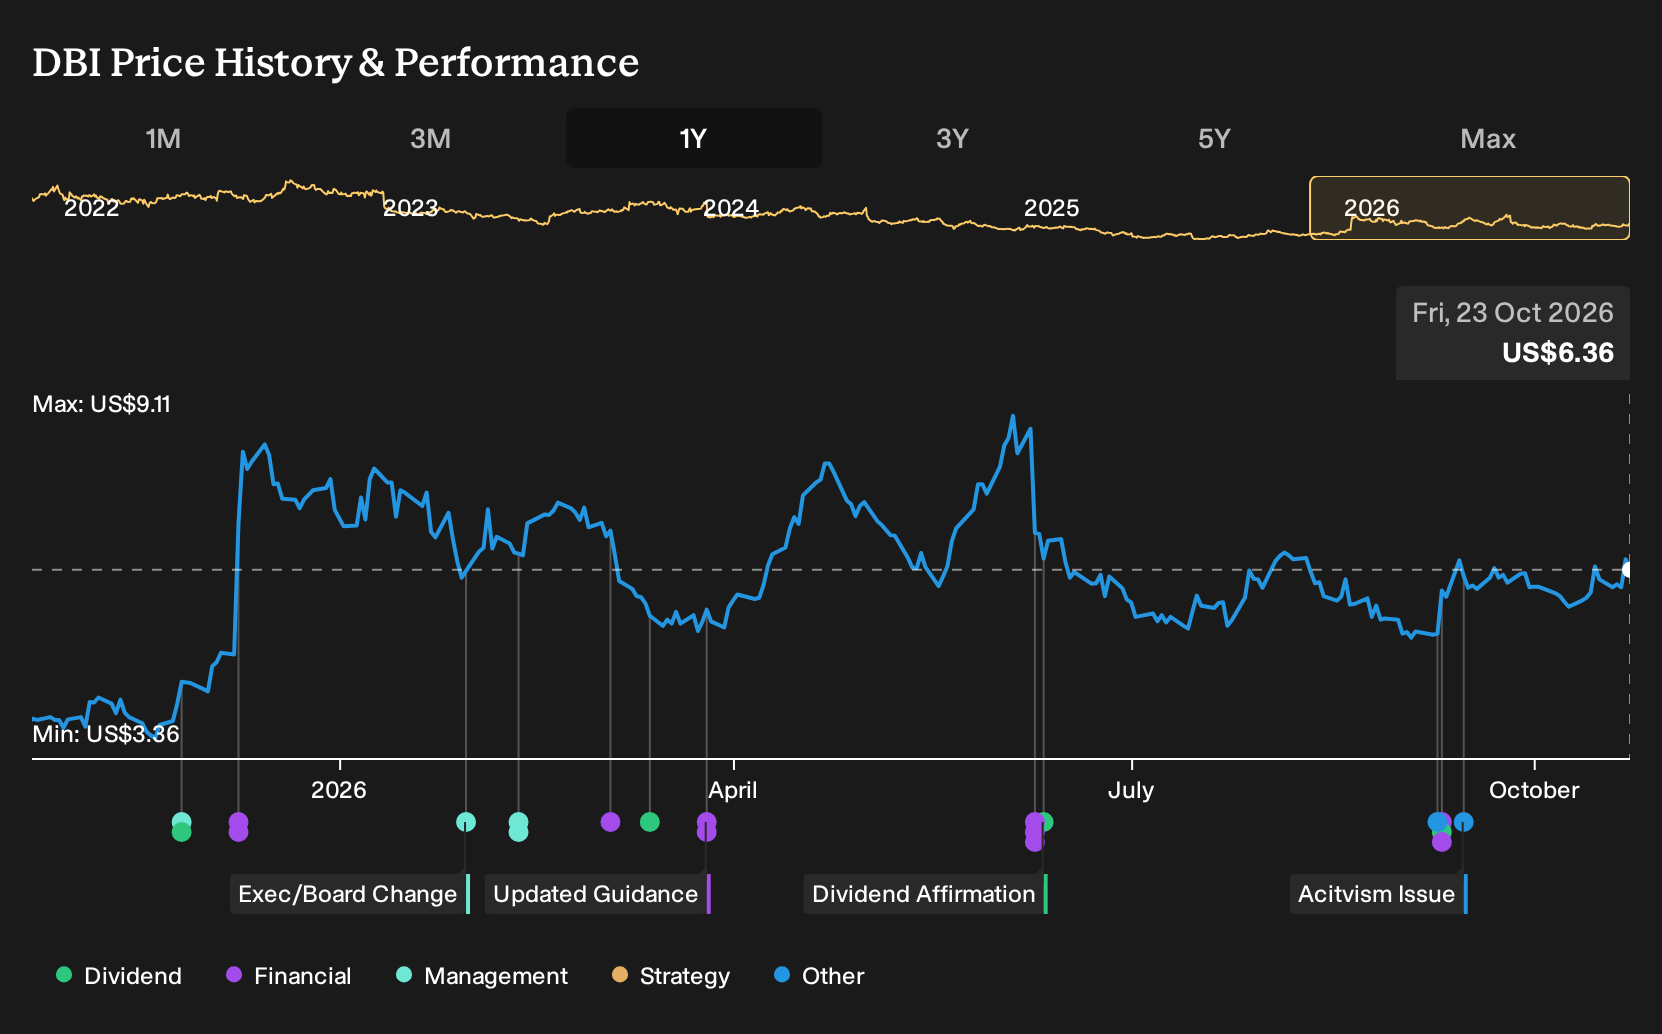
What The Results Changed For Designer Brands
Revenue at Designer Brands moved from US$739.8m in Q2 2026 to US$730.6m in Q2 2027, which challenged the upbeat story built on steady top line expansion. Net income rose from US$10.5m to US$17.6m and net margin shifted from 1.4% to 2.4%, which supported the optimistic focus on tighter costs. Overall, the evidence cut both ways.
The lesson is simple. When a thesis leans on margin improvement, track net income and net margin beside revenue each quarter so you can see whether efficiency gains are arriving without relying on uninterrupted sales growth.
What Designer Brands' Run Now Asks You To Believe
Designer Brands now trades at US$6.36. The key question is whether expectations moved faster than the business after the jump from a lower starting price. Revenue edged from US$739.8m in Q2 2026 to US$730.6m in Q2 2027, so the top line did not push the story forward.
Profit told a different story. Net income reached US$17.6m and net margin rose to 2.4%. The valuation tool can help you test how far future margin gains are already assumed.
The return is settled. The valuation question is not. Pinpoint what our model says Designer Brands is worth.
Find Your Own Contrarian Opportunity
You may be late to this rally, but that does not have to mean arriving late to every opportunity. Start with companies whose prices leave room for a different view of their future. Here are three trading below our estimates.
- Company 1 - 33% below our estimate - targets data centre build outs where AI hardware and software remain tightly integrated.
- Company 2 - 24% below our estimate - embeds AI assistants across productivity, developer tools and cloud infrastructure for existing enterprise clients.
- Company 3 - 37% below our estimate - advises on complex technical, regulatory and safety problems as projects demand deeper multidisciplinary expertise.
Three companies from the same screener. Open the full list of 24 financially solid companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com