


Synaptics (SYNA) Unveils New Edge AI Platforms, Is The Upside Already Priced In?
Synaptics (SYNA) has put fresh attention on its shares after unveiling the Astra SR200 xMCU line and Coralboard platforms, which target multimodal Edge AI workloads that run fully on-device across wearables and industrial systems.
Against this backdrop of new Edge AI hardware, Synaptics shares trade at US$117.26, with a 30-day share price return of 14.16% and a year-to-date share price return of 54.82%. The 1-year total shareholder return of 64.69% points to strong momentum building around the story.
Capitalize on Synaptics' Edge AI momentum and scan a curated set of hardware and infrastructure plays with the 55 AI infrastructure stocks.After a sharp run on the Astra and Coralboard news, the real debate now is simple. Is Synaptics still pricing in only the early innings of Edge AI, or has most of the upside already been pulled forward in the multiple?
Most Popular Narrative: 10% Undervalued
Against the last close at $117.26, the most followed narrative pins Synaptics fair value around $130.33, which suggests the current quote sits below that narrative anchor and puts fresh focus on whether the Edge AI story has more room to run.
The company's strategy to bundle highly integrated solutions combining wireless connectivity, low-power mixed-signal processing, and embedded AI/software content is expected to increase silicon content per device and drive higher gross margins as more revenue is captured per customer design win. Active product portfolio optimization, including organic and disciplined inorganic investment, is intended to repurpose engineering talent toward higher ROI segments (especially Core IoT and Edge AI). This approach supports expanding operational leverage and could contribute to margin expansion and operating earnings growth.
See why 16 investors see Synaptics as 10% undervalued.
Result: Fair Value of $130.33 (UNDERVALUED)
Still, two things could challenge the bullish Synaptics narrative quickly: execution missteps in shifting toward Core IoT solutions or tougher competitive pressure on pricing could both derail those upbeat assumptions.
Find out about the key risks to this Synaptics narrative.
Another View: SWS DCF Flags Synaptics As Expensive
While the analyst narrative pegs Synaptics around $130.33, the SWS DCF model lands much lower. On this cash flow view, Synaptics is trading above an estimated value of $82.98, which reads as overvalued and raises a simple question: Is the story running ahead of the cash generation?
Investors who want to see how the cash flow driven view is built line by line can go deeper with the Look into how the SWS DCF model arrives at its fair value..
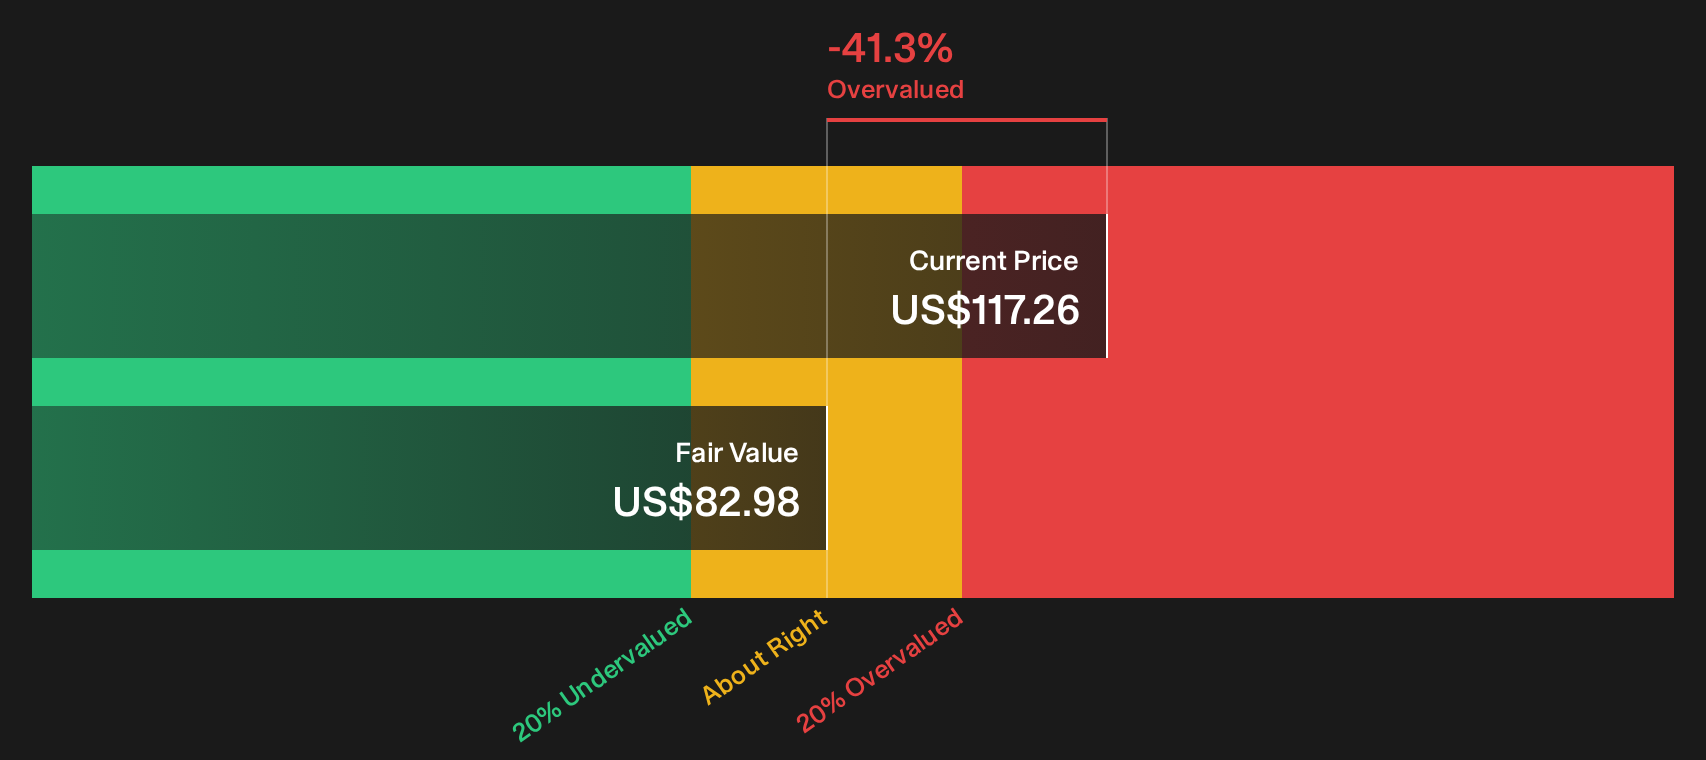
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Synaptics for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this mix of enthusiasm and caution around Synaptics feels familiar to you, consider reviewing the data yourself promptly so your stance is based on more than headlines and short term moves, then round out your view with the 1 key reward and 2 important warning signs.
Looking For More Ideas Beyond Synaptics?
Do not stop your research with Synaptics. Broader context across other opportunities helps you judge whether the risk and reward profile here still earns a place in your portfolio.
- Target resilient compounding potential by scanning companies with strong cash generation and supportive valuations through the 29 high quality undervalued stocks.
- Prioritise sleep at night stability by reviewing companies in the 30 resilient stocks with low risk scores that pair sturdier risk profiles with measured return potential.
- Hunt for early stage opportunities that the market may be overlooking by checking the 21 high quality undiscovered gems before attention moves elsewhere.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com