


36% Undervalued? Penguin Solutions (PENG) Following Axe Compute Partnership And Q3 Beat
Penguin Solutions (PENG) has attracted investors’ attention after Axe Compute Inc. selected the company as a key partner for deploying large GPU cluster sites that support enterprise AI infrastructure projects worldwide.
The Axe Compute partnership and a strong Q3 earnings beat arrive after a powerful run in Penguin Solutions’ shares, with a year-to-date share price return of 163.36%, a 1-year total shareholder return of 138.44%, and a 3-year total shareholder return of about 3x.
Scan for other AI infrastructure beneficiaries beyond Penguin Solutions by focusing on our hand-picked 55 AI infrastructure stocks that are tied to similar GPU buildout and data center themes.
After a 163% year-to-date surge and a pullback following a strong Q3 beat, Penguin Solutions now forces a simple timing call. Is it worth paying up today or waiting for a cooler entry before committing fresh capital?
Most Popular Narrative: 36% Undervalued
The most followed narrative pegs Penguin Solutions’ fair value at about $83.57 per share, well above the recent $53.41 close. This puts the current Axe Compute news and recent AI contract momentum into sharper context for long term holders.
Increasing demand for scalable and energy-efficient data center solutions, driven by edge computing and new AI workloads, aligns with Penguin's differentiated, customizable hardware and software offerings, supporting higher-margin solution sales and long-term improvement in net margins.
See why 29 investors see Penguin Solutions as 36% undervalued.
Result: Fair Value of $83.57 (UNDERVALUED)
Still, the Penguin Solutions narrative can break if large project timing swings keep earnings choppy or if tariff and cost pressures squeeze already sensitive margins.
Find out about the key risks to this Penguin Solutions narrative.
Another View: Penguin Solutions Through The SWS DCF Lens
Multiples paint Penguin Solutions as attractively priced, with a P/E of 21.3x compared with 42.6x for the US Semiconductor group and a fair ratio of 37.7x. Our SWS DCF model tells a different story. On that framework, PENG screens as expensive at $53.41 versus an estimated cash flow value of $30.93.
The gap between earnings-based metrics and the SWS DCF output leaves you with a simple question. Is the stronger growth profile worth paying well above the modelled future cash flows, or is this where discipline should start to matter more than AI excitement? Look into how the SWS DCF model arrives at its fair value.
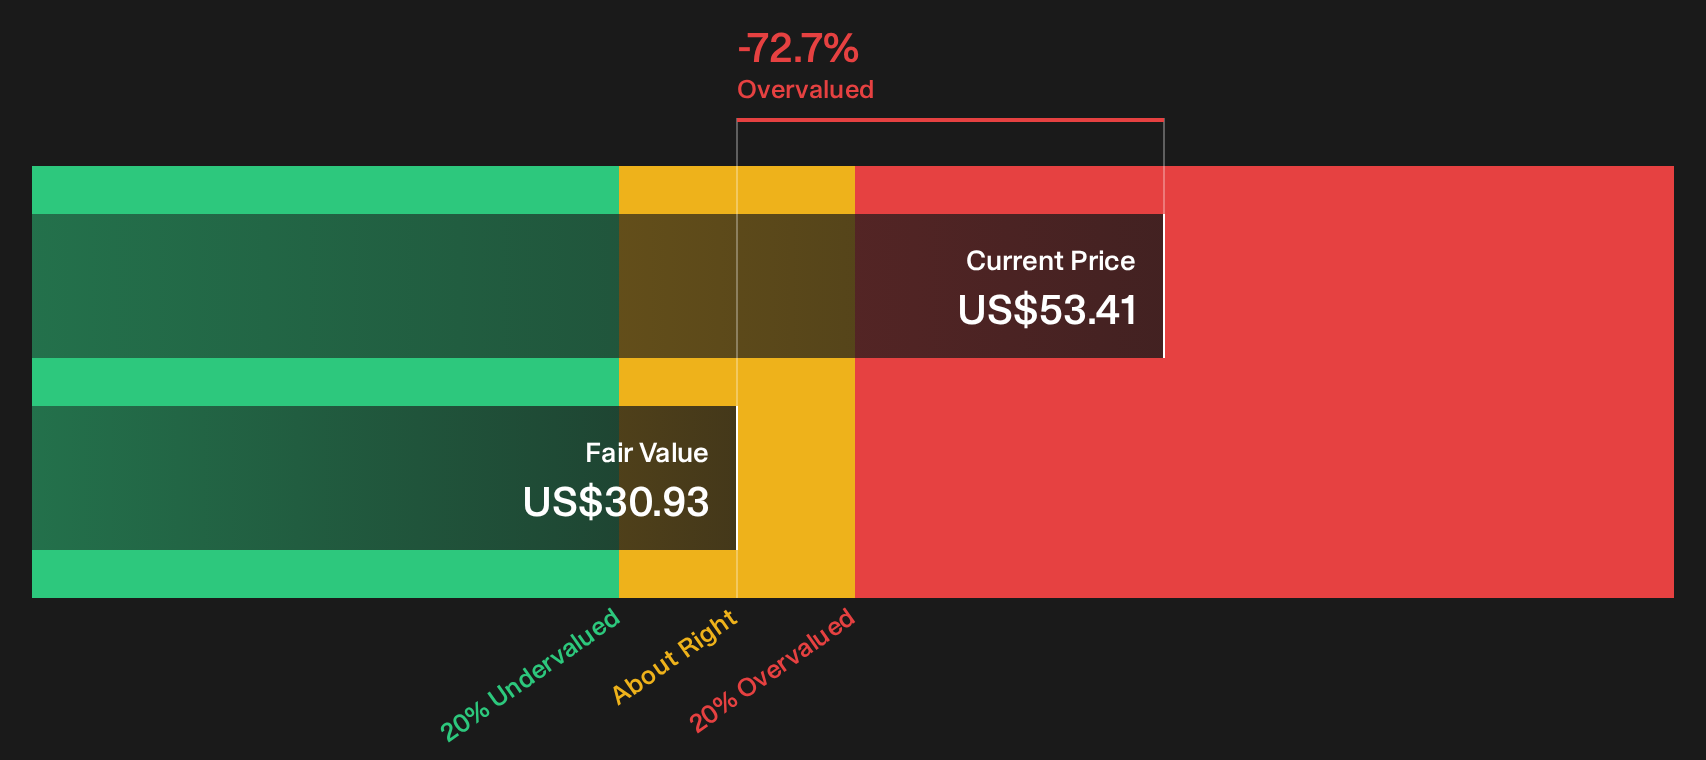
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Penguin Solutions for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this mix of enthusiasm and caution around Penguin Solutions feels familiar, consider your options while sentiment is still split and weigh the 5 key rewards and 2 important warning signs.
Ready For More Investment Ideas Beyond Penguin Solutions?
If Penguin Solutions has sharpened your focus on AI and infrastructure themes, broaden your watchlist with fresh opportunities sourced directly from Simply Wall Street’s stock screener.
- Target resilience in rocky markets by scanning companies with a strong financial cushion using our list of solid balance sheet and fundamentals (24 results).
- Look for quality at a discount by checking the 29 high quality undervalued stocks before prices move beyond your preferred range.
- Explore potential income streams by reviewing dependable payers in the 5 dividend fortresses while current yields meet your criteria.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com