


Main Street Capital (MAIN), What Is Drawing Fresh Attention Now?
Why Main Street Capital Is Back On Investors' Radar
Main Street Capital (MAIN) is drawing fresh attention as its next earnings report on 5 November approaches, with Wall Street watching how a projected US$1 EPS filters through to distributions and valuation.
Recent trading in Main Street Capital has cooled, with the share price at US$53.51 and a year-to-date share price return down 13.34%, even as the 5-year total shareholder return of 80.42% points to stronger long-run compounding.
Compare Main Street Capital’s setup to a hand picked group of income focused financiers and credit players screened for valuation and balance sheet strength using the 28 high quality undervalued stocks.
Main Street Capital’s softer share price and firm specific premium to book tell two very different stories. Is this stretch a signal of business strength, or just sentiment running ahead of itself as earnings approach, and how does that feed into valuation?
Most Popular Narrative: 11% Undervalued
On the latest numbers, the most followed narrative pegs Main Street Capital’s fair value at about $60.33, versus a last close of $53.51, which puts the spotlight on how earnings quality and funding costs line up against that gap.
The refinancing of US$500m of 3% notes with US$200m of March 2029 notes at a 6.2% yield and US$150m of April 2031 private notes at 6.93%, combined with an upsized US$1.24b credit facility maturing in 2031, creates a higher long term funding cost base that can offset gains from the low operating expense ratio of 1.3% and weigh on net margins and dividend coverage.
See why 98 investors see Main Street Capital as 11% undervalued.
Result: Fair Value of $60.33 (UNDERVALUED)
Still, Main Street Capital’s higher long term borrowing costs and falling dividend income from exited equity positions give that 11% valuation gap plenty of room to close.
Find out about the key risks to this Main Street Capital narrative.
Another View: Main Street Capital Through The DCF Lens
A different lens on Main Street Capital comes from the Simply Wall St DCF model, which estimates a future cash flow value of $40.17 per share versus the current $53.51 price. That points to an overvalued reading. This raises the question of which signal to focus on: earnings based fair value or cash flow calculations.
Look into how the SWS DCF model arrives at its fair value.
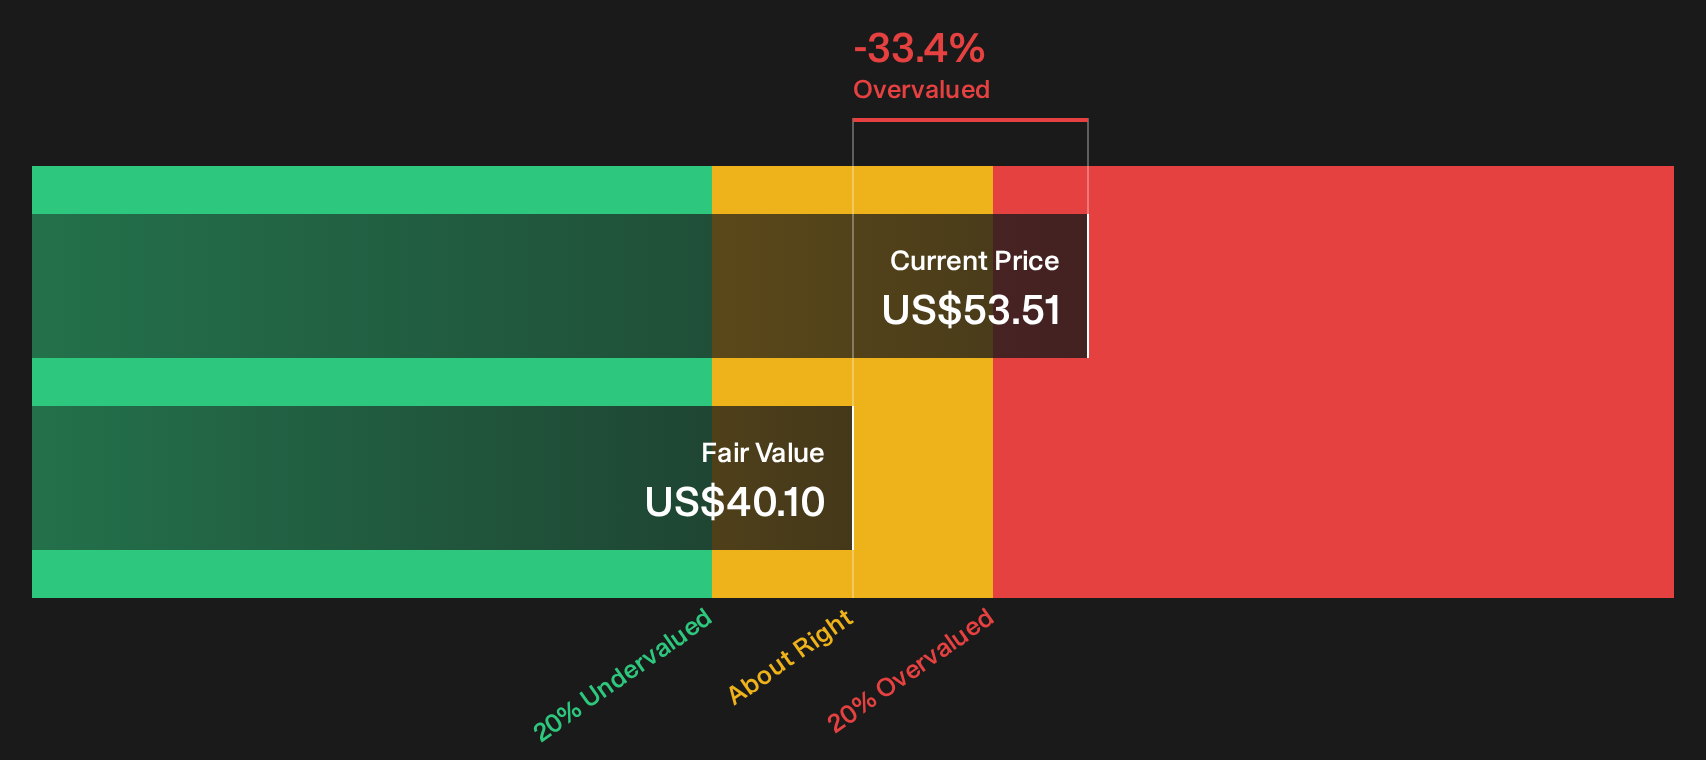
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Main Street Capital for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 28 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this mix of signals around Main Street Capital leaves you split, move quickly to test the data yourself and weigh both sides. To see how those cross currents look when you stack them side by side, check out the 1 key reward and 5 important warning signs.
Looking For More Investment Ideas Beyond Main Street Capital?
You have seen how different valuation tools frame Main Street Capital. Now broaden your watchlist with a few focused idea lists before the next move passes by.
- Target resilient compounding potential by scanning companies with strong fundamentals and low leverage using our list of solid balance sheet and fundamentals (24 results).
- Hunt for quality at a discount by reviewing the 21 high quality undiscovered gems that many investors may not be watching yet.
- Prioritise sleep at night stability with a basket of 30 resilient stocks with low risk scores tailored to investors who want calmer price swings.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com