


NeoGenomics (NEO) Stock May Trade Above Fair Value Despite AI Pathology Expansion
NeoGenomics has had a mixed share price record over the past few years, and the question now is whether the current US$16.59 level can be squared with what the business is generating in sales. With attention on its role in cancer diagnostics and lab services, the valuation debate turns on how much revenue investors are effectively paying for today.
- The stock has fallen 63.9% over the past 5 years, which puts the focus firmly on whether the market is now over or under shooting what its sales can support.
- The expanded Indica Labs partnership to scale AI-powered digital pathology may support expectations for more efficient test throughput and potentially richer revenue per case, which feeds directly into how much investors might be prepared to pay per dollar of sales.
- The analysts covering NeoGenomics have run their own numbers. See what analysts think NeoGenomics's shares could be worth.
The issue now is whether NeoGenomics' current share price is appropriately aligned with its sales based on the Fair Ratio benchmark.
If you want to test whether NeoGenomics' sales-based valuation question also shows up elsewhere in healthcare, compare it with companies in the 34 healthcare AI stocks.
Is NeoGenomics Getting Expensive on Sales?
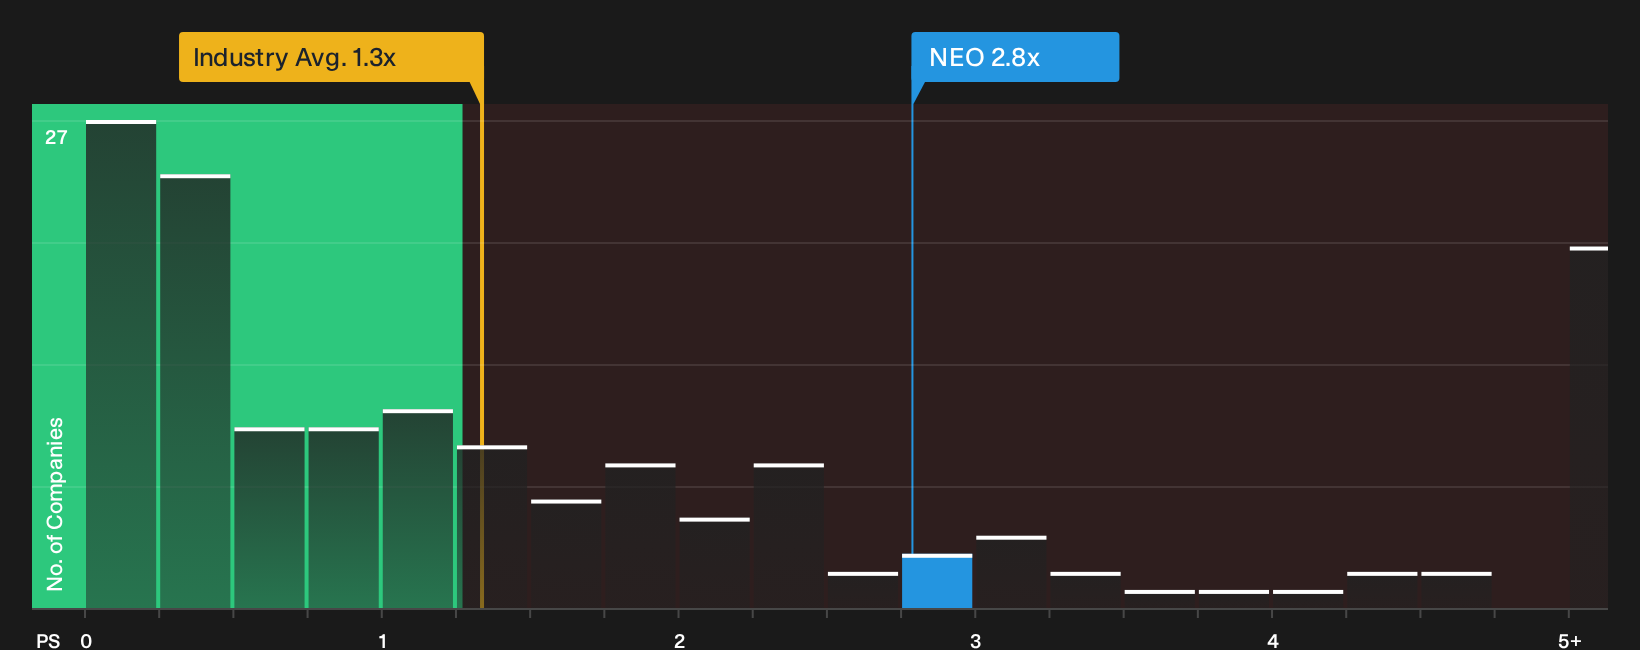
P/S fits NeoGenomics because investors are currently paying more attention to its revenue scale than its loss-making free cash flow profile. At a P/S of 2.8x, the stock trades at roughly double the Healthcare sector average of 1.3x and also above the 1.4x level implied by the peer group. Because the Fair Ratio folds in NeoGenomics' own risk profile and business mix, the current P/S sitting above that benchmark points toward the shares screening as overvalued on this framework.
Because the expanded Indica Labs partnership sharpens the story around AI-powered digital pathology, the higher multiple suggests investors are already paying up for that potential in the sales line. For anyone evaluating NeoGenomics at this price, the key consideration is whether its future revenue quality and scale can justify paying a premium P/S compared with both peers and the Fair Ratio signal. Explore the numbers behind NeoGenomics's P/S valuation.
The NeoGenomics Narrative: What Would Justify Today's Price?
Narratives for NeoGenomics pick up where the valuation puzzle leaves off. They spell out which paths for growth, margins and earnings would need to play out for the shares to look meaningfully higher or lower than today's price, and they sit on Simply Wall St's Community page. Each one links its number to a clear view on how sales momentum, profitability and risk might evolve, giving you something concrete to revisit as new information comes through.
NeoGenomics draws two very different readings, with one camp seeing more upside in the oncology testing story than the more cautious side.
Bull case: 22% undervalued
"The commercial launch of PanTracer, a comprehensive liquid biopsy panel for therapy selection, is set to enhance NeoGenomics' competitiveness and capture greater share in the rapidly growing NGS and liquid biopsy segment…"
Discover why this Narrative puts NeoGenomics at 22% undervalued.
Bear case: roughly fairly valued
"Bearish analysts expect continued pressure from the weaker nonclinical segment, legal and regulatory overhangs, and balance sheet strain to keep NeoGenomics unprofitable and at risk of missing future financial targets…"
Explore why this Narrative puts NeoGenomics at roughly fairly valued.
NeoGenomics' valuation still leaves one crucial angle unresolved
Price tags and scenarios only tell part of the story. NeoGenomics also carries specific risk checks that research has already flagged and that could change how you view the whole investment case. Take a closer look at 2 warning signs before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com