


How Investors Are Reacting To Amex (AXP) Workforce Cuts
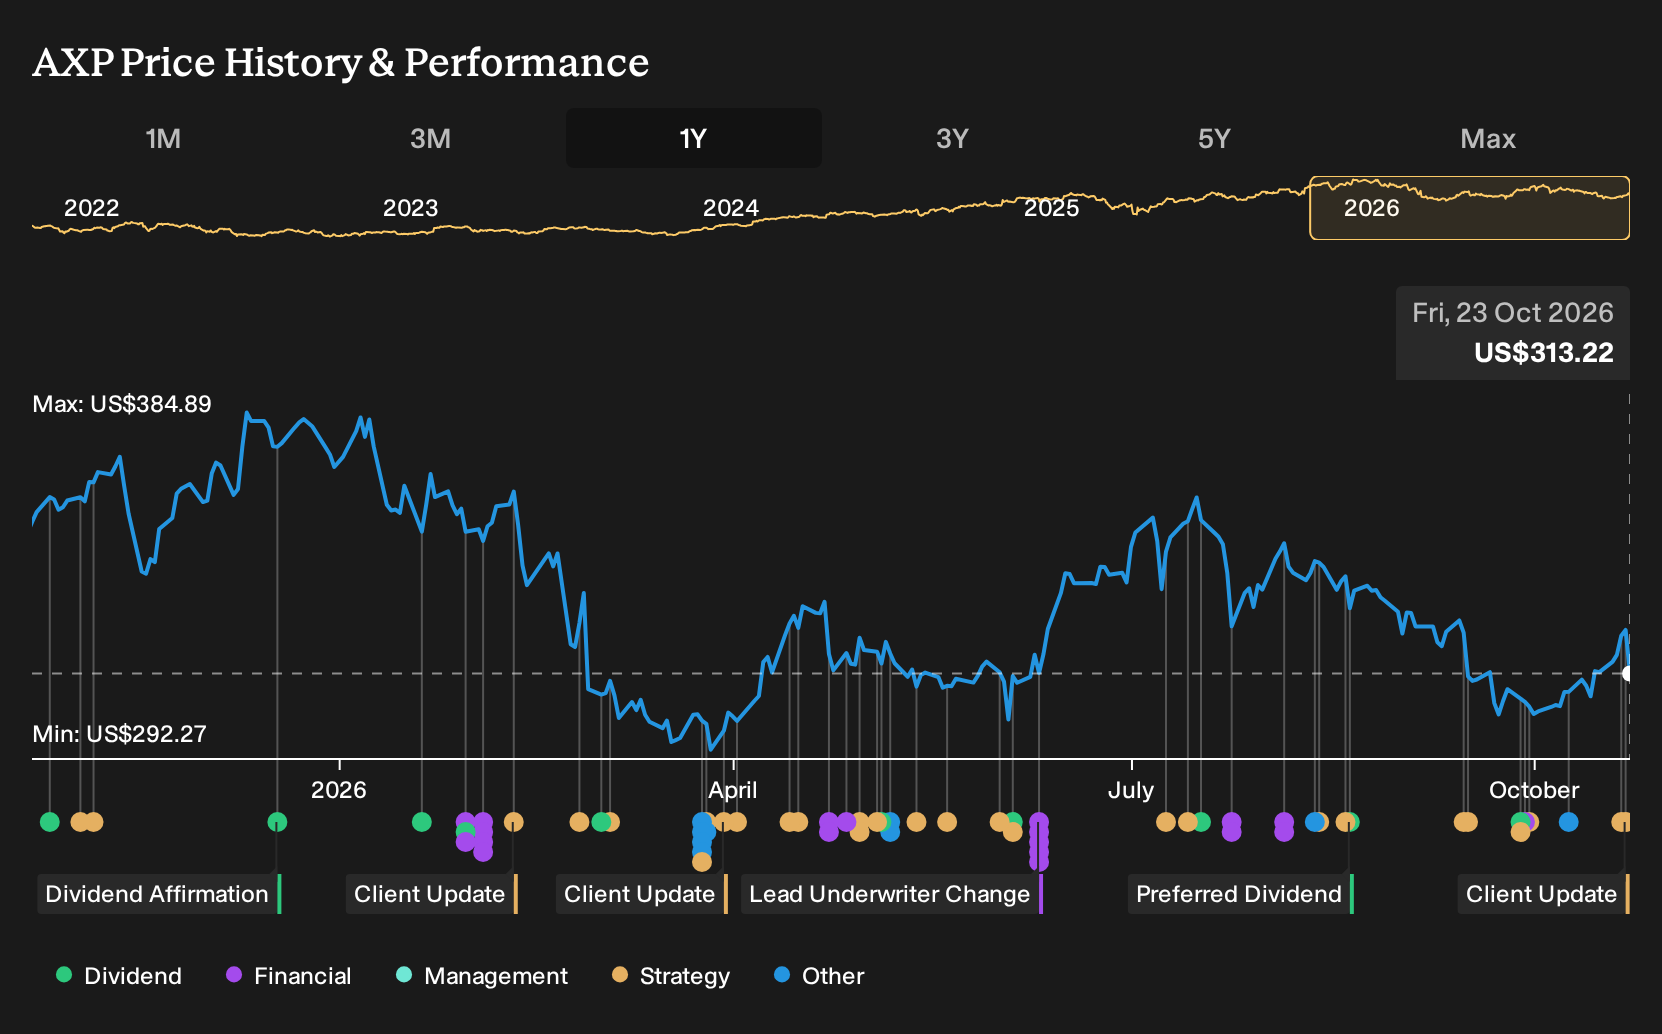
- American Express has reported strong third quarter 2026 results, raised full year EPS guidance to US$18.30 to US$18.60, and simultaneously announced a plan to cut about 5% of its global workforce as part of a restructuring linked to AI and efficiency priorities.
- The combination of higher earnings guidance and a sizeable headcount reduction highlights how American Express is trying to balance rich premium card benefits and technology investment with tighter control over operating costs and organizational complexity.
- We will now look at how American Express's workforce reduction alongside raised EPS guidance could reshape the existing investment narrative.
Compare how American Express’s mix of premium customers, AI spend and cost cuts stacks up against other potential opportunities by scanning our hand-picked 28 high quality undervalued stocks.
American Express Investment Narrative Recap
To own American Express, you need to believe its premium customer focus, high card fees and growing international reach outweigh rising reward costs and regulatory noise. The raised 2026 EPS guidance and solid Q3 profit of US$3.71b support that operating thesis. The key near term swing factor is whether strong affluent spending and fee income continue to cover heavy marketing, rewards and AI investment.
The biggest operational risk still sits in variable customer engagement spending, which is running at roughly the mid 40s as a share of revenue. Workforce cuts and AI projects are aimed at efficiency, but the restructuring charge, revenue expectations misses and pressure from exited small business co brand portfolios keep execution risk elevated.
The Airbnb partnership is the clearest operational tie in to the latest guidance and restructuring news. Folding more than one million Airbnb listings and Airbnb Luxe into Amex Travel deepens the company’s reach in travel, where its premium cardholders already concentrate spend. It also gives extra earning levers through Membership Rewards points, credits and higher earn rates for Platinum customers.
For you as a shareholder, this kind of partnership matters because the core catalysts revolve around fee income, premium engagement and international trip volume. If cardmembers shift more lodging and experiences into the American Express ecosystem, that supports billed business and net card fees, which helps offset headwinds from co brand portfolio sales and keeps the reward rich model more sustainable.
What The Latest American Express Forecasts Assume
American Express' current analyst narrative points to revenues of US$98.3b and earnings of US$15.4b by 2029. This lines up with assumptions of 11.5% yearly revenue growth and an earnings increase of about US$4.1b from US$11.3b today.
Uncover why American Express' fair value indicates an 18% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts frame American Express’s AI push and restructuring as a clear earnings catalyst. Before this news, they were mapping out revenue of about US$102.7b and earnings of roughly US$16.7b by 2029. You can compare that upbeat view with more cautious forecasts and decide which storyline feels more realistic to you.
Explore 7 other American Express fair value estimates, including one that indicates the potential for up to 40% upside from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your American Express research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for American Express. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate American Express' overall financial health at a glance.
Looking For More Investment Ideas Beyond American Express?
Once you have formed a view on American Express, it can help to compare that thesis with other businesses that have very different risk and return profiles. The Simply Wall St Screener is built for exactly that kind of side by side work, letting you filter the market around the factors that matter most to you rather than whatever is trending today.
- If capital preservation sits high on your list, start with a group of companies that our models flag as relatively resilient by scanning 30 resilient stocks with low risk scores.
- Income focused investors who want yield backed by fundamentals can zero in on potential payout candidates through 5 dividend fortresses.
- If you prefer businesses with strong balance sheets and solid underlying metrics, narrow the field using a curated list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com