


Zhaojin Mining Industry (SEHK:1818) Reshuffles Leadership And Posts Softer Earnings, Is It A Bargain?
Zhaojin Mining Industry (SEHK:1818) has been in focus after a reshuffle in senior leadership coincided with fresh nine-month earnings, combining a change in decision makers with updated financial performance data.
Those leadership changes and the latest nine month figures landed against a rough patch for Zhaojin Mining Industry’s shares. The stock was down 18.76% on a 90 day share price basis and 48.15% year to date, while the 5 year total shareholder return of 201.43% and 3 year total shareholder return of 56.00% reflect a stronger longer term outcome for investors who held through past cycles.
Spot opportunities around Zhaojin Mining Industry's leadership and earnings reset by scanning the 35 elite gold producer stocks for other gold producers that are experiencing similar management shifts and market pressure.Analysts see Zhaojin Mining Industry trading well below their targets and an intrinsic estimate, yet the share slide and softer nine month earnings keep caution high. Is this discount compensation for risk, or an overreaction that valuation does not support?
Preferred P/E of 15.4x: Is it justified?
On earnings, Zhaojin Mining Industry trades on a P/E of 15.4x, which sits above both its Metals and Mining peers and the wider Hong Kong market even after the share price pullback.
The P/E ratio links what investors pay per share to the profit the business generates per share. For a miner with exposure to gold and other metals, that yardstick often reflects how much the market is willing to pay for the earnings profile, given its growth record, commodity exposure, and balance sheet structure.
Here the stock looks expensive compared to the Hong Kong Metals and Mining industry average P/E of 8.7x and a peer group at 12.5x. The fair P/E estimate of 15.9x is very close to the current 15.4x, which suggests the valuation level could reasonably sit in this band if earnings forecasts and cash flow expectations play out as modeled.
Explore the SWS fair ratio for Zhaojin Mining Industry.
Result: Price-to-earnings of 15.4x (ABOUT RIGHT)
Still, Zhaojin Mining Industry faces clear risks if softer nine month earnings persist or if leadership changes disrupt execution on its gold and copper projects.
Find out about the key risks to this Zhaojin Mining Industry narrative.
Another view on Zhaojin Mining Industry’s value
The P/E picture tells one story for Zhaojin Mining Industry, but the SWS DCF model points to another. On that framework, HK$16.54 compares with an estimated future cash flow value of HK$22.27, which implies the shares change hands at a 25.7% discount. Is that a margin of safety, or a value trap in the making?
Look into how the SWS DCF model arrives at its fair value.
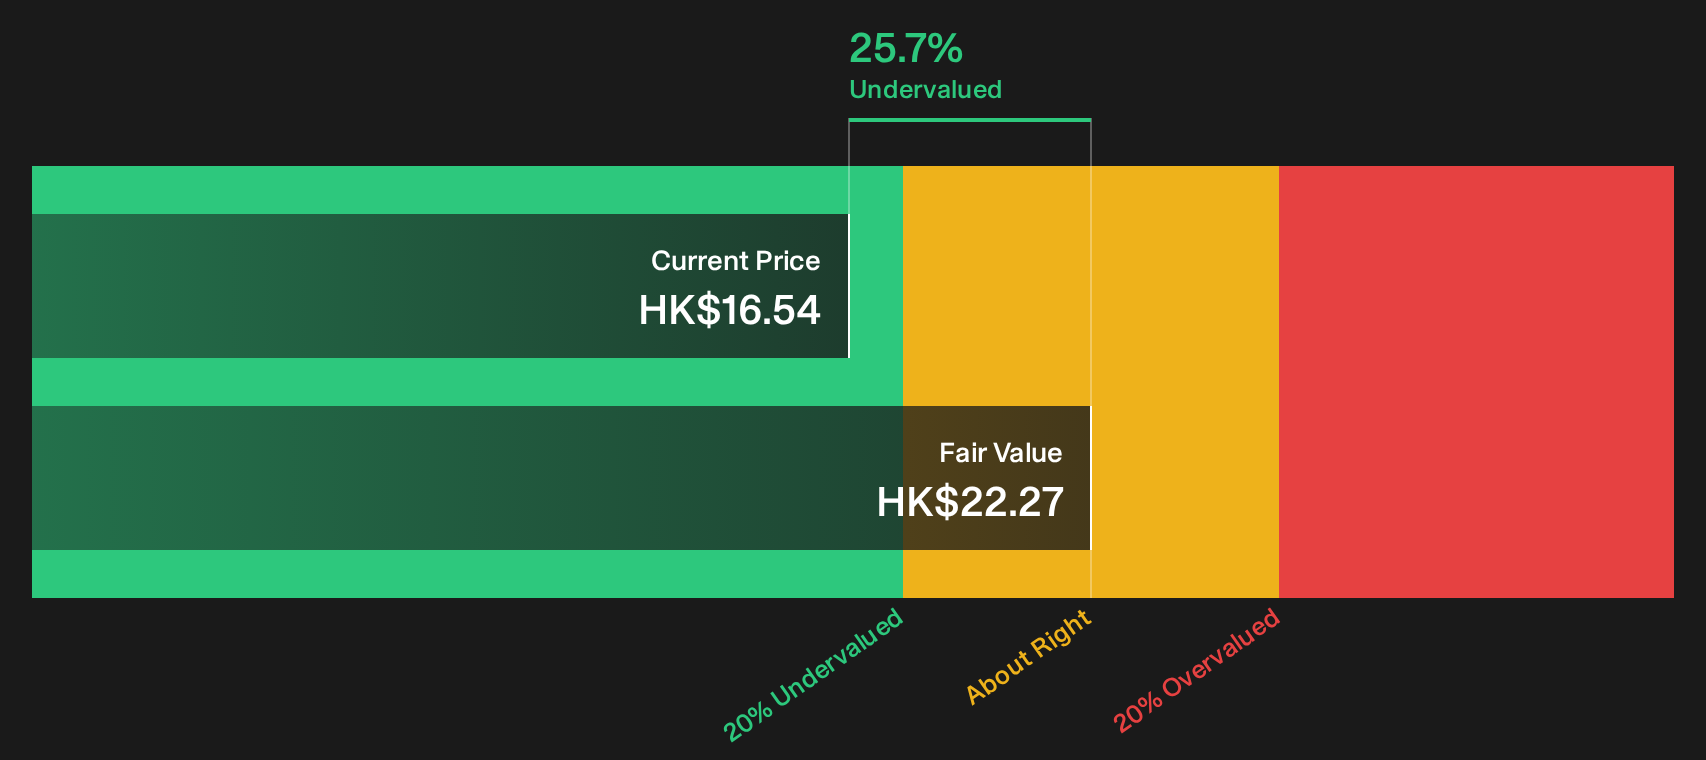
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Zhaojin Mining Industry for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 192 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the combination of leadership change, earnings pressure, and valuation gaps around Zhaojin Mining Industry seems conflicted, review the data quickly and shape your own conclusion with 3 key rewards.
Looking for more investment ideas beyond Zhaojin Mining Industry?
If Zhaojin Mining Industry is on your radar, do not stop there. Broaden your watchlist now so you are not late to the next opportunity.
- Target potential bargains by scanning the 192 high quality undervalued stocks that combine quality fundamentals with prices that currently look compressed.
- Strengthen your income focus by checking the 226 dividend fortresses that may offer higher yields alongside established payout records.
- Reduce portfolio stress by reviewing the 221 resilient stocks with low risk scores that score well on financial resilience and volatility controls.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com