


Is Shionogi (TSE:4507) Undervalued Following IDWeek 2026 Pipeline Updates?
Shionogi (TSE:4507) has drawn fresh investor attention after IDWeek 2026 showcased new data on its anti infective portfolio, including cefiderocol, XOCOVA for COVID 19 post exposure prophylaxis, and olorofim for invasive aspergillosis.
These IDWeek updates have landed against a supportive backdrop for Shionogi, with the share price at ¥3,036 and a 30 day share price return of 4.06% feeding into a solid 90 day gain of 6.32% and a 27.29% 1 year total shareholder return. Together, these figures point to momentum that has been building rather than fading.
Scan how Shionogi’s infectious disease focus compares with other healthcare players by reviewing a curated set of 10 healthcare AI stocks aligned with medical data and treatment advances.
After a 27.29% one-year return and fresh IDWeek catalysts, the key question is straightforward: does it make more sense to add Shionogi at ¥3,036 now, or wait until the valuation case looks clearer?
Price-to-Earnings of 9.8x: Is it justified?
On simple valuation terms, Shionogi looks cheap, with the shares at ¥3,036 trading on a P/E of 9.8x while still reflecting a 27.29% 1 year total shareholder return and a 2.5% dividend yield.
The P/E ratio compares the share price to earnings per share and gives a quick sense of how much investors pay for each yen of profit. For a pharmaceuticals group like Shionogi, this lens matters because profit quality, patent cycles, and pipeline visibility can all influence how much of a premium or discount the market is willing to assign.
Here, the multiple sits well below several yardsticks. The stock trades at a P/E of 9.8x against a JP Pharmaceuticals industry average of 14.4x and a peer average of 19.3x. The estimated fair P/E sits even higher at 20.6x. That combination points to a market that prices Shionogi well below both sector norms and the level the fair ratio suggests the shares could trend toward if sentiment and fundamentals align.
Explore the SWS fair ratio for Shionogi.
Result: Price-to-Earnings of 9.8x (UNDERVALUED)
Still, the recent decline in annual net income growth and Shionogi’s heavy reliance on prescription drugs leave little room for error if key therapies disappoint or face setbacks.
Find out about the key risks to this Shionogi narrative.
Another View: Shionogi Through The DCF Lens
The earnings multiple suggests Shionogi looks inexpensive, yet the SWS DCF model indicates an even larger gap. With the shares at ¥3,036 and an estimated future cash flow value of ¥7,202.55, the model presents the stock as heavily undervalued. That kind of gap raises a simple question: is the discount an opportunity or a warning about future cash generation?
For a closer look at how that cash flow view is built, and what would need to change for the gap to close, Look into how the SWS DCF model arrives at its fair value.
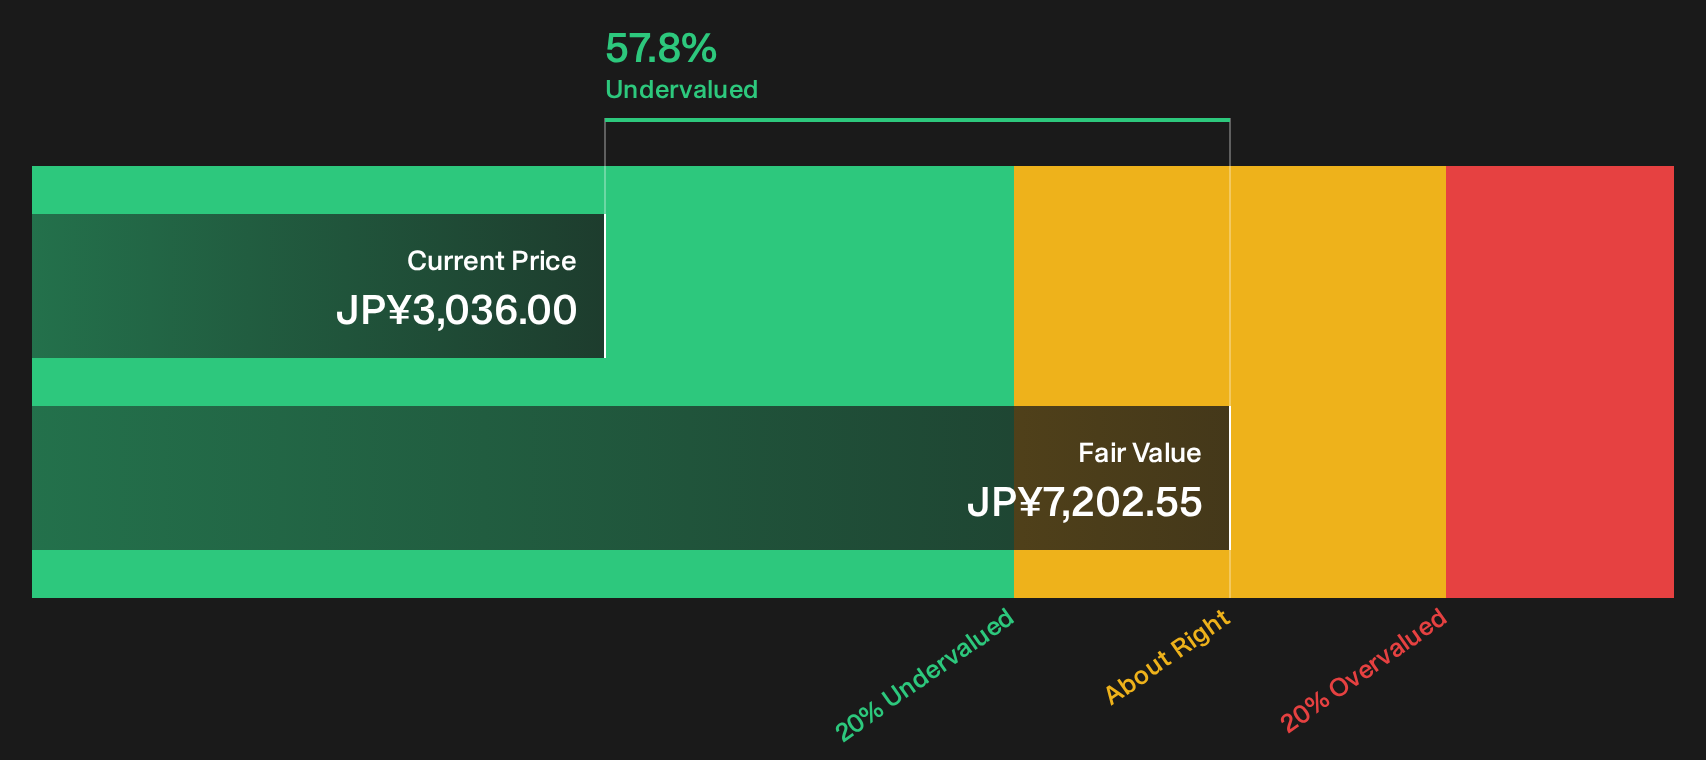
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Shionogi for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 14 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Shionogi’s valuation and pipeline can feel unclear. Move quickly from headline impressions to the actual data and shape your own stance with 4 key rewards and 2 important warning signs
Looking for more ideas beyond Shionogi?
If you stop with Shionogi, you only see part of the opportunity set. Put a wider watchlist to work so your capital is not anchored to one story.
- Hunt for overlooked quality by scanning our 72 high quality undiscovered gems, which pairs stronger fundamentals with less crowded ownership.
- Prioritize resilience and sleep easier by focusing on a 22 resilient stocks with low risk scores, which screens for sturdier financial profiles.
- Anchor your portfolio with sturdier finances by using the list of solid balance sheet and fundamentals (23 results), which highlights companies with stronger balance sheets and fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com