


Earnings And Dividend Update Could Be A Big Deal For Izumi Stock (TSE:8273)
- Izumi Co., Ltd. reported half year sales of JPY 253,907 million and net income of JPY 8,426 million, while confirming a second quarter-end dividend of JPY 15.00 per share after a three for one stock split.
- The stock split means Izumi's forecast annual dividend would equate to JPY 90.00 per share on a pre split basis, which helps investors compare payouts with prior years more clearly.
- Next, the focus shifts to how Izumi's higher net income and clarified dividend framework could influence the broader investment narrative.
What Is Izumi's Investment Narrative?
To own Izumi, you need to believe a fairly simple story. This is a domestic retailer, tied tightly to everyday spending in Japan, that is trying to steadily improve earnings while keeping its stores productive and its capital spending disciplined. The latest half year figures, with JPY 253,907 million in sales and JPY 8,426 million in net income, point to a business that is at least holding its ground operationally while tightening profit margins.
The announced merger of wholly owned units like Youme Mart Kumamoto and SUNLIFE matters more than it first appears. A cleaner structure can cut overhead, sharpen buying power and make new store investments easier to weigh. The confirmed dividend, adjusted for the three for one split, reinforces that cash returns remain a priority, even as questions linger around free cash flow cover and relatively low return on equity.
Yet there is a tension inside that income story that could start to bite if ...
There's only one way to know the right time to buy, sell or hold Izumi. Head to Simply Wall St's company report for the latest analysis of Izumi's Fair Value.
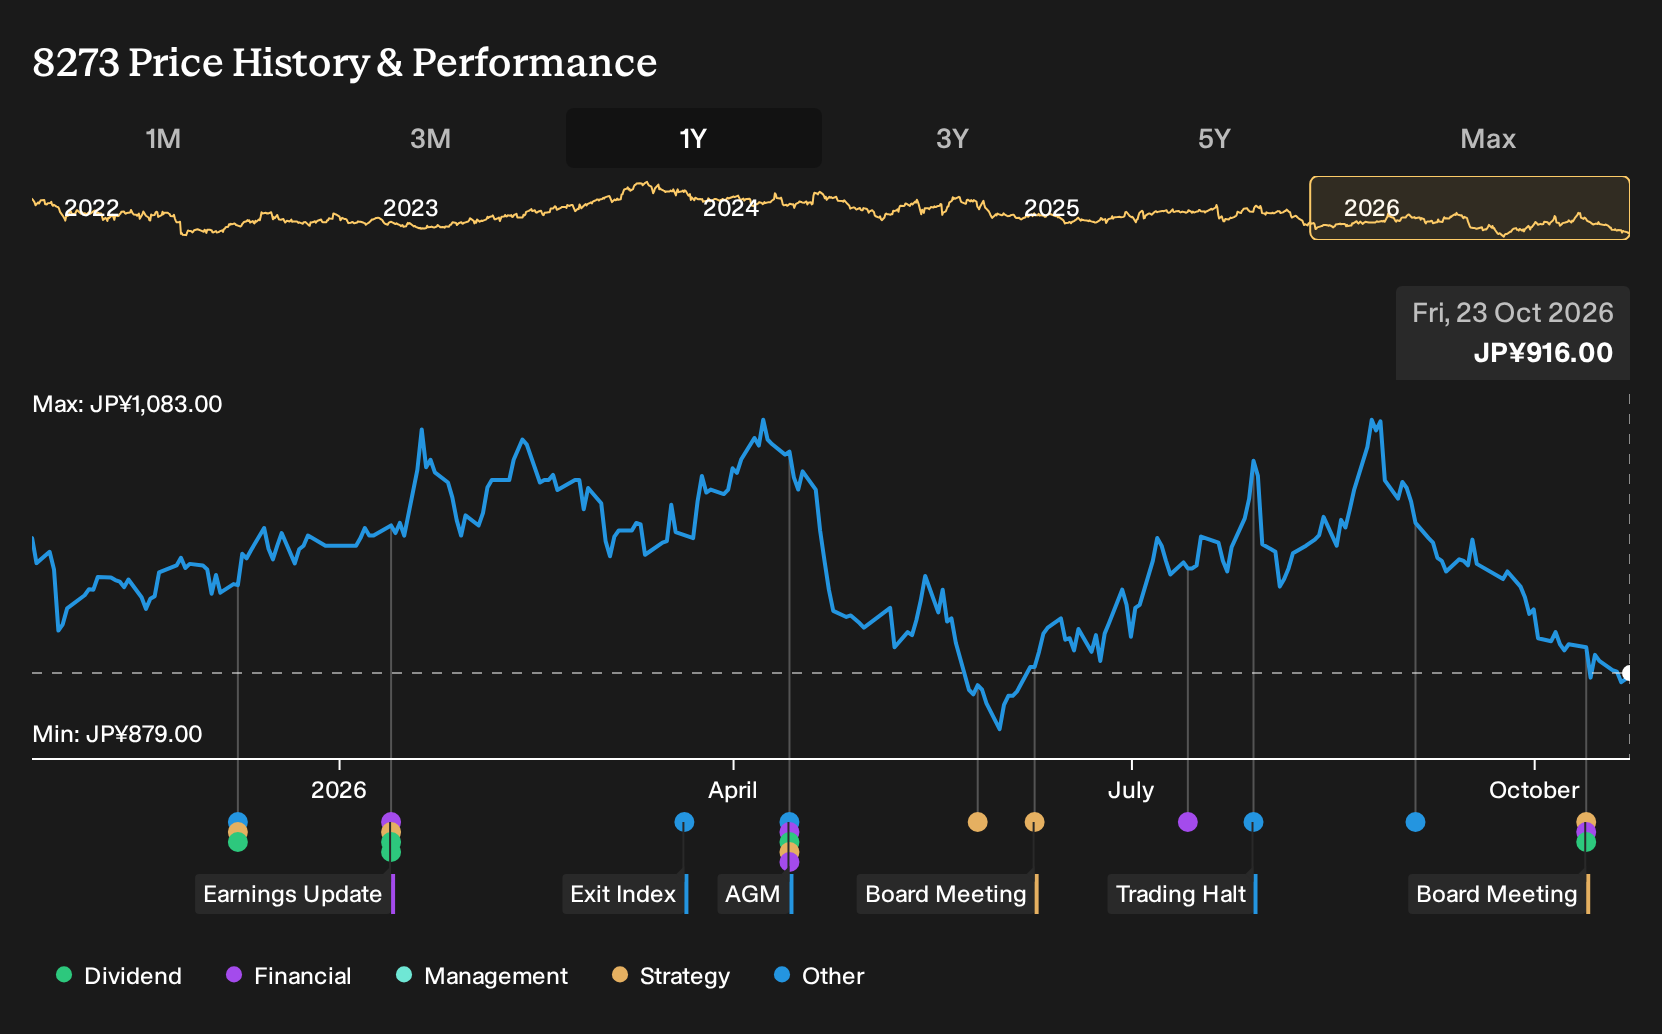
Form Your Own Verdict
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Izumi research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Izumi. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Izumi's overall financial health at a glance.
Looking For More Ideas Beyond Izumi?
If Izumi's mix of income and steady operations appeals to you, it can help to line it up against other listed businesses that share some of the same traits. The Simply Wall St Screener lets you filter for different combinations of quality, balance sheet strength and yield so you can quickly narrow a long list of tickers down to a manageable watchlist.
- For investors who want income with fewer balance sheet surprises, start with companies that pair resilient finances with dependable metrics through the list of solid balance sheet and fundamentals (23 results).
- If you are hunting for stocks where valuation metrics look more forgiving relative to fundamentals, scan the 14 high quality undervalued stocks to see which tickers fit that profile today.
- For readers who care most about reliable cash distributions, sort for income focused opportunities using the 29 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com