


3 AI Infrastructure Stocks Retail Investors Are Watching Beyond Nvidia And Broadcom
Explosive AI data center spending has turned the quiet plumbing of the internet into one of the loudest stories in markets, with Nvidia and Broadcom at the center of eye catching revenue figures. Investors watching this surge risk being late to where capital and capacity are moving. This article walks through three stocks linked to that same AI buildout and explains how the recent news could matter for your portfolio decisions.
The stocks in this article are just a starting sample, and the full screen surfaced 47 more large cap cloud and AI platform companies with equally compelling narratives that are not covered here. To identify and analyze the highest conviction opportunities in this space, go straight to the Global AI Hyperscaler and Cloud Platform Leaders screener.
Insight Enterprises (NSIT)
Insight Enterprises is closely tied to the AI hyperscaler theme by helping enterprises combine cloud platforms, data center equipment, and AI tools into workable solutions. This positions the company within the flow of capital as AI infrastructure spending extends beyond chip suppliers.
Insight Enterprises integrates multicloud, cybersecurity, data and AI, and device solutions for enterprises worldwide, generating about US$6.9b of revenue in North America, US$1.4b in EMEA, and US$276 million in APAC, with a market value around US$5.0b.
"The rapid adoption of artificial intelligence and the increasing urgency for enterprises to modernize IT infrastructures, especially to support AI workloads, remains a live driver for Insight Enterprises as clients continue to invest in servers, storage and networking, which could support infrastructure revenue and related services earnings."
An important question is what happens if a single assumption about how efficiently Insight Enterprises converts that AI project flow into lasting margin gains does not hold.
If that margin story matters to your thesis, read the full narrative for Insight Enterprises to see where Insight Enterprises could be quietly decoupling from the headline AI trade.

Keysight Technologies (KEYS)
Keysight Technologies plugs directly into the Global AI Hyperscaler and Cloud Platform Leaders theme by supplying the test gear and design software that hyperscalers, chipmakers and equipment vendors use to validate high speed data center hardware and communications infrastructure before it ever reaches AI racks.
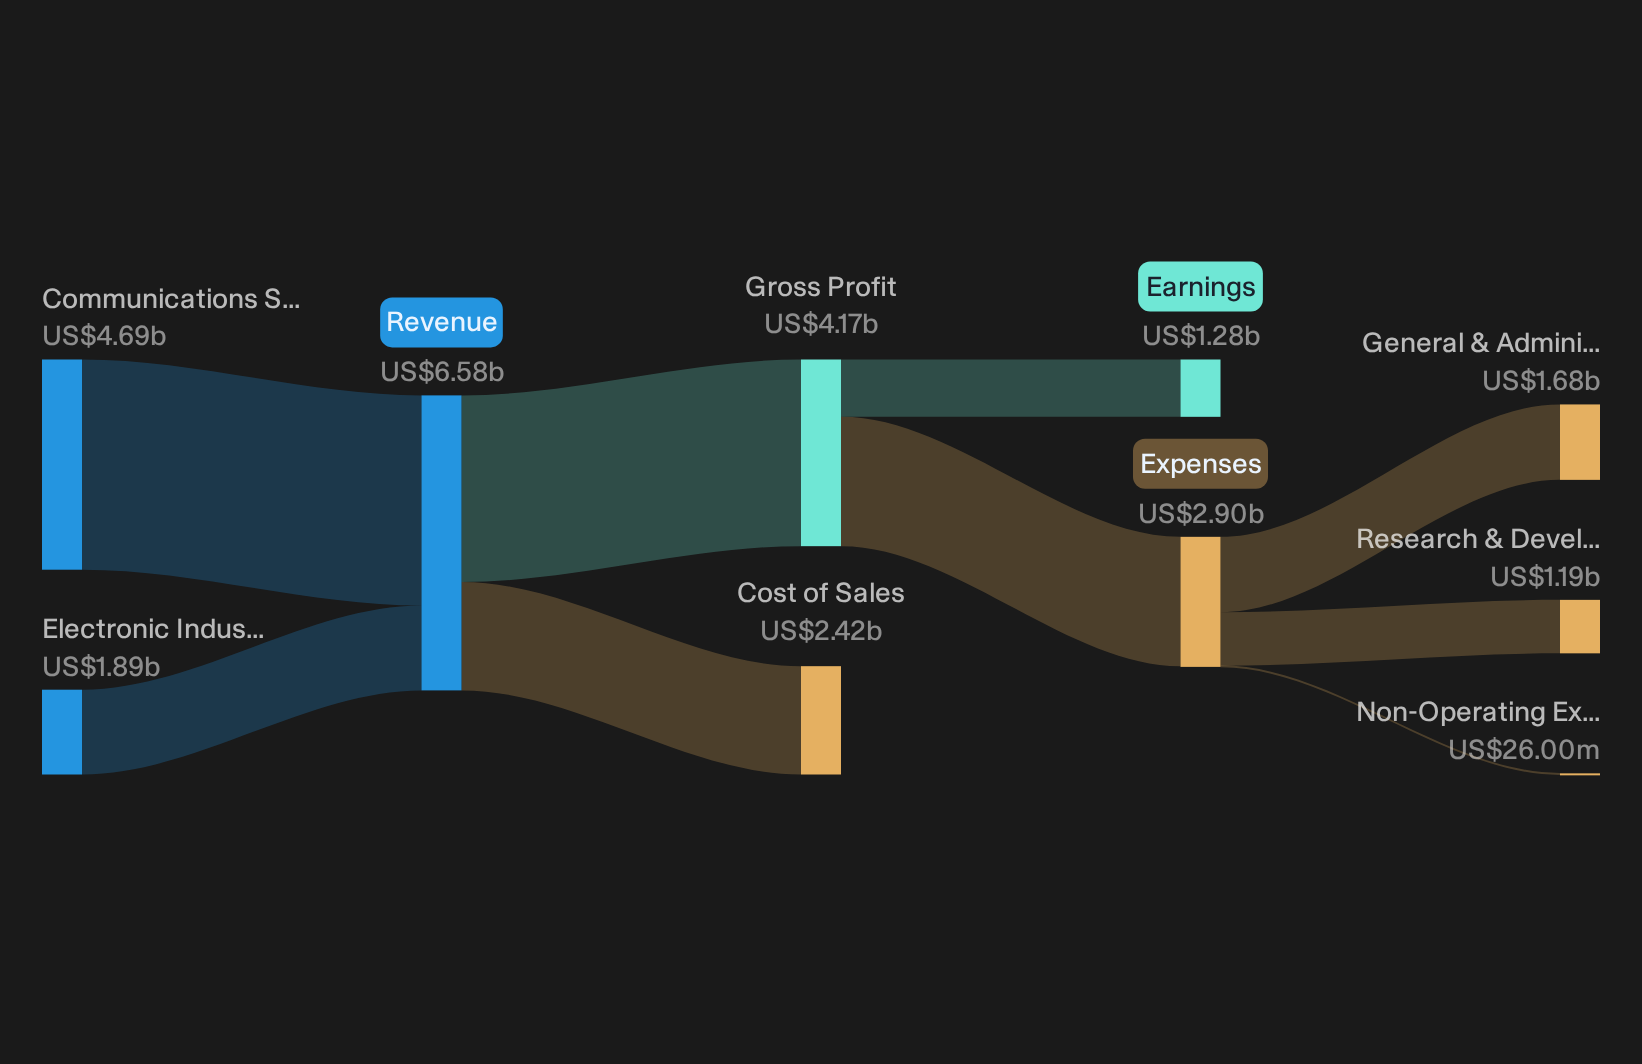
Keysight Technologies, a US$53.0b test and measurement specialist, provides design, simulation and validation tools across wireless, data center, aerospace, defense, automotive and semiconductor markets. It generates about US$4.7b from its Communications Solutions Group and US$1.9b from its Electronic Industrial Solutions Group.
"Adoption of AI across digital infrastructure is now visible in Keysight Technologies reporting, with commercial communications delivering its first US$1b quarter and wireline revenue surpassing wireless in Q3 2026. If supply constraints persist or worsen, the timing mismatch between strong orders and revenue recognition could limit reported revenue growth and dampen earnings."
What happens to Keysight Technologies earnings power if one quiet supply bottleneck keeps interrupting the flow between AI orders and recognized revenue?
If that supply squeeze is what you keep circling back to, read the full narrative for Keysight Technologies to see whether near term constraints are masking longer term earnings power.
IONOS Group (XTRA:IOS)
IONOS Group gives this AI hyperscaler and cloud platform screen a European twist, running its own data centers and selling cloud infrastructure and web tools directly to smaller businesses that want AI powered services without building anything themselves.
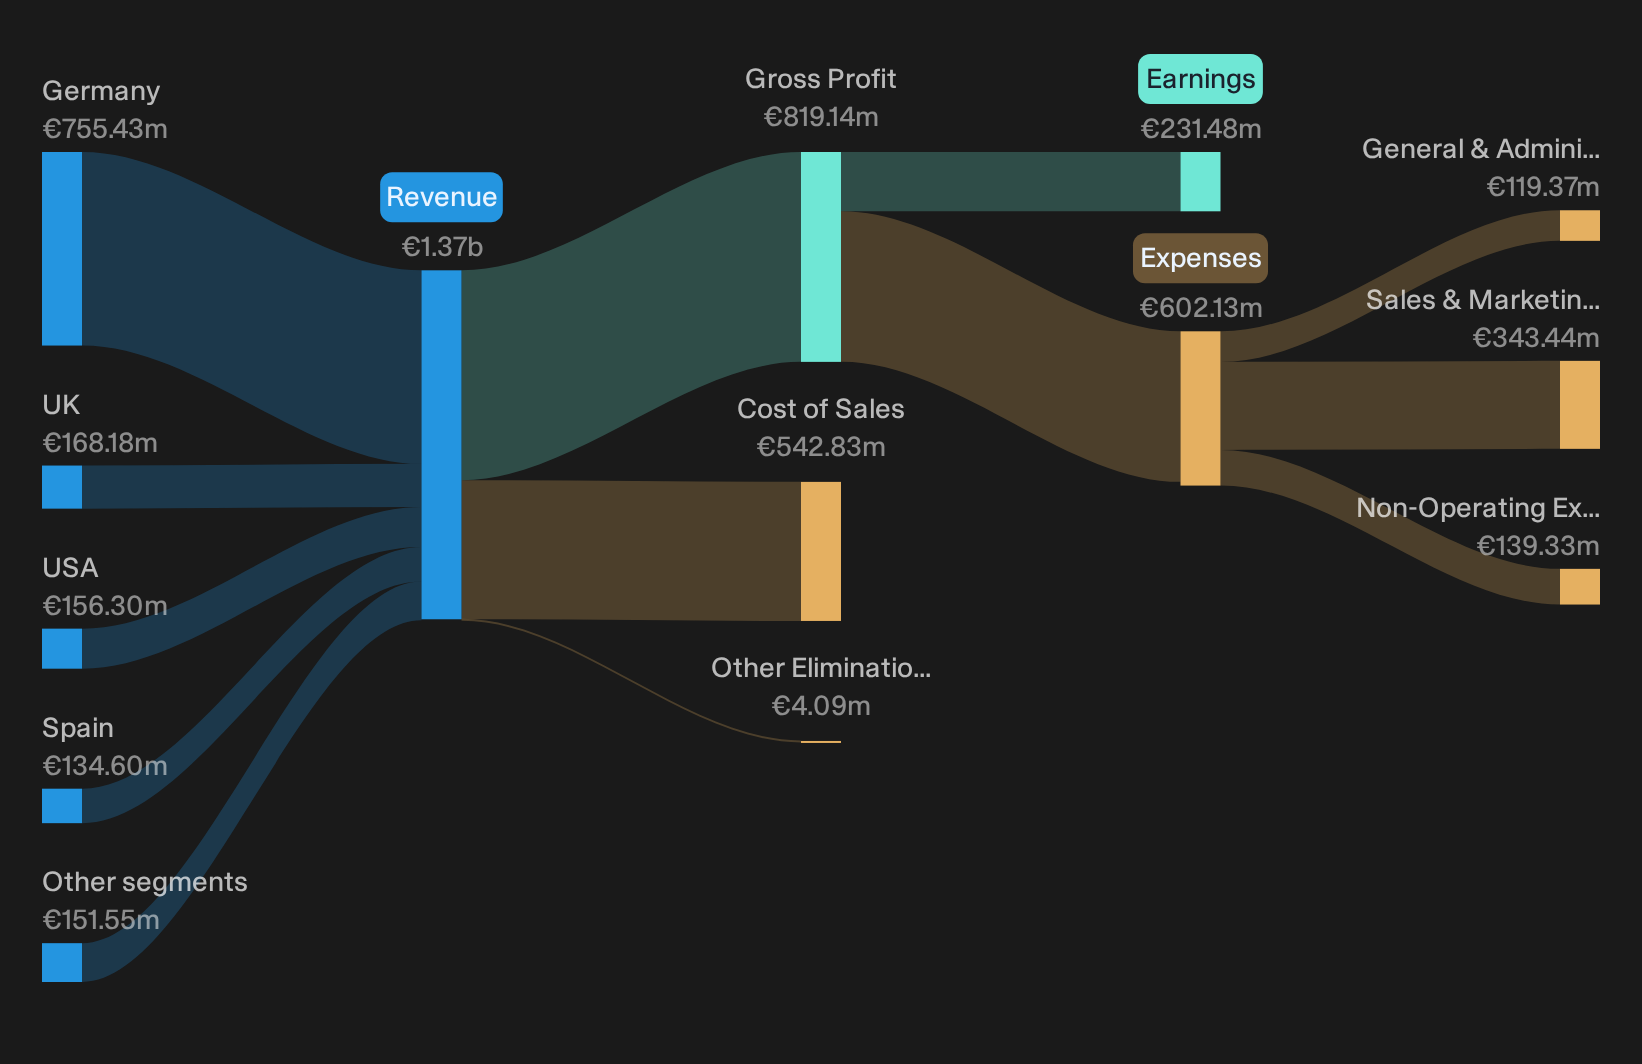
IONOS Group runs subscription based web presence, productivity and cloud infrastructure products, earning about €1.36b from its combined Web Presence & Productivity and Cloud Solutions segment, and the stock carries a roughly €4.8b market value.
"Expanding AI-led products in Web Presence & Productivity, with management indicating AI contributed around 20% of incremental revenue in 2025 and is expected to reach about 50% in 2026 and 80% by 2028, positions IONOS Group to lift subscription revenue and support higher earnings over time."
The real test comes if one planned shift in how that AI heavy subscription mix feeds through to margins and cash generation proves too optimistic.
If that margin reset is what worries you, read the full narrative for IONOS Group to see whether accelerating AI subscriptions are masking risk or quietly reshaping IONOS Group.
Seeking Fresh Alternatives Before They Fly
Fresh breakouts can move fast while information decay creeps in. Scan curated ideas before momentum runs away, while it still matters and is under the radar for now.
- Spot cash rich companies before the crowd rotates into them by checking the 27 high quality undervalued stocks that filters for resilient balance sheets and robust cash generation.
- Explore the next wave of automation momentum by scanning the tightly curated 95 robotics and automation stocks that tracks businesses building the hardware and software behind smarter factories and logistics.
- Review potential opportunities in grid upgrades by using the focused 42 power grid technology and infrastructure stocks highlighting businesses tied to transmission, stability tools and next generation energy infrastructure.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com