


Q3 Earnings Could Be A Key Test For Align Technology Stock (ALGN)
- Align Technology plans to report Q3 2026 results on October 28 after market close, with recent commentary highlighting firm Clear Aligner volumes across regions and continued demand from both orthodontists and general dentists.
- The mix of resilient Invisalign case activity and higher scanner placements, supported by exocad related services, signals that Align Technology is still leaning heavily into its end to end digital treatment ecosystem despite pressures in its Imaging Systems and CAD/CAM Services segment.
- We will now look at how Align Technology's upcoming Q3 earnings release and aligner volume trends may influence its investment narrative.
Scan beyond Align Technology and size up other dental and medical device players with resilient demand profiles using our hand picked 34 healthcare AI stocks as a starting universe.
Align Technology Investment Narrative Recap
To own Align Technology, you need to be comfortable with a story where clear aligners remain the engine, and the digital workflow keeps doctors in its ecosystem. The upcoming Q3 report matters most for confirming that Invisalign volumes stay firm across regions, since that flow of cases underpins the thesis around earnings compounding and margin improvement.
The biggest near term swing factor is whether resilient international and DSO demand can fully offset any ongoing softness in North America retail Invisalign activity. The main risk still sits in Systems and Services. A mix that leans further toward lower priced scanner options could keep pressure on that segment’s revenue and group margins.
The most relevant update is Align Technology guiding to release Q3 2026 earnings on October 28, framed by commentary that clear aligner volumes have held up well while scanner placements increased. That pairing matters, as it ties today’s Invisalign revenue to tomorrow’s potential case starts when more dentists adopt the digital platform.
This print is an operational check in on two linked catalysts. Clear aligner volume trends show whether underpenetrated regions and DSO channels are doing the heavy lifting today. Scanner and exocad activity gives a read on how effectively the business is seeding future Invisalign demand while managing the revenue headwind from lower upfront pricing in Systems and Services.
What Current Forecasts Assume For Align Technology
Align Technology's current analyst narrative ties together moderate growth expectations with a step up in profitability. Consensus models point to revenue increasing by 4.7% per year over the next three years, while profit margins are expected to move from 10.0% today to 15.7% by around 2029. Earnings are modeled to rise from US$413.6 million today to US$746.0 million by that same 2029 timeframe, with some analysts projecting as much as US$864.6 million. Those projections sit alongside an assumption that the share count drifts lower by about 0.99% annually over the next three years, which would support earnings per share even if top line growth tracks the mid single digit pace currently embedded in the consensus.
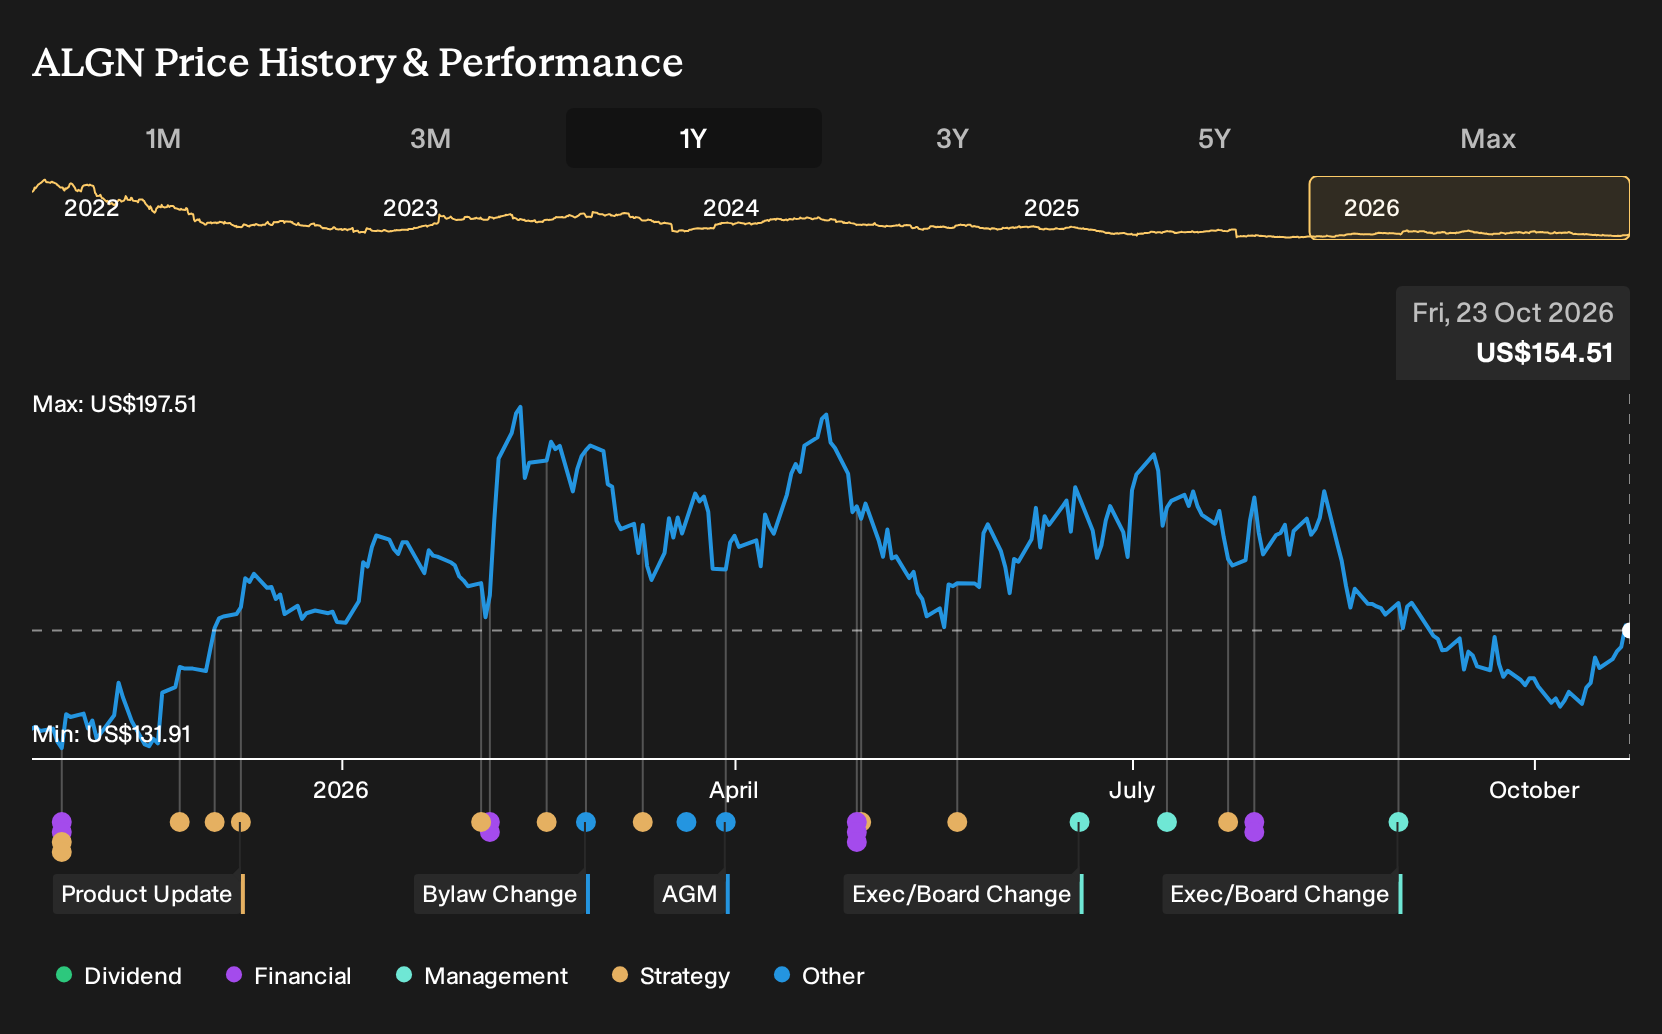
On these numbers, analysts are effectively asking investors to accept a modest de rating in the stock while still factoring in higher projected profits. The current P/E multiple of 24.7x would need to ease to 22.9x on the forecast 2029 earnings. This is just below the stated 24.5x level for the wider US medical equipment peer group. Discounting at about 7.5% and using the projected 2029 profit of US$746.0 million yields a consensus price target of US$199.21 compared with a spot price of US$143.54. Individual analyst targets range from US$155.00 to US$235.00. For investors tracking Align Technology, a central question is whether the clear aligner and scanner ecosystem can deliver the modeled revenue growth and margin uplift that these figures assume.
Align Technology's narrative projects US$4.8b revenue and US$746.0 million earnings by 2029. This is based on 4.7% yearly revenue growth and an earnings increase of about US$332.4 million from current earnings of US$413.6 million.
Uncover why Align Technology's fair value indicates a 29% potential upside to its current price before the market closes that gap.
Exploring Other Perspectives
One alternate view on Align Technology leans heavily on the clear aligner catalyst. The most optimistic analysts were penciling in about US$4.9b of revenue and US$862.8 million of earnings by 2029, compared with US$4.8b and US$746.0 million in the baseline. Those pre Q3 estimates may shift once the October 28 update lands, so treat this as a starting point and compare several viewpoints before deciding how the story fits with your own expectations.
Explore 5 other Align Technology fair value estimates, including one that suggests as much as 94% upside from the current price!
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Align Technology research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Align Technology. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Align Technology's overall financial health at a glance.
Looking For More Investment Ideas Beyond Align Technology?
If the Align Technology story has sharpened your focus on quality and risk, broaden that shortlist with a few targeted ways to scan the market using the Simply Wall St Screener.
- For investors hunting for potentially mispriced opportunities backed by solid fundamentals, start with a curated pool of 27 high quality undervalued stocks that may warrant a closer look.
- If income consistency matters most for your portfolio, anchor your watchlist around 5 dividend fortresses that combine higher yields with a focus on resilience.
- When capital protection is front of mind, filter the market for 30 resilient stocks with low risk scores to see which companies might better fit a more cautious approach.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com