


Should AI Growth Plans Require Action From ExlService Holdings Stock Investors?
- ExlService Holdings has seen its share price deliver a 72.5% return over the past five years, while recent analysis suggests the stock is trading below an estimated intrinsic value based on discounted cash flow work.
- The business is using a large credit facility and a sizable buyback program to support AI-focused expansion, which may also affect earnings per share through a lower share count.
- This article examines how ExlService Holdings' investment narrative is influenced by perceived undervaluation and its push into AI-driven revenue.
Scan other potential AI beneficiaries that are moving on similar themes to ExlService Holdings through our hand-picked list of 39 profitable AI stocks that aren't just burning cash.
ExlService Holdings Investment Narrative Recap
Owning ExlService Holdings means buying into the idea that data and AI led services can keep pulling a larger share of client spend across insurance, healthcare and financial services. In the near term, the focus is on execution in AI centric projects and integration of acquired capabilities, while still keeping digital operations reliable for large enterprise customers.
The most immediate swing factor is how effectively ExlService Holdings converts its US$1b credit facility and higher AI related capex into usable products and client wins. The key risk is that big clients could lean more on internal or third party AI tools, which could limit demand for outsourced processes and higher value AI services.
The capital allocation update that matters most here is the combination of the US$1b credit line and the two year US$500m buyback program. This marks a period in which balance sheet choices, alongside new contracts, have a direct influence on earnings per share and financial flexibility.
If ExlService Holdings executes M&A in AI model training and evaluation in line with the iMerit acquisition, that credit capacity becomes an operational lever rather than purely a financial one. On the flip side, reliance on external borrowing as the main funding source means investors need to watch interest costs and how quickly any acquired AI or data assets translate into stable revenue streams.
ExlService Holdings Analyst Growth Setup
ExlService Holdings' current AI story is pinned to a set of explicit analyst assumptions that try to translate its data led operations into future cash flows. Rather than just talking about AI ambition, the forecast ties specific growth, margin and valuation numbers to what would need to happen by the end of the decade.
For the top line, analysts are building their models on ExlService Holdings delivering 12.4% yearly revenue growth over the next three years. That pace reflects expectations around AI infused projects, deeper penetration in regulated sectors and incremental contributions from acquisitions like iMerit, all feeding into a larger addressable pool of client spend.
Profitability in those forecasts does not rest on a huge overhaul. The model moves net profit margins from 11.2% today to 11.7% in three years, which assumes some mix shift into higher value AI and IP rich work without requiring a dramatic overhaul of the cost base. For you as a reader, the key question is whether a 0.5 percentage point uplift in margins feels realistic given wage pressure, compliance spend and the incremental cost of more complex AI tools.
On the earnings line, analysts are looking for profit to reach US$372.5 million by 2029 from US$250.0 million today. That implies an earnings increase of roughly US$122.5 million, with a consensus view that this step up is achievable if ExlService Holdings continues to grow its AI related offerings and keeps utilization high across delivery centers.
Valuation assumptions layer on top of this earnings bridge. The current setup assumes the stock would trade on a P/E of 19.7x those 2029 earnings, compared with 21.7x today and against a current US Professional Services sector P/E of 21.3x. In plain terms, the scenario behind the analyst price target combines higher earnings with a slightly lower multiple, which means the heavy lifting in their view comes from profit growth, not a richer valuation label.
The model also bakes in a shrinking share count. Analysts expect shares outstanding to fall by 4.47% each year for the next three years, which links directly back to the US$500m buyback program. If management sticks to that plan, earnings per share could benefit even if overall profit grows at a steadier clip, because the same dollar of earnings would be spread across fewer shares.
ExlService Holdings' narrative projects US$3.2b revenue and US$372.5 million earnings by 2029. This rests on 12.4% yearly revenue growth and an earnings increase of about US$122.5 million from US$250.0 million today.
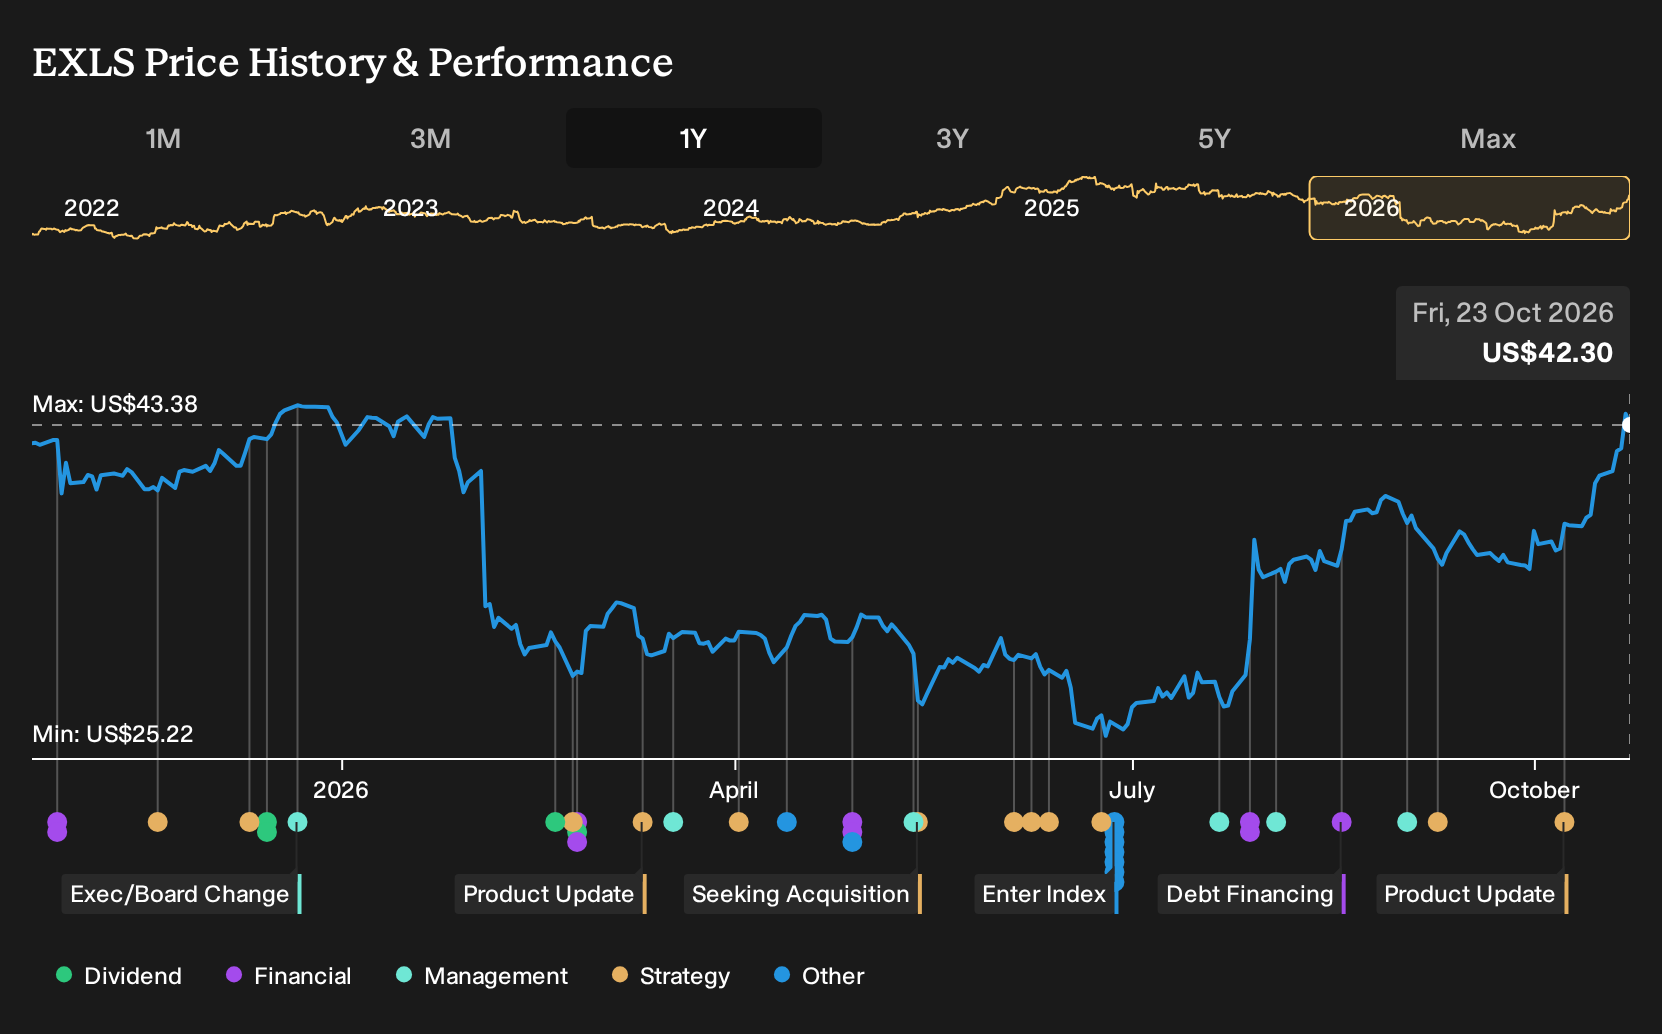
To tie everything together into a single marker, analysts have clustered around a consensus price target of US$44.62, with the most optimistic sitting at US$48.0 and the most cautious at US$39.0. With the stock at US$35.75 as of late October 2026, that central target is 19.9% higher. Readers need to judge whether the combination of mid teens style revenue growth, modestly higher margins, ongoing AI spend and consistent buybacks is credible enough to bridge the gap implied by current models.
Discover how ExlService Holdings' fair value indicates a 5% potential upside to its current price that could close sooner than you expect.
Exploring Other Perspectives
You have a different angle available here. The most optimistic analysts lean into ExlService Holdings treating AI talent as the real bottleneck, not client demand, and they were pencilling in US$3.3b of revenue and US$397.1 million of earnings by 2029 before this news. Those views may shift, so compare them with your own expectations.
Explore 2 other ExlService Holdings fair value estimates, including one that suggests as much as 92% upside from the current price!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your ExlService Holdings research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for ExlService Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ExlService Holdings' overall financial health at a glance.
Looking For More Investment Ideas Beyond ExlService Holdings?
If you want to stress test your view on ExlService Holdings, compare it with other companies that fit different risk and quality profiles using the Simply Wall St Screener.
- For investors who care most about durable balance sheets and robust fundamentals, start with this list of solid balance sheet and fundamentals (25 results) as a reference set for financial strength.
- If value is your priority and you prefer companies that trade below what their fundamentals might imply, benchmark ExlService Holdings against a curated group of 27 high quality undervalued stocks to see how it stacks up.
- When you want measured risk and steadier profiles, broaden your watchlist with 30 resilient stocks with low risk scores that score well on resilience and downside control.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com