


Supply Network (ASX:SNL) Could Be 28% Below Fair Value As Expansion Plans Build
Supply Network (ASX:SNL) is back in focus after reporting sales revenue of A$403.1 million and profit after tax of A$47.6 million, along with significant investment in branches and IT systems across Australia and New Zealand.
Recent trading action suggests investors are still warming to Supply Network. The share price is at A$35.30, with a 90 day share price return of 6.78% and a year to date gain of 9.93%, even though the 1 year total shareholder return has slipped 2.02%. Over longer horizons, momentum looks stronger, with total shareholder returns of about 163% over three years and roughly four times over five years. This frames the latest branch and IT investments as part of a much longer rerating story rather than a one off reaction to this result.
Spot similar rerating stories by scanning 15 high quality undiscovered gems with strong fundamentals that, like Supply Network, are reinvesting heavily into their own growth engines.Supply Network now trades at a clear discount to both analyst targets and estimated fair value after a strong multi year run. Is that a simple mispricing, or is the market sensibly pricing in execution risk on its expansion plans?
Price-to-Earnings of 32.4x: Is it justified?
On simple valuation maths, Supply Network screens as expensive, with a P/E of 32.4x that investors are paying at A$35.30 per share, even though the stock is flagged as trading at a 28% discount to an estimated fair value of A$49 based on the SWS DCF model.
The P/E ratio compares the current share price to per share earnings, so it effectively shows how many dollars the market is willing to pay for A$1 of profit. For a parts distributor like Supply Network, investors often watch this closely because it reflects how confident the market is that earnings can keep compounding from here.
Here the multiple points to a rich price tag. The P/E of 32.4x is higher than the peer average of 23.2x and far above the global Retail Distributors group on 15.3x. It also sits well above an estimated fair P/E of 17.2x that the regression based fair ratio suggests the stock could gravitate toward if sentiment cools or profit growth simply tracks expectations.
Explore the SWS fair ratio for Supply Network.
Result: Preferred multiple of Price-to-Earnings of 32.4x (OVERVALUED)
Still, the Supply Network story can be knocked off course if branch and IT spending fails to lift returns, or if expansion strains operations in Australia and New Zealand.
Find out about the key risks to this Supply Network narrative.
Another View: What the SWS DCF Model Says About Supply Network
The earnings multiple paints Supply Network as expensive, yet the SWS DCF model points the other way. At A$35.30, the shares are flagged as trading about 28% below an estimated fair value of A$49. That difference in message raises a simple question: which risk matters more to you, paying up on a P/E, or trusting a cash flow forecast?
Look into how the SWS DCF model arrives at its fair value.
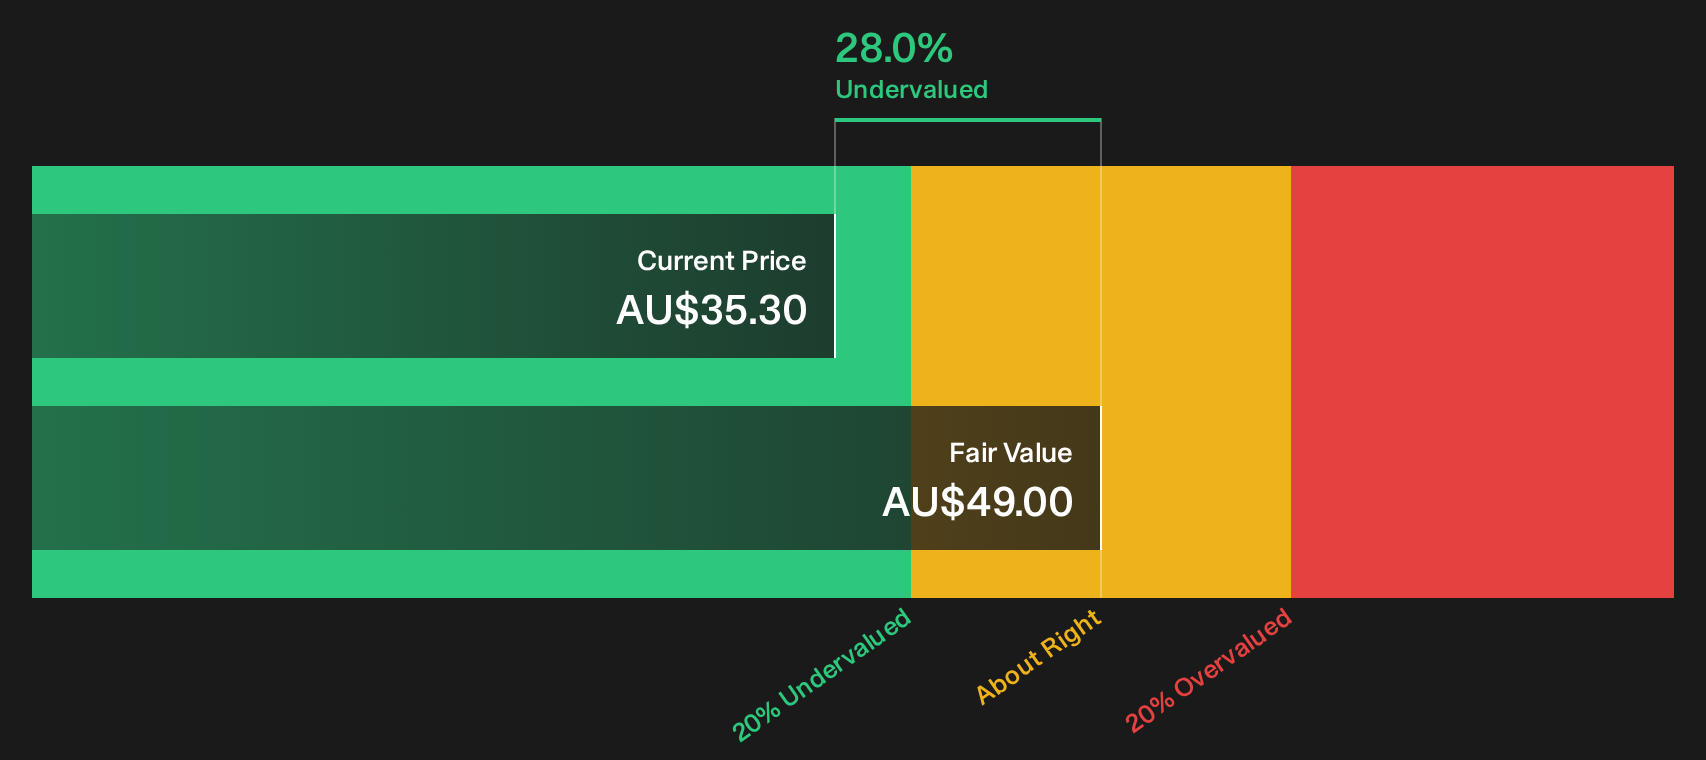
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Supply Network for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 4 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Plenty in this review leans optimistic about Supply Network, yet the real test is how the data stacks up for you personally. Pressure test that optimism against the 3 key rewards.
Looking for more investment ideas beyond Supply Network?
Once you have a view on Supply Network, the next edge often comes from lining it up against other opportunities that fit your style and risk tolerance.
- Target potential mispricings by scanning a curated set of companies that look cheap on quality metrics through the 4 high quality undervalued stocks.
- Prioritise resilience and capital strength by checking a list of solid balance sheet and fundamentals (12 results) that can help you avoid fragile businesses before trouble hits.
- Hunt for tomorrow's breakouts early by reviewing a focused 21 elite penny stocks with strong financials list before other investors start paying attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com