


Brinker International (EAT) Slides After A Sharp Pullback, Is The Stock Still Cheap?
Brinker International (EAT) has drawn fresh attention after recent share price pressure, with the stock down about 13% over the past month and roughly 2% over the past 3 months.
The latest pullback extends a weaker stretch, with Brinker International’s share price down 3.9% in the last day and 10.5% over the past week, even though the year-to-date share price return is 20.6% and the 1-year total shareholder return is 43.5%. This highlights strong longer term momentum despite fading short term sentiment.
Scan how Brinker International’s latest pullback compares with other potential rebound candidates across our hand picked 27 high quality undervalued stocks.
After that sharp pullback, Brinker International now trades well below the average analyst target and slightly above one intrinsic estimate. Is the current price discount wide enough to call this weakness an opportunity, or is it just noise?
Most Popular Narrative: 30% Undervalued
Brinker International closed at $182.70, compared with a widely followed fair value narrative of $262.59 that is built using an 8.89% discount rate. The gap between those two figures sits on a foundation of detailed assumptions about Chili's unit economics, capital allocation, and how long current restaurant level profitability can be maintained.
Planned Chili's unit growth of 20 to 30 new locations per year by fiscal 2029, together with a program to reimage roughly 10% of the system annually where early remodels are tied to 3% to 5% sales lifts and targeted $5 million to $6 million AUVs in new builds, can add a new layer of volume driven revenue growth and contribute to operating leverage.
See why 31 investors see Brinker International as 30% undervalued.
Result: Fair Value of $262.59 (UNDERVALUED)
Still, the narrative around Brinker International could wobble if Chili's value offers fail to offset rising labor and commodity costs, or if Maggiano's ongoing traffic softness persists.
Find out about the key risks to this Brinker International narrative.
Another View: Brinker International Through A Cash Flow Lens
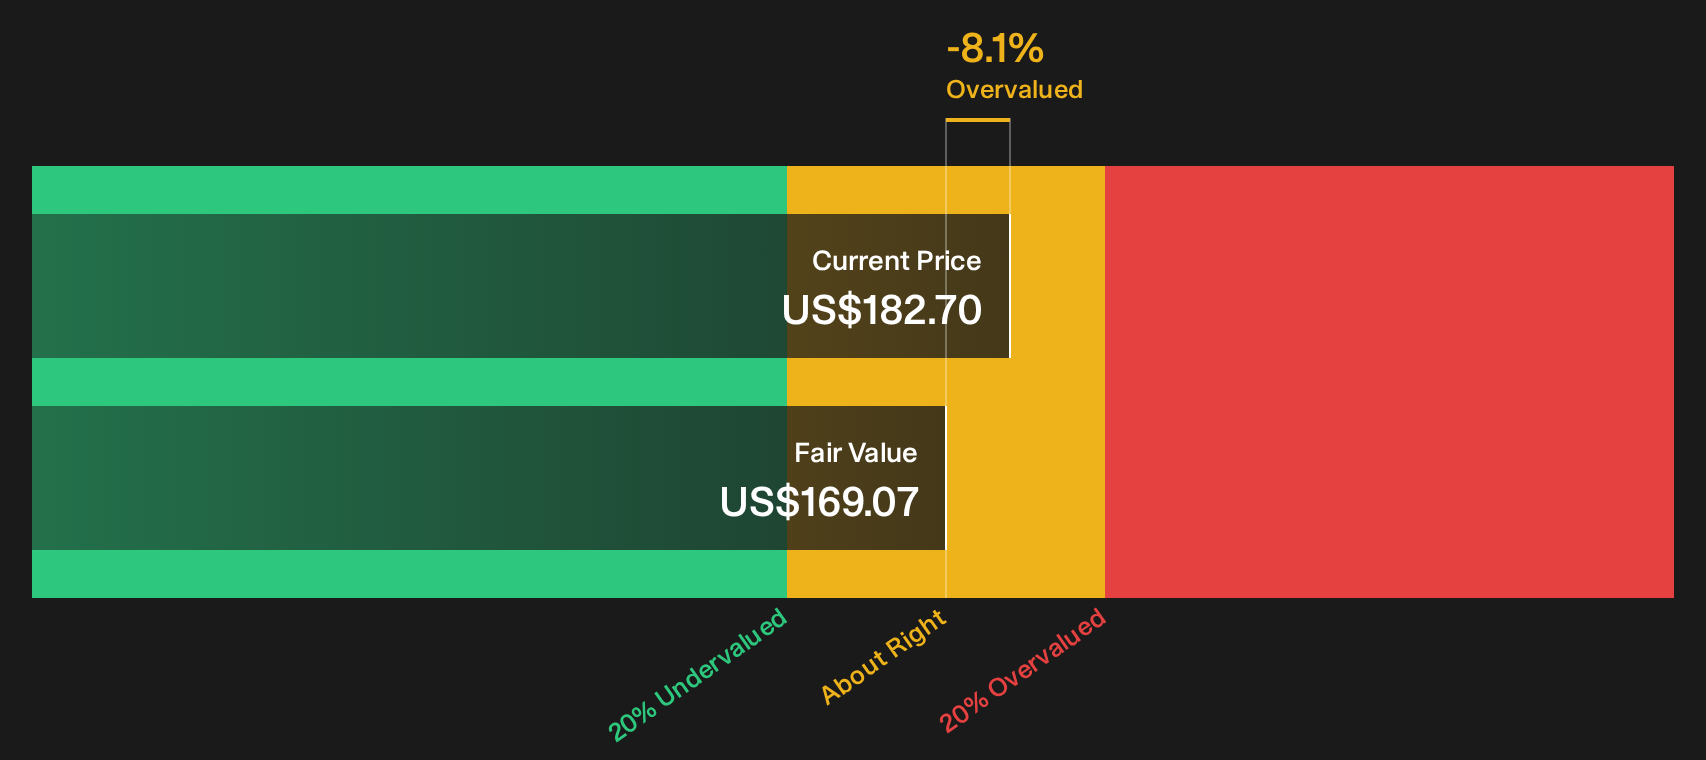
The fair value story shifts when you switch from analyst targets to the SWS DCF model. On that framework, Brinker International at $182.70 trades above an estimated future cash flow value of $169.07, which points to an overvalued signal instead of a discount. Which narrative feels more realistic to you?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Brinker International for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 27 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Curious whether the recent mood around Brinker International matches your own view of the situation? Move quickly through the underlying data, weigh both the concerns and the potential upside, then ground your perspective in the full picture across 5 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Brinker International?
If the Brinker International story has you thinking more broadly about opportunities, do not stop here. Use a few focused tools to pressure test and expand your watchlist.
- Target resilient potential value plays by scanning companies that screen well on cash flows and fundamentals using the 27 high quality undervalued stocks.
- Prioritise financial strength first by reviewing a curated list of solid balance sheet and fundamentals (25 results) that can help you sidestep fragile balance sheets.
- Hunt for under the radar opportunities by browsing a focused pool of 21 high quality undiscovered gems before other investors catch on.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com