


Is CRH (CRH) Still Undervalued Following Its $8.5b Arcosa Deal?
CRH (NYSE:CRH) has closed its US$8.5b purchase of Arcosa, while New Jersey regulators are pushing for divestitures of several asphalt plants to keep regional road building markets competitive.
CRH shares closed at US$84.89 after a 1 day share price decline of 1.78%. This capped a tougher year where the year to date share price return is down 32.86%, even as the 3 year total shareholder return of 69.68% and 5 year total shareholder return of 93.05% point to stronger longer term momentum.
Spot similar infrastructure focused opportunities by scanning our hand picked 42 power grid technology and infrastructure stocks that could also benefit from heavy spending on roads, energy transmission, and critical utility projects.After a sharp pullback despite the Arcosa deal closing, CRH now splits opinions. Has most of the rerating already played out, or do the current numbers still imply meaningful upside ahead based on valuation alone?
Most Popular Narrative: 31% Undervalued
CRH closed at $84.89 while the most widely followed narrative pegs fair value at $122.72. This puts a clear gap between the market price and the modelled outlook that investors need to weigh for themselves.
The ongoing rollout of U.S. federal infrastructure funding, with management expecting around 40% of IIJA highway funds still unspent at the end of 2026 and referencing the proposed BUILD America 250 Act authorizing an additional US$580b for transportation programs, points to a multiyear pipeline of public works that can support CRH revenue, order backlog and earnings.
See why 31 investors see CRH as 31% undervalued.
Result: Fair Value of $122.72 (UNDERVALUED)
Still, CRH relies heavily on public infrastructure funding, and the planned step up in leverage around Arcosa means that any integration stumble could quickly challenge this undervaluation story.
Find out about the key risks to this CRH narrative.
Another View: What CRH’s P/E Is Really Saying
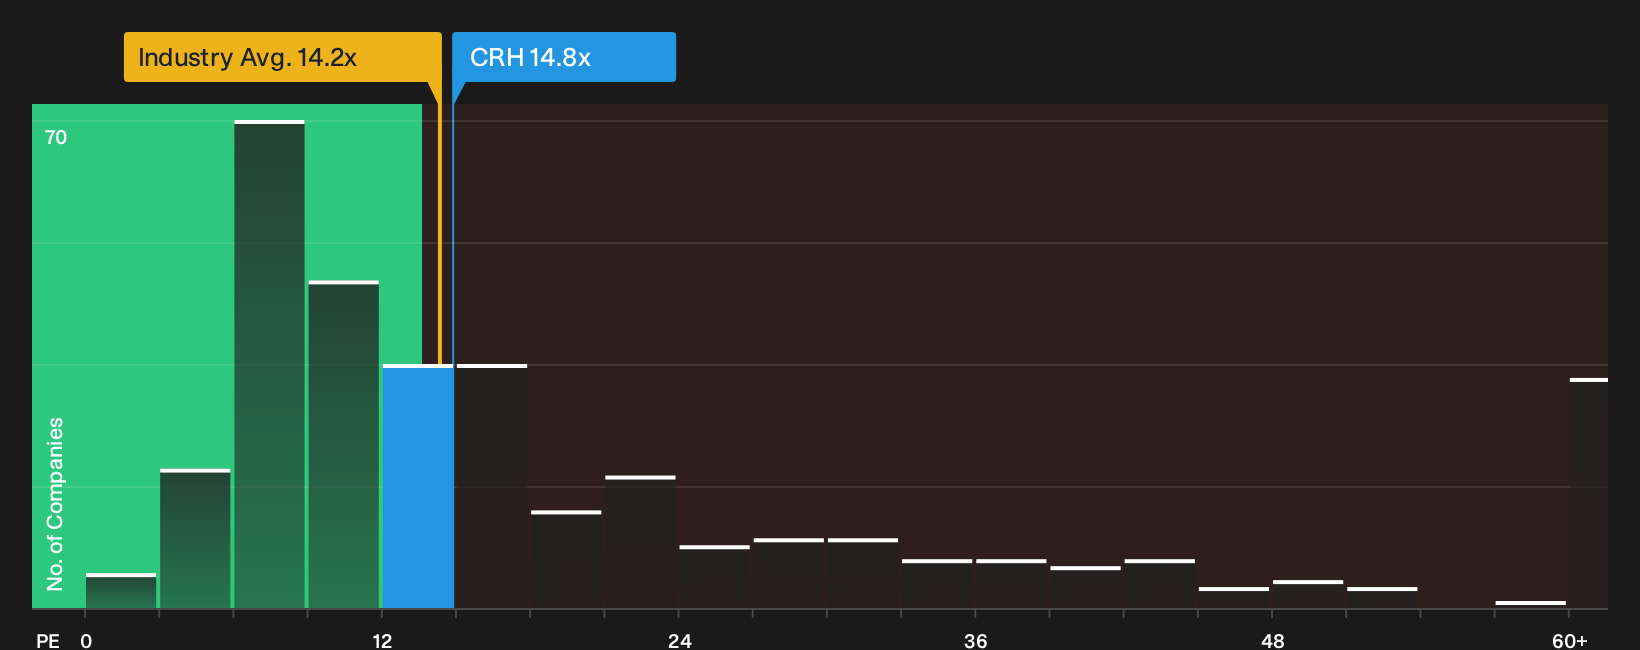
Price based on earnings tells a more mixed story for CRH. The stock trades on a P/E of 14.8x. That is slightly richer than the global Basic Materials sector at 14.2x, yet well below the peer average of 26x and under the fair ratio of 21.2x that the model suggests the market could move toward.
If the share price drifts closer to that fair ratio, the current gap could look like an entry point. If it stays near the industry multiple instead, the premium to the sector might matter more to you than any theoretical upside.
Before leaning on this single earnings yardstick, it helps to see the full breakdown of how that valuation stacks up against sector and peers in practice, not just in theory, in See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals like these rarely stay unresolved for long. Check the data now, pressure test both sides of the CRH story, then review the full picture in 5 key rewards and 1 important warning sign.
Looking for more investment ideas beyond CRH?
If CRH has your attention, do not stop here. Fresh opportunities sit just a few clicks away when you line them up side by side.
- Target potential mispricings by scanning a curated set of strong fundamentals in the 27 high quality undervalued stocks.
- Build a steadier income stream by reviewing companies in the 5 dividend fortresses that pair higher yields with supporting financials.
- Protect your downside first by focusing on resilient balance sheets and cash flow strength in the list of solid balance sheet and fundamentals (25 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com