


What Interparfums (IPAR)'s Flat Q3 Sales Means For Shareholders
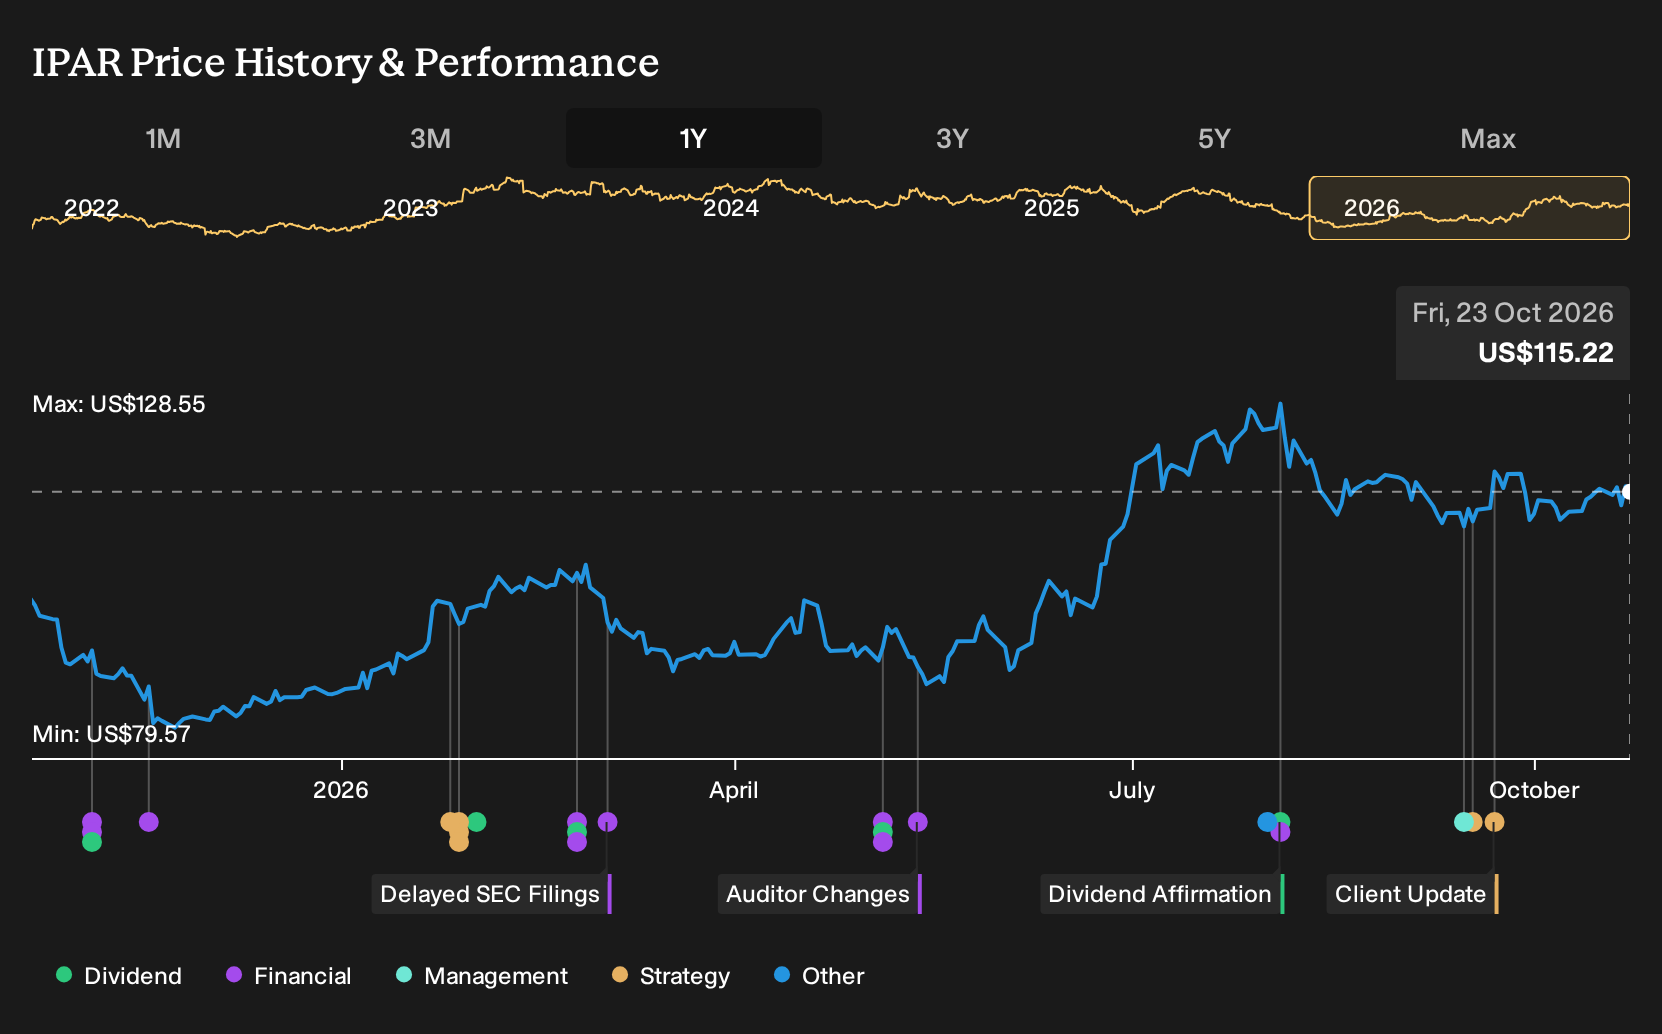
- Interparfums reported Q3 2026 sales of US$430 million, unchanged from a year earlier, with nine month sales at US$1.115b versus US$1.102b, as stronger European fragrance demand offset weaker U.S. activity linked partly to shipment delays.
- The mix shift, with European operations supporting flat quarterly sales despite U.S. softness, highlights how Interparfums’ geographic balance can help absorb logistical and regional pressures on its fragrance portfolio.
- The next step is an assessment of how Interparfums’ steady sales and stronger European performance may influence the existing investment narrative around licensing.
Interparfums Investment Narrative Recap
To own Interparfums, you need to believe in a fragrance portfolio that can handle regional swings and license concentration while still supporting measured growth. The Q3 2026 print, with US$430 million in sales matching last year and year to date revenue at US$1.115b, points to resilience but not much momentum. The near term swing factor is whether US shipment delays clean up without bleeding into shelf space or promotion for key brands.
The biggest risk is that higher SG&A and advertising, already pressuring operating margin from 20.0% to 17.9% in the first half of 2026, do not translate into stronger sell through for lines tied to heavy licensing. Q3 does not materially change that concern. It keeps the spotlight firmly on execution around 2027 launches and on protecting profitability as Interparfums leans into digital channels and international markets.
The most relevant piece of context here is management’s plan to treat 2026 as an off cycle year and instead prepare a concentrated wave of blockbuster launches for 2027 and 2028. Flat Q3 sales make that product cycle even more important. Investors are watching whether today’s spend on advertising, royalties and logistics is really laying the groundwork for that step up in brand activity.
Interparfums already secured long duration licenses such as Puma through 2037 and Roberto Cavalli through 2046. That pushes the focus away from signing new deals and toward making existing agreements count, through e commerce, digital marketing on platforms like Amazon and TikTok, and tighter supply chain execution. Q3’s European strength helps, but it does not remove the core risk that heavy license reliance and war affected regions could still weigh on earnings power if future launches underperform.
Interparfums’ analyst narrative centers on revenues reaching about US$1.8b and earnings of US$184.4 million by 2029, based on projected yearly top line growth of 5.7% and an earnings increase of roughly US$16.6 million from current earnings of US$167.8 million.
Uncover how Interparfums' fair value indicates a 10% potential upside to its current price before the market closes the gap.
Exploring Other Perspectives
Some of the most optimistic analysts frame Q3 differently. You see flat US$430 million sales and wonder about momentum. They focus on potential upside from premium fragrances and Solferino, and were modeling about 8% yearly revenue growth and earnings of roughly US$207.1 million by 2029 before this update. Those views might shift, so explore several angles before deciding what fits your own expectations.
Explore 4 other Interparfums fair value estimates, including one that suggests as much as 98% upside from the current price!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Interparfums research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Interparfums. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Interparfums' overall financial health at a glance.
Looking for more investment ideas beyond Interparfums?
Once you have a view on Interparfums, it can help to set it alongside a few peers with different risk, balance sheet, and income profiles. The Simply Wall St Screener lets you filter by quality, valuation, income potential, and more so you can build a watchlist that matches how you like to invest.
- If you want income to do more of the work, scan for companies with sturdy payout profiles using our 5 dividend fortresses.
- If capital preservation sits high on your priority list, narrow the field to stocks with steadier risk characteristics through the 30 resilient stocks with low risk scores.
- If financial strength matters most for you, start with businesses that pair cleaner balance sheets with solid fundamentals via the list of solid balance sheet and fundamentals (25 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com