


Diamondback Energy (FANG) Shares Moved, What Is Catching Investors' Attention?
Upcoming earnings and oil market shocks put Diamondback in focus
Diamondback Energy (FANG) is drawing attention as investors weigh its November 2 earnings release against a backdrop of rising oil prices linked to attacks on key Saudi infrastructure and shipping routes.
Recent trading suggests interest in Diamondback Energy is picking up again, with a 1-month share price return of 10.83% and a year to date gain of 35.06%. That move sits on top of a 1-year total shareholder return of 44.46% and a 5-year total shareholder return of 137.21%. This helps explain why fresh geopolitical risk and the November earnings event are drawing so much attention to a stock now priced at US$205.75.
Scan for other producers that could react the same way to oil shocks as Diamondback Energy by running the curated 27 high quality undervalued stocks aligned with stronger fundamentals and resilient cash generation.
After that sharp move, Diamondback Energy now trades at US$205.75 while analyst targets and intrinsic estimates point higher. How wide is the gap between today’s quote and a reasonable view of fair value?
Most Popular Narrative: 12.3% Undervalued
On the most followed narrative, Diamondback Energy screens as undervalued, with a fair value estimate of $234.52 against a last close of $205.75. The gap rests on how much of its cost efficiency, debt reduction and gas demand story is already reflected in today’s price.
Ongoing consolidation in the Permian Basin, with Diamondback Energy positioned as a consolidator that has already integrated large acquisitions and realized lower lease operating expense through automation and pump by exception, supports further scale driven synergies that can help sustain EBITDA margins and free cash flow. Consistent operational efficiency improvements, including record low drilling cost per foot in zones like Wolfcamp D and progress toward sub $400 per foot Barnett wells, point to durable cost reductions that can support resilient net margins and free cash flow generation.
See why 78 investors see Diamondback Energy as 12% undervalued.
Result: Fair Value of $234.52 (UNDERVALUED)
Still, large insider share sales and a more neutral analyst stance could pressure Diamondback Energy’s valuation if sentiment cools around its cash flow story.
Find out about the key risks to this Diamondback Energy narrative.
Another View: What Diamondback’s P/E Is Telling You
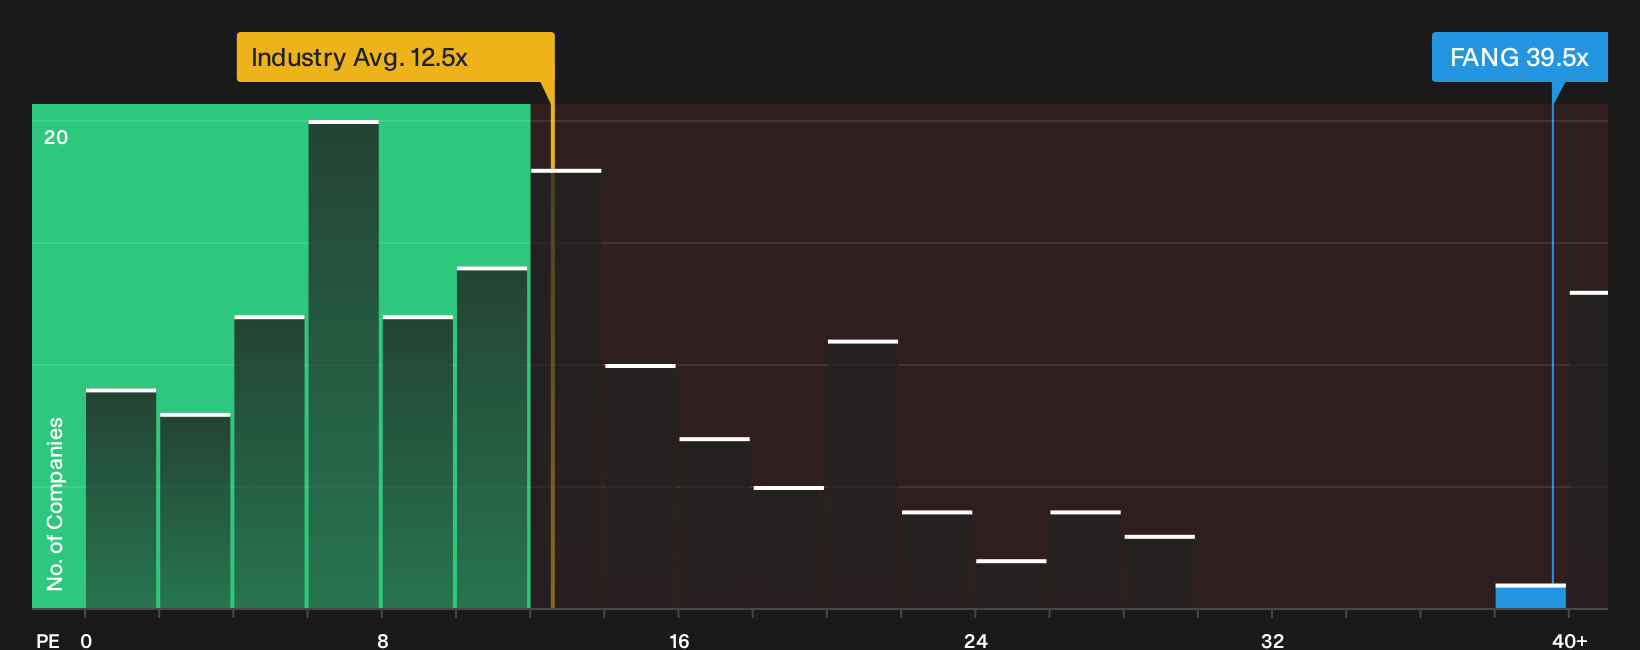
That 12.3% undervaluation story for Diamondback Energy meets a very different signal once you look at the P/E. The shares trade on 39.5x earnings, while the US Oil and Gas group sits near 12.5x and peers around 12.8x. The fair ratio sits at 24x, which suggests meaningful valuation risk if sentiment cools. What if the multiple shifts closer to that fair ratio instead of the narrative fair value?
To see how that rich earnings multiple stacks up against the underlying financials, take a closer look at our valuation breakdown, including how it compares to industry peers, through the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on value can be useful if you treat them as a prompt rather than an answer and move quickly to test your own thesis. To see both sides of the story in one place, review the 2 key rewards and 4 important warning signs.
Looking for more investment ideas beyond Diamondback Energy?
If you stop with Diamondback Energy, you risk missing opportunities where valuation, balance sheet strength and income potential line up more cleanly for your portfolio.
- Target quality at a discount by scanning companies that screen as both financially solid and attractively priced through the 27 high quality undervalued stocks.
- Strengthen portfolio resilience by focusing on businesses with robust finances and dependable fundamentals using the list of solid balance sheet and fundamentals (25 results).
- Turn income into a core pillar of your returns by zeroing in on high yielders screened as 5 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com