


Earnings Growth Could Be A Game Changer For Farmers & Merchants Bancorp Stock
- Farmers & Merchants Bancorp reported third quarter 2026 net interest income of US$58.32 million and net income of US$25.08 million, with both metrics above the prior year period, and posted higher basic and diluted earnings per share from continuing operations.
- For the first nine months of 2026, Farmers & Merchants Bancorp showed higher net interest income and net income than a year earlier, indicating that core lending and spread driven earnings have been an important profit driver across the year so far.
- This article examines how Farmers & Merchants Bancorp's investment narrative is shaped by this higher net interest income performance.
Scan how Farmers & Merchants Bancorp's earnings momentum compares with hand picked regional lenders and community banks in the list of solid balance sheet and fundamentals (25 results).
What Is Farmers & Merchants Bancorp's Investment Narrative?
For an investor to own Farmers & Merchants Bancorp, the belief has to be simple. This is a conservative regional bank that turns disciplined lending and deposit gathering into solid net interest income. The latest quarter fits that pattern. Net interest income of US$58.32 million and net income of US$25.08 million, both above the prior year period, point to execution on spreads and credit costs rather than relying on one off gains or aggressive balance sheet moves.
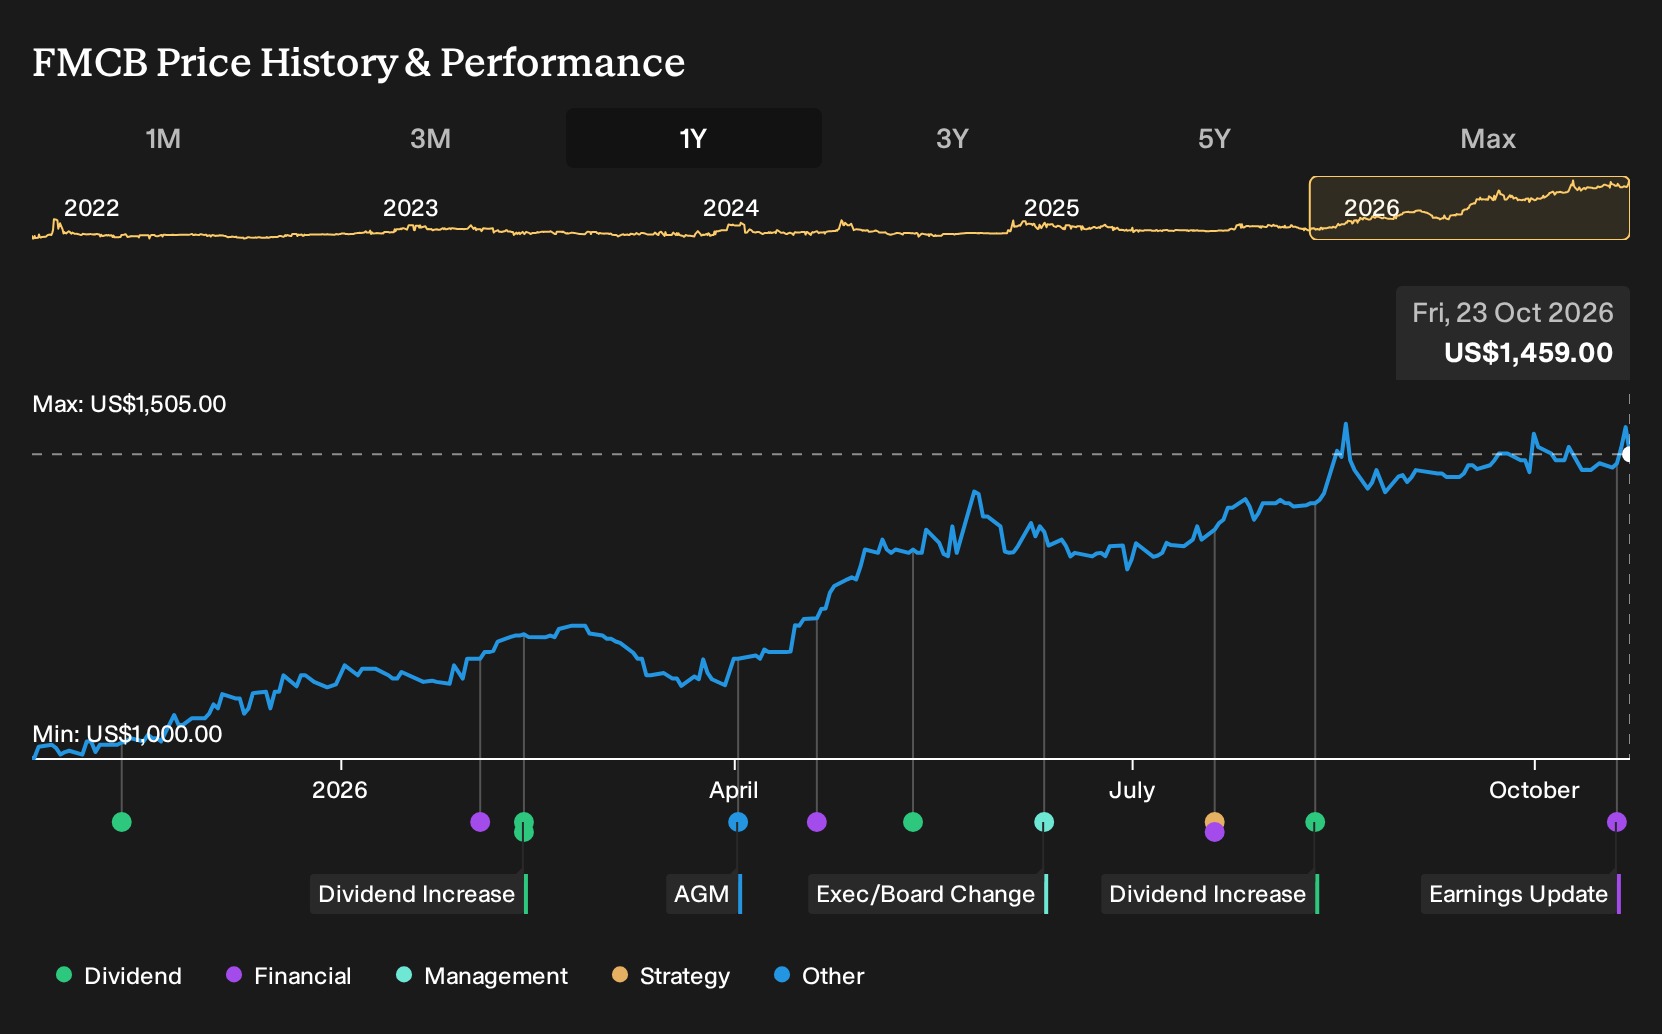
The near term story revolves around whether Farmers & Merchants Bancorp can keep that earnings engine steady as funding costs move and loan demand shifts. Nine month numbers, with higher net interest income of US$172.58 million and net income of US$73.89 million than a year earlier, suggest current operations are supporting that case. Key watchpoints now are how pricing on loans and deposits evolves, how management uses capital given a roughly US$1.0b market value, and whether current profitability, including a 40.1% net margin and 14.7% return on equity, can be sustained without stretching risk.
Even so, there is a less comfortable side to this story once you dig into how that return profile is being earned and what it implies for...
There's only one way to know the right time to buy, sell or hold Farmers & Merchants Bancorp. Head to Simply Wall St's company report for the latest analysis of Farmers & Merchants Bancorp's Fair Value.
Exploring Other Perspectives
The Simply Wall St Community currently has three fair value views on Farmers & Merchants Bancorp, ranging from about US$1,167.75 up to roughly US$2,628,760.68. That spread shows how far apart retail investors can be. These opinions pre date the latest earnings release, so use them as starting points and compare them with your own assessment of the bank's profitability and risk profile.
Explore 2 other Farmers & Merchants Bancorp fair value estimates, including one that suggests as much as 180076% upside from the current price!
Form Your Own Verdict
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so consider your own instincts.
- A great starting point for your Farmers & Merchants Bancorp research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Farmers & Merchants Bancorp. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to evaluate Farmers & Merchants Bancorp's overall financial health at a glance.
Looking For More Ideas Beyond Farmers & Merchants Bancorp?
If you want to round out your watchlist beyond Farmers & Merchants Bancorp, the Simply Wall St Screener can surface other businesses that fit very different priorities, from value driven opportunities to steadier profiles built on income or resilience.
- For investors who care most about paying a fair price for strong fundamentals, start with companies on the 27 high quality undervalued stocks that combine quality with more modest expectations baked into their share prices.
- If dependable income is your focus, scan for companies in the 5 dividend fortresses that pair higher yields with balance sheets built to support regular payouts.
- For those who would rather sleep easier during tougher markets, consider stocks highlighted in the 30 resilient stocks with low risk scores where business quality and risk scores point to more resilient profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com