


Why First Bancorp (FBNC) Could Be 36% Undervalued Following Its Earnings Beat
How First Bancorp’s Latest Earnings Reset the Conversation
First Bancorp (FBNC) just delivered third quarter 2026 results that topped analyst expectations, with higher net interest income, stronger earnings per share, and asset quality metrics aligned with what the market was looking for.
The bank reported net interest income of US$114.8 million for the quarter, alongside net income of US$51.28 million and diluted earnings per share from continuing operations of US$1.24. For holders of First Bancorp stock, those figures now frame the next phase of the investment case.
Momentum around First Bancorp has been building, with a 7 day share price return of 6.76% and a year to date share price gain of 26.58%. The 1 year total shareholder return of 33.52% and 3 year total shareholder return of about 15x suggest earnings and dividend updates are being interpreted as improving the risk reward profile.
Scan other banks showing similar momentum and balance sheet resilience with our curated list of 30 resilient stocks with low risk scores as you weigh First Bancorp’s latest earnings beat.
First Bancorp’s sharp rerating reflects far stronger reported earnings, yet a 33.52% 1 year total return can also be fueled by shifting enthusiasm. How much of today’s US$64.44 share price is business, and how much is mood?
Price-to-Earnings of 16.3x: Is It Justified for First Bancorp?
On valuation terms, First Bancorp is carrying a P/E of 16.3x compared with 11.6x for the wider US Banks industry and 12x for its peer group. That higher multiple sits against a last close of $64.44 and leaves the stock looking expensive relative to many regional lenders on this measure.
The P/E ratio compares what investors pay today with the bank's earnings per share, so it effectively prices in how durable and repeatable current profits might be. For a lender like First Bancorp, which the data flags as having high quality earnings and a 36.1% net margin, a richer P/E often reflects confidence that those profits are clean rather than flattered by one offs.
Context matters here. Earnings grew 66.2% over the past year against a 1.8% annual pace over five years, and profit expansion over the last twelve months also moved ahead of the Banks industry. That kind of acceleration can support a premium tag, although forecasts point to earnings growth of 15.1% a year and revenue growth of 11.9% a year, which are both described as slower than the broader US market and below a "significant" 20% threshold, so the current earnings surge may not be treated as a permanent reset by all investors.
On peer and model comparisons, the market is paying a lot for those results. First Bancorp is described as expensive not only versus the US Banks average P/E of 11.6x, but also versus a peer average of 12x. The estimated fair P/E ratio of 13.2x is meaningfully lower than the present 16.3x, which points to a level some investors may see as a more balanced anchor if sentiment cools and the valuation multiple drifts toward that fair ratio.
Explore the SWS fair ratio for First Bancorp.
Result: Price-to-Earnings of 16.3x (OVERVALUED)
Still, if loan performance weakens or funding costs climb again, the premium P/E that investors currently pay for First Bancorp could lose support quickly.
Find out about the key risks to this First Bancorp narrative.
Another View On First Bancorp’s Value
The P/E discussion paints First Bancorp as expensive, yet the SWS DCF model points in the opposite direction. On that cash flow view, the stock at $64.44 trades about 35.5% below an estimated value of $99.84. Which signal do you trust when the story splits like this?
Look into how the SWS DCF model arrives at its fair value.
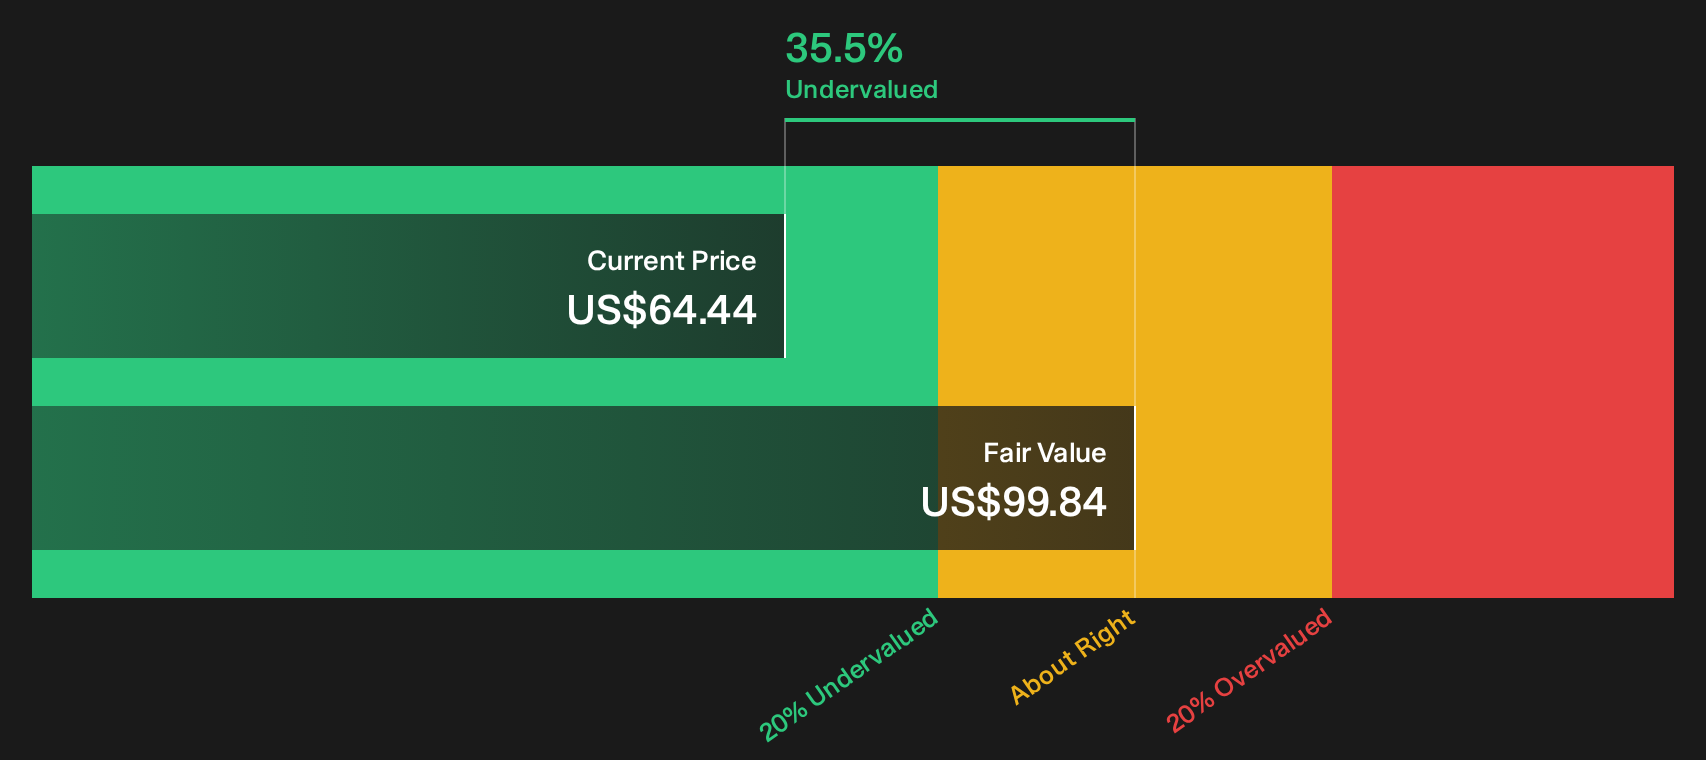
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out First Bancorp for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 27 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on First Bancorp’s valuation story are clear, so move quickly to check the underlying data, weigh both risk and upside, then ground your own view with 4 key rewards and 1 important warning sign.
Looking For More Investment Ideas Beyond First Bancorp?
If First Bancorp has sharpened your view on value and quality, do not stop here. The next step is lining up fresh ideas before the crowd notices.
- Target resilient balance sheets and consistent fundamentals by scanning the list of solid balance sheet and fundamentals (25 results) that meet your quality thresholds.
- Hunt for quality at a discount by reviewing the 27 high quality undervalued stocks that pair stronger fundamentals with more modest pricing.
- Build a cash flow focused watchlist by filtering for the 5 dividend fortresses that could support income focused portfolios.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com