


Borr Drilling (BORR) Benefits From Tight Jack Up Supply, Is The Stock Fully Valued?
Recent commentary around Borr Drilling (NYSE:BORR) has focused on a tight global pool of modern jack up rigs and steady shallow water demand, set against fresh worries over losses, higher costs, and looming refinancing.
At a share price of $4.40, Borr Drilling has moved from a 7.84% 1-day share price gain and a 4.02% 90-day share price return to a much stronger 46.18% 1-year total shareholder return, even though the 3-year total shareholder return declined 24.05% and the 5-year total shareholder return rose 131.22%. This points to momentum building recently as investors weigh tight rig supply against questions around losses, costs, and refinancing risk.
Spot under-pressure offshore drillers like Borr Drilling and compare them with a hand picked list of solid balance sheet and fundamentals (25 results) to see which businesses pair sector momentum with sturdier finances.Borr Drilling has already rewarded those in over the past year, so the real fork in the road now is simple: pay up after the surge, or wait and hope valuation hands you a better entry?
Most Popular Narrative: 8% Undervalued
The most followed valuation narrative pegs Borr Drilling's fair value at $4.76, slightly above the recent $4.40 close. This frames the current debate around whether refinancing costs and fleet growth risks are fully reflected.
The equity raise and improved liquidity position are being interpreted as straightforward enablers of opportunistic M&A and growth. However, this capital could be diverted towards debt service or be required to buffer against interest and refinancing risk due to Borr Drilling's high leverage, ultimately diluting the anticipated earnings leverage effect.
See why 9 investors see Borr Drilling as 8% undervalued.
Result: Fair Value of $4.76 (UNDERVALUED)
Still, that fair value story depends on Borr Drilling overcoming refinancing pressure after its recent debt extinguishment charge, as well as avoiding setbacks from payment delays or political risk in key markets.
Find out about the key risks to this Borr Drilling narrative.
Another View: What Multiples Say About Borr Drilling
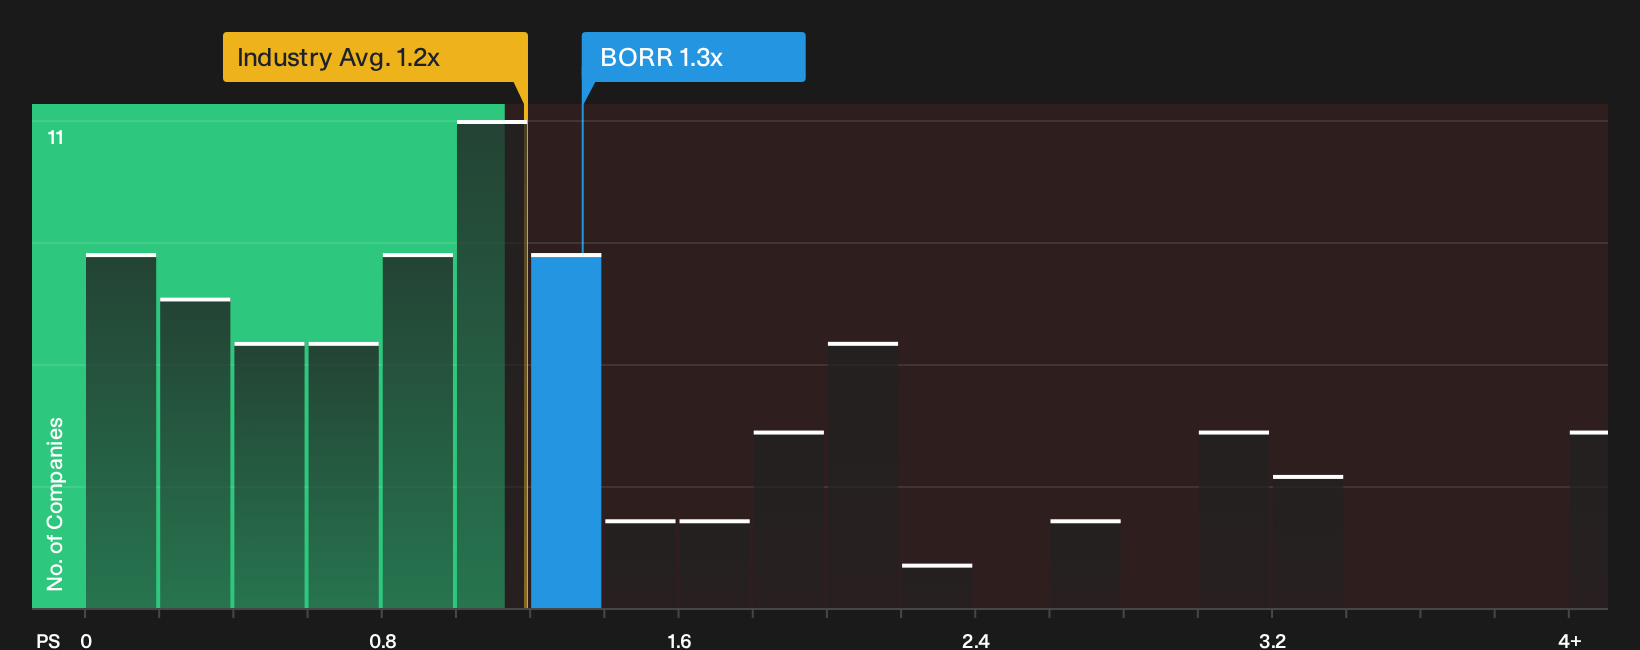
The fair value narrative around Borr Drilling leans on detailed earnings forecasts and discounted cash flows. Yet the P/S ratio tells a cooler story. At 1.3x, the stock trades at a premium to both the US Energy Services sector and peer average, each at 1.1x, which points to less room for error if growth or margins disappoint.
That 1.3x P/S also sits right on the estimated fair ratio of 1.3x, suggesting the market may already be pricing in the current story pretty cleanly. The key question is whether future news flow will justify paying that premium or push investors to rethink the multiple being assigned.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mixed messages around Borr Drilling leave you torn between risk and reward, move fast and pressure test the data yourself. Then weigh those findings against the 2 key rewards.
Looking for more investment ideas beyond Borr Drilling?
You have seen how one offshore driller can split opinion. Now widen the lens and use structured stock lists to pressure test your next decision.
- Target potential mispricings by hunting for quality companies trading below their estimated worth through the 27 high quality undervalued stocks.
- Protect your downside first by filtering for 30 resilient stocks with low risk scores that aim to keep volatility and financial stress in check.
- Look for opportunities by scanning a 21 high quality undiscovered gems before they reach a wider audience.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com