


3 LNG Stocks Investors Are Watching As Alaska Gas Export Risk Reshapes Infrastructure
Global LNG politics just swung through Alaska and the Arctic, pulling a handful of U.S. infrastructure players into the spotlight as sanctions risk, foreign ownership questions, and a fragile $25b export project all collide. That mix can create mispricing, both on the upside and the downside. This article walks through 3 stocks exposed to this news and how this twist in LNG could matter for your portfolio decisions.
The three LNG infrastructure stocks below are a sample set, while the full screen surfaced 15 more listed businesses with similar Alaska and Arctic LNG storylines that are not covered here but may merit a closer look. To go straight to the source and identify your own highest conviction angles, analyze the Alaska and Arctic-Exposed LNG Infrastructure & Services screener.
NPK International (NPKI)
NPK International gives you a way to play the Alaska and Arctic LNG build out indirectly, supplying the rugged composite matting that keeps remote transmission, pipeline, and terminal worksites accessible when conditions are harsh and logistics are complicated.
NPK International focuses on Industrial Solutions, with recyclable composite matting generating about $300.7 million of segment revenue, and holds a market value near $914 million, positioning the business as a mid cap specialist in temporary access infrastructure for energy and construction projects.
"Industry adoption of advanced, longer-life composite mats (versus traditional timber) for access solutions is accelerating, with NPK's product innovation and strong customer relationships with utilities and fleet operators driving a secular transition to higher-margin, value-added products, which is enhancing overall net margins."
The real swing factor sits in how far large, remote infrastructure projects lean into longer rental terms and repeat matting deployments over the next few years.
Those long rentals and repeat deployments are exactly what the full narrative for NPK International unpacks, highlighting where recurring access work could quietly compound returns.

MasTec (MTZ)
MasTec brings LNG theme exposure through its engineering and construction work on energy and pipeline assets across North America. Its primary story centers on how that broad infrastructure mix converts into longer duration earnings tied to power, gas and utility customers.
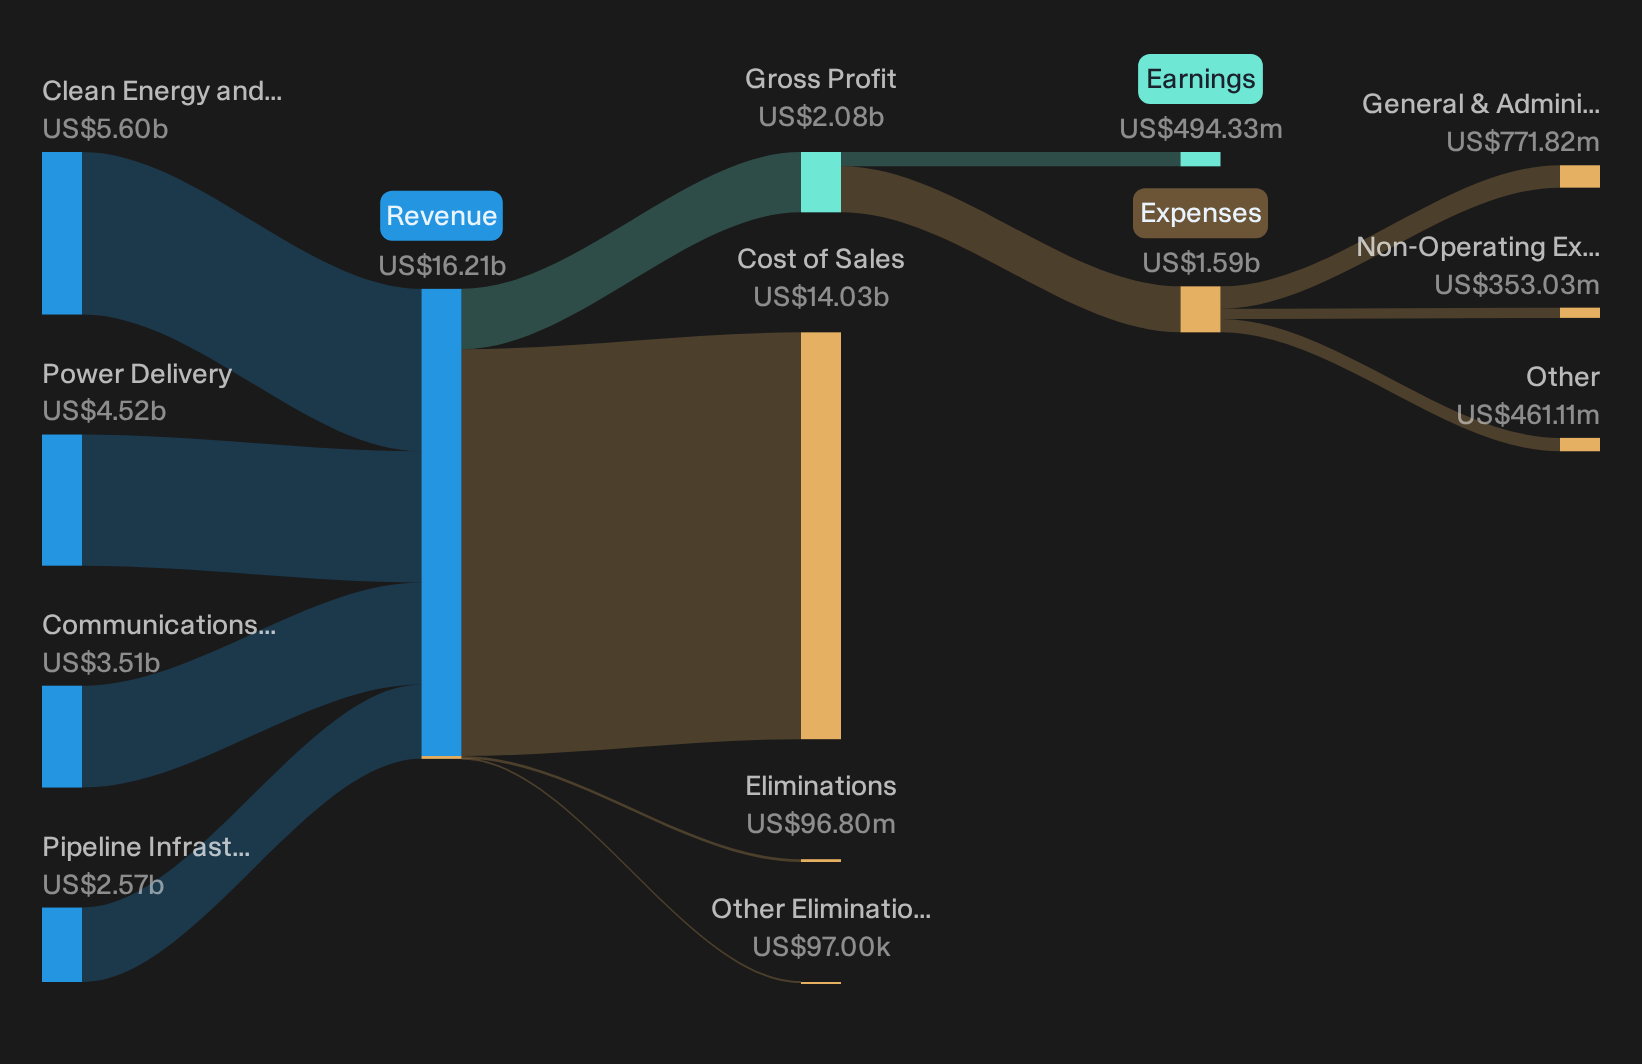
MasTec, a US and Canada focused infrastructure contractor, earns most of its roughly US$16.1b revenue from Clean Energy and Infrastructure at about US$5.6b, Power Delivery at about US$4.5b and Pipeline Infrastructure at about US$2.6b, and carries a market value near US$13.6b.
"Ongoing grid modernization and electrification, reflected in MasTec’s Power Delivery segment backlog of about US$6.3b and 2026 revenue outlook of roughly US$5.725b with low double digit EBITDA margins, increases the portion of earnings tied to longer duration utility spending rather than shorter cycle work."
What really moves the needle for MasTec from here is how one quiet shift in its project mix ultimately flows through to margins and cash.
That mix shift is exactly what the full narrative for MasTec unpacks. It shows how MasTec’s backlog, capital intensity, and LNG work could be quietly decoupling cash generation from headline revenue volatility.
Quanta Services (PWR)
Quanta Services gives you LNG-adjacent exposure through the less glamorous but critical work of building and maintaining the wires and pipes that keep gas utilities, pipelines, and large energy projects running. This includes the kind of grid and midstream upgrades Alaska and Arctic LNG projects depend on.
Quanta Services runs a large infrastructure platform that delivers about US$26.9b of sales from Electric Infrastructure and roughly US$6.0b from Underground Utility and Infrastructure Solutions, and the stock carries a market value near US$83.1b.
Investors watching the Alaska and Arctic LNG story now have to factor in how a contractor like Quanta might absorb any ripple effects from a delayed or reshaped export buildout, especially if capital spending reorders where and how new pipes and power lines get built.
"The first driver is utility and transmission capex. Grid hardening, reliability spending, renewable integration, and long-distance transmission all require exactly the types of services Quanta provides."
What really matters from here is how one quiet shift in the mix of large, long-duration projects ultimately feeds through to margins and cash generation.
That mix shift could be exactly where full narrative for Quanta Services shows how Quanta Services turns grid capex and LNG adjacency into accelerating, less cyclical earnings power.

Seeking Alternatives Before The Crowd
Fresh ideas move first. By the time every headline catches a breakout, early momentum can be gone or prices already flying. Scan under-the-radar setups while it matters and act now.
- Spot underpriced quality before momentum funds wake up by running the 27 high quality undervalued stocks and filtering for businesses where balance sheets and cash flows already do the heavy lifting.
- Track where real earnings fuel AI momentum, not hype, with the 39 profitable AI stocks that aren't just burning cash and focus on companies already funding growth from their own operations.
- Target businesses with resilient compounding potential in choppy markets through the 30 resilient stocks with low risk scores and identify companies designed to handle shocks without panicked dilution.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com