


Is Covista (CVSA) Still Below Fair Value Following Buybacks And Its New Utah Campus?
Covista (CVSA) is back in focus as management keeps shrinking the diluted share count through ongoing buybacks, while also investing in growth with a new Chamberlain University nursing campus in Utah.
Recent trading reflects this mix of capital returns and reinvestment. Covista’s share price has climbed 7.0% over the past month and 26.2% year to date, yet the 1 year total shareholder return has declined 13.8%. By contrast, the 3 and 5 year total shareholder returns of 163.8% and 257.0% point to stronger longer term momentum that recent buybacks and the new Utah campus are now trying to refresh.
Capitalize on Covista’s mix of buybacks and education growth by screening for other education and training providers showing similar momentum using our curated 21 high quality undiscovered gems.After a 26.2% gain year to date but a 13.8% decline over the past year, Covista now sits at a crossroads. Do current valuation markers still leave enough potential upside for new buyers to be comfortable with the risk?
Most Popular Narrative: 17% Undervalued
At a last close of $131.82 against a widely followed fair value estimate of $159.50, the current Covista price sits well below that narrative anchor while buybacks and new campuses try to pull the story higher.
Persistent health care workforce shortages in nursing, medicine and behavioral health create a structural need for large scale training capacity, which can support sustained demand for Covista's programs and underpin revenue growth.
Rising acceptance of flexible digital learning for working adults, reflected in Walden's record 52,400 students and ongoing program launches in areas like applied behavioral analysis and clinical psychology, can expand addressable markets and support earnings through scale efficiencies.
See why 5 investors see Covista as 17% undervalued.
Result: Fair Value of $159.50 (UNDERVALUED)
Still, the bullish Covista narrative leans heavily on tight healthcare labor markets and continued appetite for online learning, both of which could soften and weaken the thesis.
Find out about the key risks to this Covista narrative.
Another View: What Multiples Say About Covista
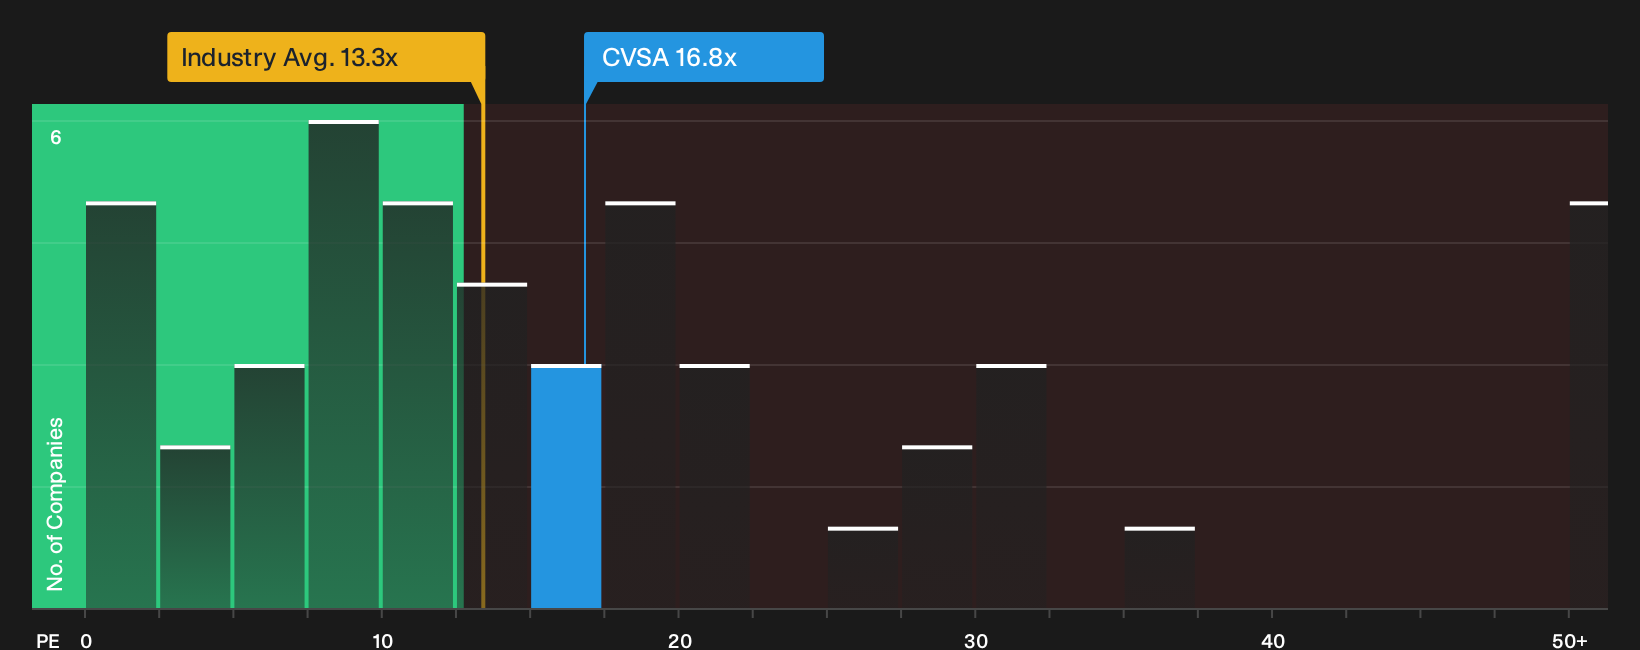
On simple earnings multiples, Covista looks less clear cut. The stock trades on a P/E of 16.8x, above both the US Consumer Services group at 13.3x and a peer average of 16.3x, even though the fair ratio estimate sits higher at 19.5x.
The market price therefore appears richer than sector and peer benchmarks, yet still below the fair ratio that models suggest it could move toward. This leaves you weighing whether that gap represents valuation risk or a potential opportunity if sentiment shifts.
To stress test this earnings multiple view against detailed valuation work, review the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Covista is mixed, which is exactly when fresh data can help you move faster than consensus and form an independent view. To see what investors are currently optimistic about, take a closer look at the 4 key rewards.
Looking for more investment ideas beyond Covista?
You have seen how Covista blends buybacks with education growth. Do not stop there when a wider set of opportunities could suit your goals even better.
- Zero in on potential mispricings by scanning a focused group of companies that screen as both higher quality and attractively valued using our 27 high quality undervalued stocks.
- Strengthen your defensive side by reviewing a list of solid balance sheet and fundamentals (25 results) that can help you spot businesses built to handle tougher conditions.
- Target consistent cash payouts by reviewing a hand picked group of higher yield payers through the 5 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com