


Dividend Raise Might Change The Case For Investing In Ventas (VTR)
- Ventas, Inc. recently set its quarterly dividend at $0.52 per share, implying a 2.44% yield and an annualized payout that is 8.3% above the prior year.
- The richer dividend, alongside projections for an 11.78% increase in fiscal 2026 earnings, outlines how Ventas may be focusing on income growth to support its senior housing and healthcare real estate platform.
- We will now look at how Ventas' higher annualized dividend relates to its existing investment narrative around senior housing growth.
Scan beyond Ventas’ higher payout to find other income-focused real estate and infrastructure plays in our hand picked list of 5 dividend fortresses.
Ventas Investment Narrative Recap
To own Ventas, you need to believe its senior housing and healthcare real estate platform can keep turning demographic demand into steady occupancy, pricing power and net operating income, even as new construction stays relatively muted. The key near term swing factor is how well its senior housing operating portfolio holds occupancy around recent levels while maintaining resident fee momentum.
The richer US$0.52 quarterly dividend and higher annualized payout do not fundamentally change that thesis. They mainly signal confidence in cash generation in a backdrop where interest coverage, equity funded growth and competition for acquisitions remain important risks if returns on new senior housing investments soften.
The most relevant recent development is the decision to lift the annualized dividend by 8.3% while earnings for fiscal 2026 are projected to be 11.78% higher. That keeps Ventas aligned with an income oriented audience that also cares about the underlying health of the real estate platform, particularly the large senior housing footprint.
This higher payout interacts directly with existing catalysts. Ventas has deployed more than US$8b into senior housing since early 2024, funded partly by about US$4.2b of equity, and is targeting mid 6% initial yields on acquisitions at discounts to replacement cost. The ability of those properties to support the new dividend level while covering interest costs is central to the execution story.
What The New Dividend Asks You To Believe About Ventas
Ventas' narrative projects US$8.9b in revenue and US$677.2m in earnings by 2029. That rests on analysts penciling in 11.6% yearly revenue growth and an earnings increase of about US$414.5m from current earnings of US$262.7m.
Uncover why Ventas' fair value indicates a 17% potential upside to its current price, which could narrow quickly.
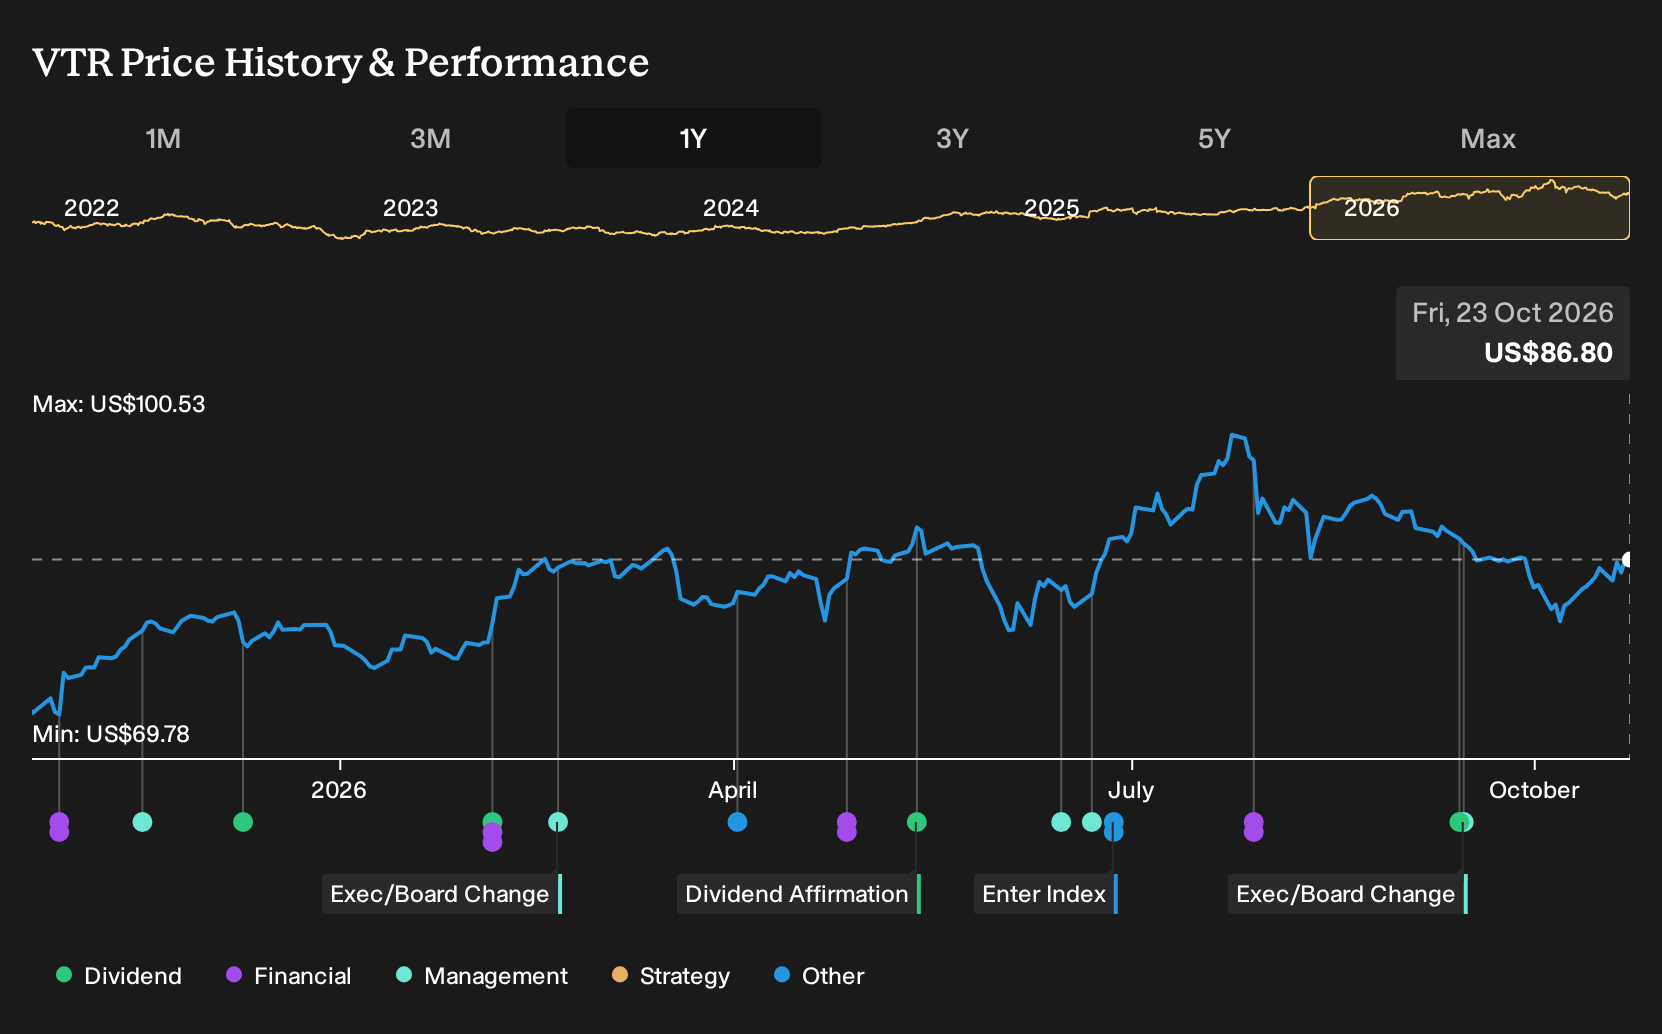
Exploring Other Perspectives
Only two fair value estimates from the Simply Wall St Community cluster tightly between about US$101.9 and US$118 per share, yet they still show how far opinions on Ventas can stretch. Those views sit beside risks around equity funded senior housing deals and occupancy trends, which could sway how you judge the whole story.
Explore another Ventas fair value estimate, including one that suggests as much as 36% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your Ventas research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Ventas. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Ventas' overall financial health at a glance.
Looking For More Ideas Beyond Ventas?
Once you have a handle on Ventas, it can help to compare its profile with other companies that match your income or risk preferences. The Simply Wall St Screener lets you scan the market using fundamentals rather than headlines, so you can quickly narrow the field to a shortlist that actually fits your criteria.
- If you want potential income with fewer balance sheet surprises, start with companies screened for resilient finances and dependable metrics through our list of solid balance sheet and fundamentals (25 results).
- For readers hunting for quality at a measured price, filter the market by valuation and fundamentals using the 27 high quality undervalued stocks to see which businesses match your checklist.
- Those looking for stability before return potential can zero in on stocks with steadier risk profiles through a 30 resilient stocks with low risk scores that places resilience front and centre.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com