


TCL Electronics Holdings (SEHK:1070) Shares Just Climbed, So What Is Behind The Move?
TCL Electronics Holdings (SEHK:1070) has updated investors with fresh earnings guidance for the first three quarters of 2026, indicating double digit year-on-year gains in both revenue and adjusted profit.
TCL Electronics Holdings' latest guidance lands after a strong price run, with the share price at HK$16.35 and a year to date share price return of 56.16%. The very large 3 year total shareholder return of more than 7x and 5 year total shareholder return of 360.73% point to investors steadily reassessing both growth prospects and risk around the business, as earnings guidance and new product launches, such as the 5G AI CPE X5 showcased in October 2026, keep the story in focus.
Scan 39 profitable AI stocks that aren't just burning cash that echo TCL Electronics Holdings' push into AI powered devices and could benefit as intelligent hardware gains more attention with investors.
Bulls point to TCL Electronics Holdings' rapid share rerating and upbeat 2026 guidance, while bears worry the price already bakes that in. The valuation work now needs to show which side the numbers support.
Preferred price-to-earnings of 14.1x: Is it justified for TCL Electronics Holdings?
TCL Electronics Holdings trades on a P/E of 14.1x, which leaves the stock looking expensive against the Hong Kong Consumer Durables sector but cheaper than its peer group average, even after the strong share price move to HK$16.35.
The P/E multiple compares the current share price with earnings per share and gives a quick read on how much investors are willing to pay for current profitability. For a consumer electronics group with multiple segments, from TVs to photovoltaic equipment and smart devices, it frames how the market weighs established earnings against the risks of capital intensive hardware and new business lines.
Relative to the wider Consumer Durables industry P/E of 9.2x, TCL Electronics Holdings trades at a clear premium. This suggests the market is placing a higher value on its earnings profile than the typical local peer. Against the estimated fair P/E of 11.7x though, the current 14.1x looks stretched and points to a level investors could reassess if sentiment cools or if profit delivery does not keep pace with expectations.
Explore the SWS fair ratio for TCL Electronics Holdings.
Result: Price-to-earnings of 14.1x (OVERVALUED)
Still, TCL Electronics Holdings faces clear risk if AI hardware demand cools or if capital heavy photovoltaic projects deliver slower payback than investors currently assume.
Find out about the key risks to this TCL Electronics Holdings narrative.
Another view using the SWS DCF model
TCL Electronics Holdings looks expensive on a 14.1x P/E, yet the SWS DCF model points in the opposite direction. On that cash flow view, the estimated value sits at HK$61.22 per share versus the current HK$16.35, which implies the stock trades at a steep discount. This raises the question of which signal investors should prioritize when the market and the model disagree so clearly.
Look into how the SWS DCF model arrives at its fair value.
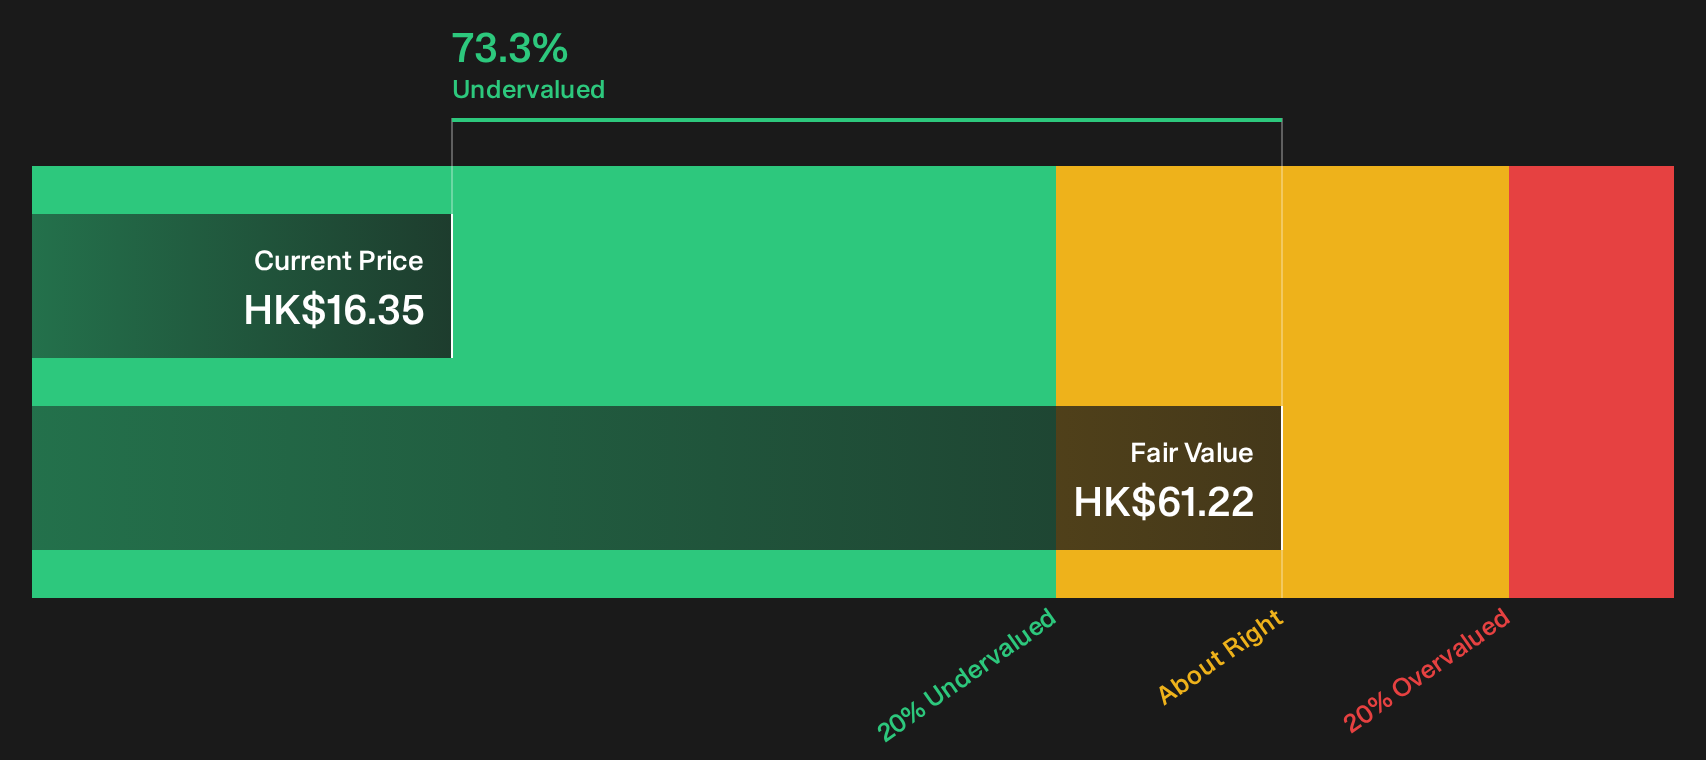
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out TCL Electronics Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 192 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
With sentiment clearly split in this TCL Electronics Holdings story, it helps to move fast and look at the underlying numbers yourself before opinions harden. To see why some investors are optimistic about its potential rewards, take a closer look at the 4 key rewards.
Looking for more investment ideas beyond TCL Electronics Holdings?
If you only stop with TCL Electronics Holdings, you could miss other compelling setups. Use the Simply Wall St screener to quickly spot ideas that fit your style.
- Target stronger potential value by scanning a 192 high quality undervalued stocks that match your preference for pricing support and balance sheet quality.
- Protect your downside focus by reviewing a 221 resilient stocks with low risk scores that may suit a more cautious approach to capital preservation.
- Hunt for tomorrow's potential standouts by checking a 615 high quality undiscovered gems before the wider market pays closer attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com