


Delek Logistics Partners (DKL) Distribution Declaration Keeps Fair Value Debate Alive
Delek Logistics Partners (DKL) has put income front and center with a new quarterly cash distribution of $1.14 per common limited partner unit, tied to the third quarter of 2026. That payout annualizes to $4.56 per unit.
Against this income backdrop, Delek Logistics Partners units trade at $57.32, with a 30-day share price return of 4.28% and a year-to-date share price gain of 21.96%, while the 1-year total shareholder return of 37.95% reflects momentum supported by distributions.
Scan income-focused opportunities with similar momentum to Delek Logistics Partners by reviewing our hand picked list of 5 dividend fortresses.
Delek Logistics Partners just pushed to $57.32 while analyst targets cluster lower and intrinsic estimates sit far higher. Where does fair value really land in that spread, and what does the recent move price in already?
Most Popular Narrative: 7.8% Overvalued
Against the narrative fair value of $53.17 per unit, the current Delek Logistics Partners price of $57.32 implies investors are paying a premium and already baking in a meaningful part of the expected buildout story.
The view that Delek Logistics Partners is fairly valued and bullish indicates that the current unit price already reflects expectations for sustained third party EBITDA mix, ongoing distribution growth and the earnings contribution from the 2026 growth capital program.
The shift in EBITDA mix toward third party customers, with management reiterating an outlook of roughly 80% of 2026 run rate EBITDA from non sponsor counterparties, can diversify revenue, influence the partnership's risk profile and support a more independent earnings and cash flow base.
See why 4 investors see Delek Logistics Partners as 8% overvalued.
Result: Fair Value of $53.17 (OVERVALUED)
Still, if Delek Logistics Partners continues to miss earnings expectations or keeps leverage elevated near 4x, that positive third-party mix story could quickly lose credibility.
Find out about the key risks to this Delek Logistics Partners narrative.
Another View: Delek Logistics Partners Through A Cash Flow Lens
The first take paints Delek Logistics Partners as overvalued on a narrative fair value of $53.17, yet the SWS DCF model points the other way. On that approach, DKL units trade at $57.32 against a future cash flow value estimate of $211.57, which screens as heavily undervalued. Which signal do you trust more when the gap is this wide?
Look into how the SWS DCF model arrives at its fair value.
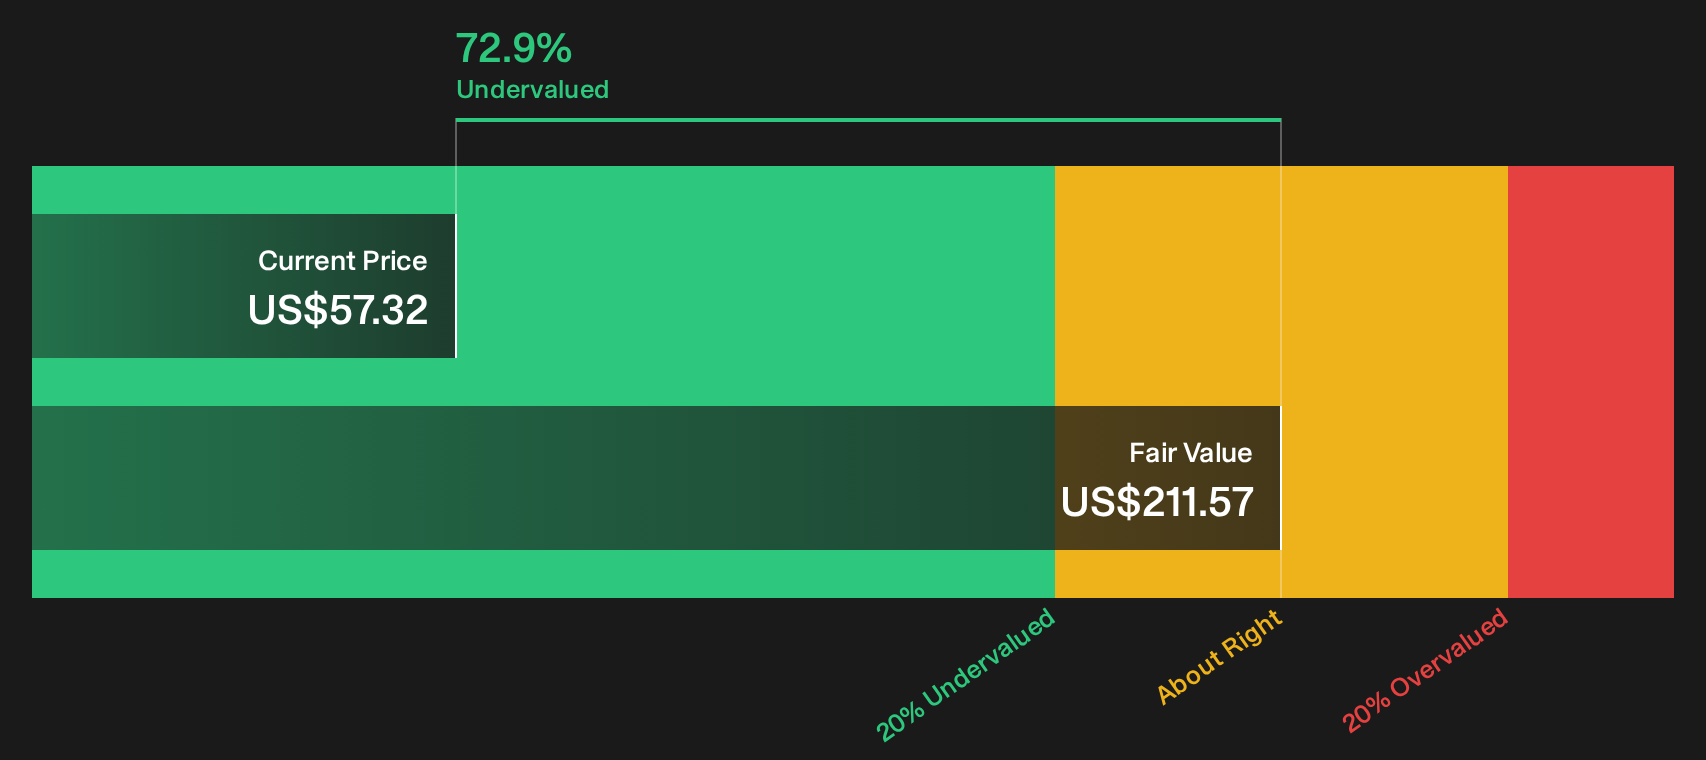
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Delek Logistics Partners for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 27 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this split narrative around Delek Logistics Partners leaves you uncertain, move quickly to check the underlying data and pressure test your own thesis. Start by weighing the 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Delek Logistics Partners?
Do not stop with one opportunity. Use this moment to line up a few more candidates so your watchlist works harder for you over the next cycle.
- Target reliable income streams by reviewing a curated group of high-yield payers through the 5 dividend fortresses.
- Hunt for mispriced opportunities where quality and valuation intersect using the 27 high quality undervalued stocks.
- Prioritize durability and financial resilience by focusing on companies in the list of solid balance sheet and fundamentals (25 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com