


Orezone Gold (TSX:ORE) Just Gave Investors Something To Think About
Orezone Gold (TSX:ORE) has put fresh operating data on the table, reporting consolidated gold output of 59,674 ounces for the third quarter of 2026 and 157,029 ounces for the first nine months.
Orezone Gold’s latest production update lands after a choppy stretch in the market, with the share price at CA$2.70 and the 30 day share price return down 16.4%. The 90 day share price return is up 19.5% and the 1 year total shareholder return is 86.2%, pointing to strong longer term momentum despite recent weakness.
Scan how Orezone Gold stacks up against other producers by checking a curated set of 35 elite gold producer stocks with similar production and price momentum.
Orezone Gold now trades at a steep discount to both its intrinsic estimate and analyst targets after that recent pullback. Is the market being prudently cautious about Burkina Faso risk, or is it marking the stock down too far on sentiment alone?
Most Popular Narrative: 75% Undervalued
Against the current price of CA$2.70, the most followed narrative on Orezone Gold places fair value at CA$10.68. This represents a large gap for a producer already reporting solid output. That framing leans heavily on the idea that Bomboré and Casa Berardi together could support a mid-tier profile if execution keeps tracking to plan.
The bull case is simple: Orezone is already producing, already generating cash flow, has completed the Stage 1 hard rock expansion at Bomboré, and now owns a second mine in Quebec. Bomboré production is guided at 160,000 to 180,000 ounces in 2026. Casa Berardi produced 91,160 ounces in 2025 before Orezone acquired it. If Bomboré ramps properly and Casa Berardi is optimized, Orezone could become a meaningful mid-tier gold producer.
See why 19 investors see Orezone Gold as 75% undervalued.
Result: Fair Value of CA$10.68 (UNDERVALUED)
Still, Orezone Gold carries clear pressure points, from Burkina Faso jurisdiction risk to high AISC levels that could quickly squeeze margins if conditions turn.
Find out about the key risks to this Orezone Gold narrative.
Another View: Orezone Gold Through The Earnings Lens
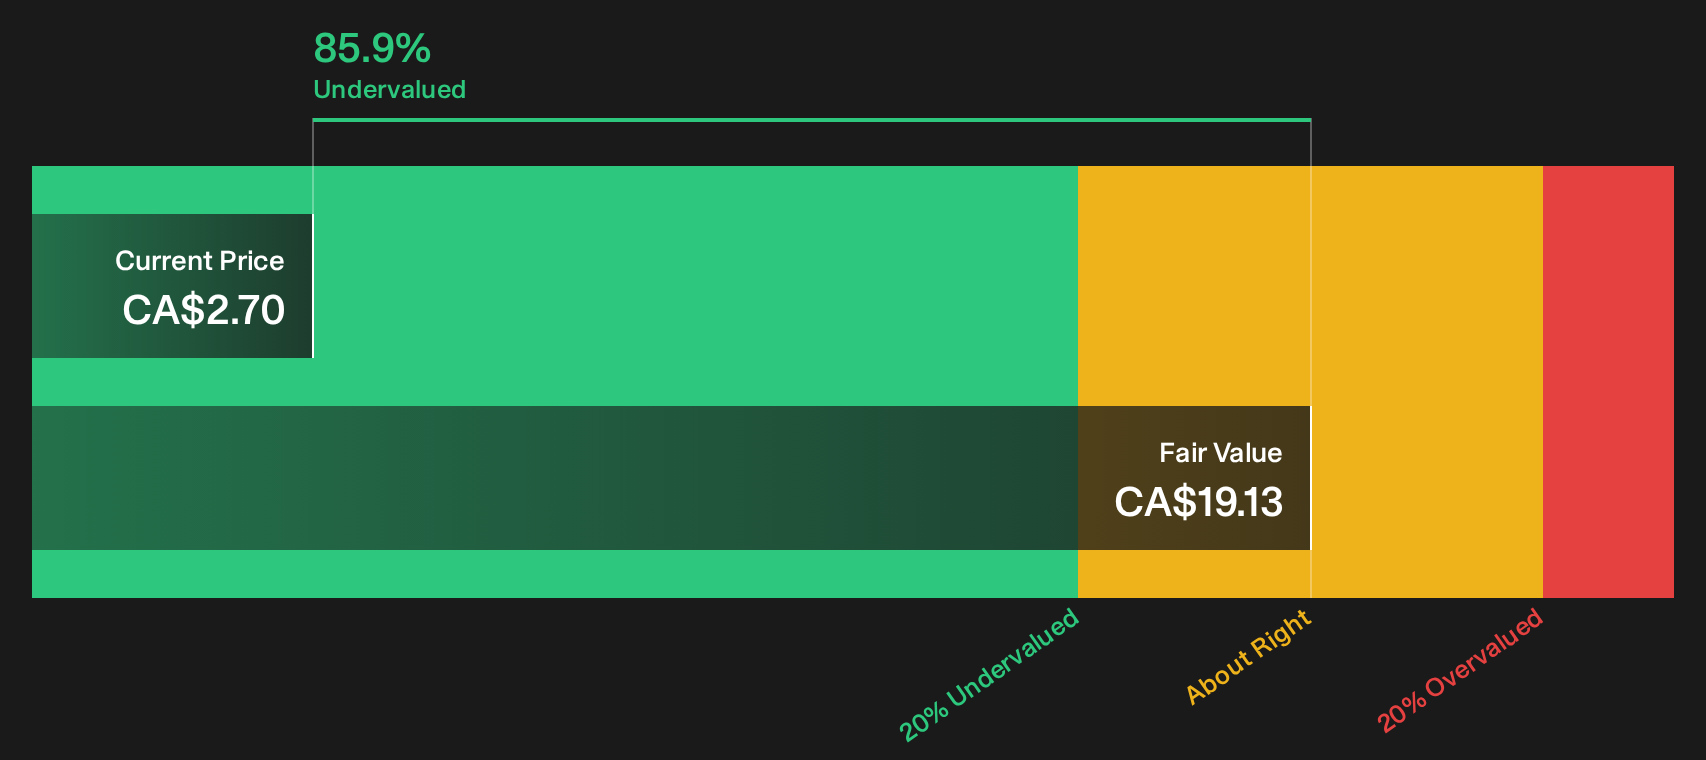
The SWS DCF model points to a fair value of CA$19.13 per share, which is far above the current CA$2.70 price and flags Orezone Gold as deeply undervalued on a future cash flow basis. That kind of gap raises a simple question: Are the cash flow assumptions too rich, or is the market being too cautious?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed messages on Orezone Gold so far, with strong production, a wide valuation gap and clear country and cost risks all pulling in different directions. If you want to move fast and reach your own verdict based on the underlying data rather than the headline story, focus on the balance of 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Orezone Gold?
You have seen how one producer’s story can hinge on a few key variables. Now widen the lens and let data guide your next shortlist.
- Target higher quality return potential by scanning for strong fundamentals and attractive pricing using a curated set of 2 high quality undervalued stocks.
- Prioritise resilience under pressure by filtering for companies with robust finances through the list of solid balance sheet and fundamentals (7 results).
- Hunt for tomorrow’s potential standouts early by reviewing a focused group of 9 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com