


How Rising Interest Costs Will Impact Lithia Motors Stock (LAD) Investors
- Lithia Motors reported Q3 2026 revenue of US$9,946.7m and net income of US$291.1m, raised its quarterly dividend to US$0.75 per share, and confirmed Bryan B. DeBoer as both CEO and Chairman, with Sidney B. DeBoer moving to Vice Chairman.
- Stronger earnings from Driveway Finance Corporation and a larger store base now sit beside higher interest costs, increased leverage and softer same store metrics, putting Lithia Motors’ cost discipline and financing model under closer scrutiny.
- We will assess how Lithia Motors’ investment narrative evolves as higher interest costs and leverage interact with its finance led earnings mix.
Scan how Lithia Motors’ mix of auto retail, financing and higher leverage compares with peers by reviewing our curated list of 27 high quality undervalued stocks.
Lithia Motors Investment Narrative Recap
To own Lithia Motors, you need to be comfortable with a story built around scale, acquisitions and a growing finance arm, all while cost control catches up. In the short term, the key question is whether SG&A efficiency, the Pinewood.AI rollout and aftersales strength can offset softer same store trends and higher interest expense that investors are already watching closely.
The biggest risk right now sits in that mix of leverage and organic softness. Interest payments are not well covered by earnings, so rising financing costs and any slowdown in acquired dealership opportunities would make it harder to grow profitably while same store revenue and gross profit trends remain under pressure.
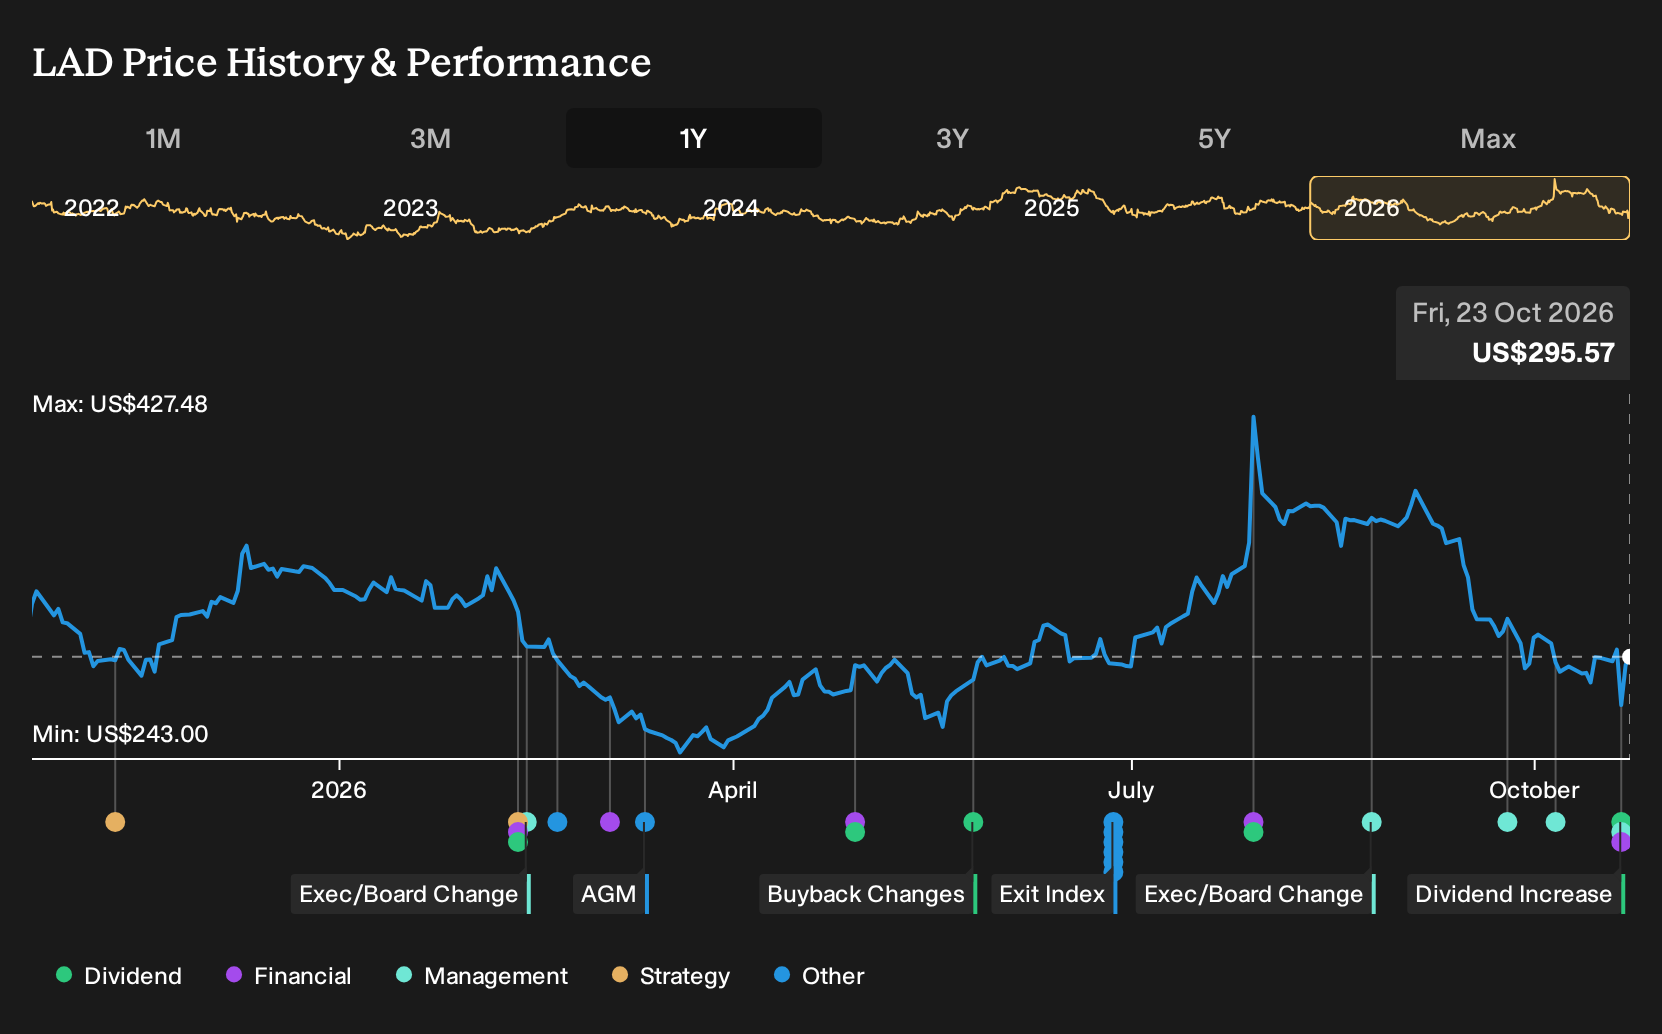
The Q3 2026 earnings release is the clearest reference point. Lithia Motors reported US$9,946.7m of quarterly revenue, US$291.1m of net income and US$13.22 in diluted EPS from continuing operations, supported by stronger Driveway Finance Corporation results. Yet the share price still dropped about 10%, suggesting that the market is focused on balance sheet risk and operating efficiency.
That reaction matters for potential catalysts. Investors are weighing record finance income, aftersales contribution and the new Memphis stores against concerns over leverage, interest coverage and declining same store metrics. Execution on SG&A reduction, disciplined acquisitions and measured growth in the finance book is likely to determine how the next stage of this story is viewed.
Lithia Motors' current narrative points to US$43.3b of revenue and US$1.1b of earnings by 2029, based on analysts’ assumption of 4.5% yearly revenue growth and an earnings increase of about US$385.6m from current earnings of US$714.4m.
Discover why Lithia Motors' fair value suggests a 41% potential upside to its current price, which some investors believe could materialize sooner than many anticipate.
Exploring Other Perspectives
Some of the most optimistic analysts frame Pinewood.AI as the big swing. Before this Q3 update and the leadership shift that put Bryan DeBoer in the Chairman role, they were modelling roughly 8.4% annual revenue growth and around US$1.2b of earnings by 2029. You might see those estimates as ambitious, cautious or somewhere in between, so it can help to compare several viewpoints before deciding how this latest dividend increase, earnings print and governance change might reshape the story for Lithia Motors.
Explore 3 other Lithia Motors fair value estimates, including one that suggests as much as 41% upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Lithia Motors research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Lithia Motors. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Lithia Motors' overall financial health at a glance.
Looking for more investment ideas beyond Lithia Motors?
Once you have a view on Lithia Motors, it can help to compare it with other opportunities that match your risk profile, income needs or balance sheet preferences using the Simply Wall St Screener.
- If you want potential income and resilience together, focus on companies with stronger yields and payout histories using our curated set of 5 dividend fortresses.
- If capital preservation matters most to you, filter for businesses with healthier debt profiles and liquidity by starting with this 30 resilient stocks with low risk scores.
- If you prefer solid finances as your foundation, look at companies backed by cleaner leverage and fundamentals through this list of solid balance sheet and fundamentals (25 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com