


Pfizer (PFE) Showcases IDWeek Data, Is The Stock Fully Priced?
Recent IDWeek data keeps Pfizer’s infectious disease engine in focus
Pfizer (PFE) is putting its infectious disease research front and center, presenting more than 50 vaccine and antiviral data sets at IDWeek 2026 in Washington, D.C., later in October.
The package spans late stage results for pneumococcal, COVID 19, Lyme disease, RSV and meningococcal programs. These programs sit alongside a market value of US$173.4b and a share price of US$30.03 as of October 21.
Pfizer shares at US$30.03 have picked up momentum recently, with a 90 day share price return of 22.37% and a year to date share price return of 19.26%. The 1 year total shareholder return of 29.79% contrasts with a 5 year total shareholder return that is still down 10.55% despite support from dividends.
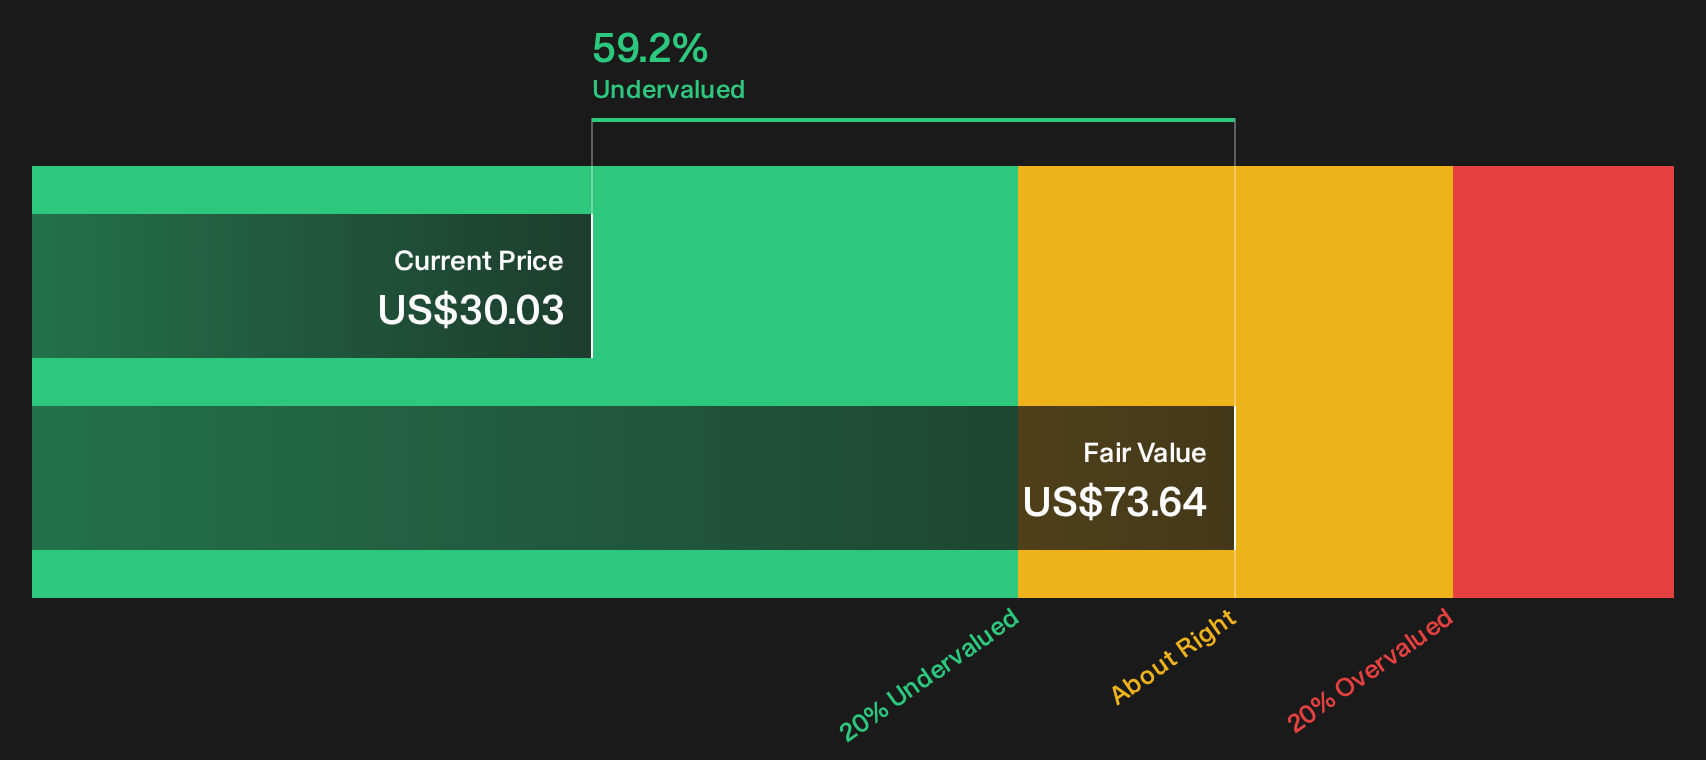
Capitalize on the renewed interest in infectious disease by scanning a hand picked list of 34 healthcare AI stocks working at the intersection of vaccines, data and diagnostics.Pfizer’s share price recovery and a headline intrinsic discount of about 59% tell very different stories. Is the recent rebound closing a genuine valuation gap, or is it simply reflecting the market’s caution on future earnings power?
Most Popular Narrative: 4% Overvalued
Pfizer’s most followed narrative pegs fair value at $28.88, slightly below the last close at $30.03. This points to a mild premium that investors need to weigh against the current infectious disease momentum.
Expansion of launched and acquired products, which management now describes as running at around a US$13b annualized revenue rate and growing in the 20% range, continues to support the view that Pfizer can further shift its mix toward non COVID therapies and sustain revenue as loss of exclusivity pressures emerge.
See why 547 investors see Pfizer as 4% overvalued.
Result: Fair Value of $28.88 (OVERVALUED)
Still, pressure on drug pricing and the planned step down in COVID revenue from about US$11b in 2024 to US$4b in 2026 could test the Pfizer narrative.
Find out about the key risks to this Pfizer narrative.
Another View on Pfizer’s valuation
The market is split on Pfizer. Our DCF model suggests the stock trades at a steep discount, with a future cash flow value of about $73.64 per share versus the current $30.03 price. That points to an undervalued setup. The question is whether you trust the cash flow path or the more cautious earnings multiples.
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Sentiment around Pfizer is clearly mixed, with enthusiasm for infectious disease work sitting alongside questions on long term earnings power and valuation. To sort signal from noise quickly and build your own view on whether the trade off is worth it, go straight to the 2 key rewards and 4 important warning signs.
Looking for more investment ideas beyond Pfizer?
If Pfizer has sharpened your focus on opportunities, do not stop here. Fresh ideas often come from comparing very different businesses side by side.
- Target potential mispricings by scanning a curated pool of companies that combine quality fundamentals with attractive entry points through the 28 high quality undervalued stocks.
- Build a cash flow focused watchlist by zeroing in on resilient payers using the 5 dividend fortresses.
- Reduce unpleasant surprises by focusing on financially robust businesses through the list of solid balance sheet and fundamentals (25 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com