


Earnings Beat Might Change The Case For Investing In Alaska Air Group Stock (ALK)
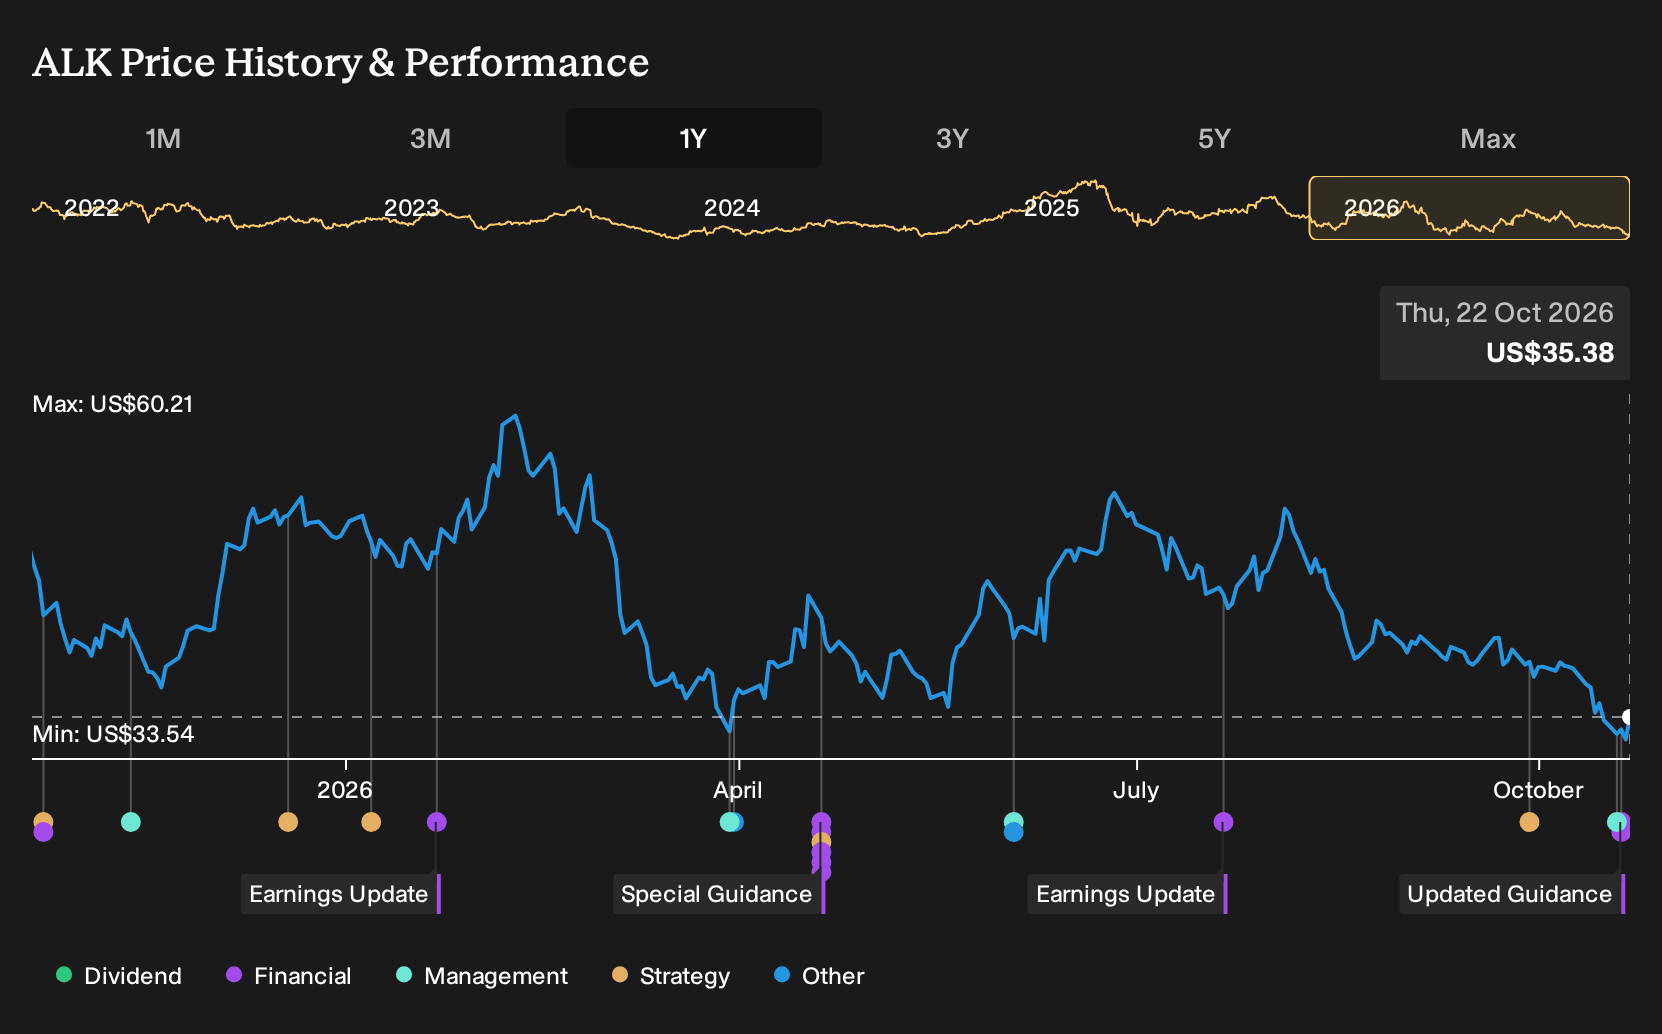
- Alaska Air Group reported third quarter 2026 results showing revenue of US$4,308 million and an adjusted profit but a GAAP net loss, with higher fuel costs and Hawaiian market weakness weighing on overall performance.
- Management kept its growth agenda intact, pointing to premium cabins, loyalty, cargo and international expansion as key levers, even while guiding to a wider adjusted loss for 2026.
- Now the focus shifts to how Alaska Air Group's investment narrative absorbs an adjusted earnings beat alongside pressure from elevated jet fuel costs.
Alaska Air Group Investment Narrative Recap
For Alaska Air Group, the core belief is that premium cabins, loyalty, cargo and international flying can offset a currently loss making base business. The near term swing factor is still jet fuel. Management is guiding to a wider adjusted loss in 2026 as elevated fuel costs meet heavier Hawaii exposure and integration spending.
Fourth quarter guidance points to capacity up 1% to 1.5% and unit revenue up in the low double digits, helped by yield strength and more international flying. That supports the revenue mix shift story. The key risk right now remains fuel staying high while leverage and Hawaiian softness strain cash generation.
The clearest link to the current debate is Alaska Air Group’s new fourth quarter 2026 outlook. Management expects healthy demand and commercial momentum, with unit revenue up in the low double digits and capacity growth focused on international routes, while unit costs excluding fuel are set to rise in the mid single digits.
For you as a shareholder, that guidance ties directly into both catalysts and risks. International expansion and yield strength feed the premium and loyalty thesis. At the same time, an anticipated adjusted loss and higher cost base underline exposure to fuel, leverage and execution on Hawaiian integration, which still need to progress cleanly.
What The Current Alaska Air Group Forecasts Assume
Alaska Air Group's narrative projects US$19.2b revenue and US$1.5b earnings by 2029. This is based on analysts' assumption of 9.1% yearly revenue growth and an earnings change of about US$1.7b, from a loss of US$175.0m today to that US$1.5b profit.
Uncover why Alaska Air Group's fair value indicates a 56% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Three fair value views from the Simply Wall St Community span roughly US$52 to US$175, so retail opinions on Alaska Air Group already stretch from deep discount to rich premium. Layer that on to fuel risk, leverage and the Hawaiian integration story and you get very different conclusions. You should compare these viewpoints directly.
Explore 2 other Alaska Air Group fair value estimates, including one that suggests it could be worth just $52.31!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Alaska Air Group research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Alaska Air Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Alaska Air Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond Alaska Air Group?
If the Alaska Air Group story has sharpened your thinking, the next step is to cast a wider net. Use the Simply Wall St Screener to line up other businesses with traits that match how you like to invest, then compare their fundamentals side by side before committing capital.
- If you are hunting for quality at a sensible entry point, scan a focused set of 29 high quality undervalued stocks that combine stronger fundamentals with market prices that may not fully reflect them.
- If balance sheet strength matters most to you, filter for companies on our list of solid balance sheet and fundamentals (26 results) so you can concentrate on businesses with sturdier financial foundations.
- If you prefer ideas that many investors have not yet crowded into, review the curated 20 high quality undiscovered gems that pair resilient financials with lower profile stories.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com