


Can Fabege (OM:FABG) Look Cheap As Q3 Earnings Rebound?
How Fabege’s latest earnings reshape the risk picture
Fabege (OM:FABG) just posted third quarter numbers that sharply changed its income statement, with SEK 700 million in net profit from continuing operations compared with SEK 99 million a year earlier.
That shift in profitability came alongside revenue of SEK 1,285 million for the quarter and SEK 3,471 million for the first nine months of 2026, a level that contrasts with the prior year’s weaker result and a reported loss for the same nine month period in 2025.
Recent trading has been tougher for Fabege shareholders, with the share price down 6.4% over the past month and 12% over 90 days, and the year to date share price return down 20%, while the 1 year total shareholder return has fallen 24%. This suggests the strong earnings rebound is being weighed against lingering concerns about long term risks in the property portfolio.
Compare Fabege’s rebound with other property and real asset opportunities by scanning the hand picked list of solid balance sheet and fundamentals (204 results) that is aligned with stronger earnings quality and balance sheet support.
Fabege’s share price has fallen sharply while analyst targets sit only moderately higher than today’s level. The next step is clear: how much of that discount reflects real risk rather than opportunity?
Most Popular Narrative: 12% Undervalued
Fabege’s most followed valuation view points to a fair value of about SEK 73.97 per share, compared with the last close at SEK 64.80. This places the recent earnings rebound inside a broader story that mixes Stockholm office risk with earnings recovery potential.
Fabege's concentrated portfolio in prime Stockholm locations positions it to benefit from ongoing urban migration and population growth, supporting future increases in occupancy rates and rental income as office demand slowly recovers (impact: revenue, margins).
The company's strong commitment to sustainable, certified properties, including new energy initiatives and a refreshed green finance framework, makes its assets more attractive to ESG-conscious tenants and investors, which could enable higher occupancy, rental pricing power, and lower long-term vacancy (impact: revenue, NAV growth).
Find out how 2 investors see Fabege as 12% undervalued.
Result: Fair Value of SEK73.97 (UNDERVALUED)
Still, weak Stockholm office demand and ongoing property value declines leave Fabege exposed to softer rents and equity pressure if those trends deepen.
Find out about the key risks to this Fabege narrative.
Another View: What Fabege’s P/E Is Really Saying
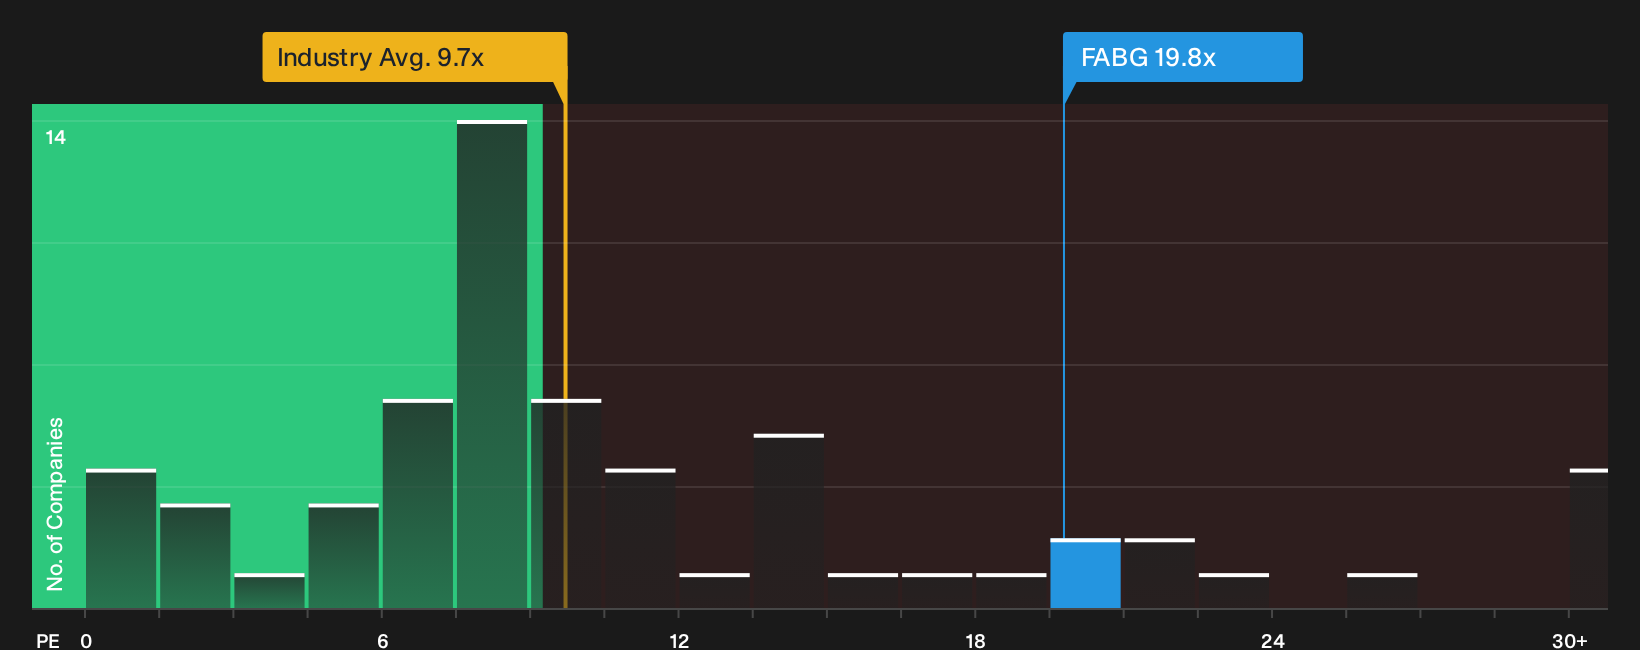
Fair value models put Fabege at SEK 73.97 per share, which implies upside from the last close at SEK 64.80. The P/E picture tells a different story. The stock trades on 19.8x earnings compared with 9.8x for the Swedish real estate sector and 11.8x for peers. This suggests buyers are already paying a premium that could limit room for error.
That premium multiple also lines up with an estimated fair ratio of 19.8x, so the price already reflects what the market model suggests it might move toward. The key question for investors is simple: If revenue is expected to decline over the next few years, what would need to go right for this higher P/E to still feel comfortable?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Fabege’s recovery story so far. Act while the information is fresh, review the underlying data, and weigh both the 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Fabege?
Do not stop with a single stock. Use the same structured approach that highlighted Fabege to widen your opportunity set and pressure test your portfolio choices.
- Target potential mispricing by scanning a curated mix of quality and value through the 190 high quality undervalued stocks that applies consistent fundamentals across the market.
- Strengthen your income plan by reviewing the 225 dividend fortresses that focuses on higher yielding businesses with the support to keep paying shareholders.
- Cut down on unpleasant surprises by checking the 222 resilient stocks with low risk scores that filters for companies with more resilient risk profiles and sturdier fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com