


How Investors Are Reacting To Hormel Foods (HRL) Portion Pack Bacon Launch
- Hormel Foods introduced HORMEL BLACK LABEL Portion Pack Bacon in October 2026, a 12 oz. product with three perforated sections of four slices each, priced at a suggested US$5.97 to US$6.97 range to let shoppers cook only what they need and keep the rest sealed.
- The portioned format targets consumer demand for convenience and waste reduction, which directly links to Hormel Foods' focus on value added protein offerings that can improve mix and support branded bacon demand.
- This article examines how Hormel Foods' investment narrative is affected by portion pack bacon aimed at convenience and reduced food waste.
Hormel Foods Investment Narrative Recap
For Hormel Foods, the big picture to consider is a shift toward higher value protein, more foodservice exposure and a cleaner portfolio, while earnings rebuild from a period of weaker margins and one off items. The portion pack bacon launch fits the push into convenient, branded protein but on its own is unlikely to move the dial on near term results.
The key near term swing factor is whether Hormel Foods can protect profitability as commodity, freight and logistics costs remain a pressure point and pricing elasticity weighs on retail volumes. The biggest risk is that input inflation and volume softness outpace productivity gains, which would keep net margins under strain and slow any earnings recovery.
Among recent developments, the planned Brakebush Brothers acquisition is most relevant when considering catalysts around this bacon launch. Portion packs relate to convenient, value added protein at retail, while Brakebush would deepen Hormel Foods' presence in value added chicken and foodservice, tying both sides of the portfolio to similar consumption trends.
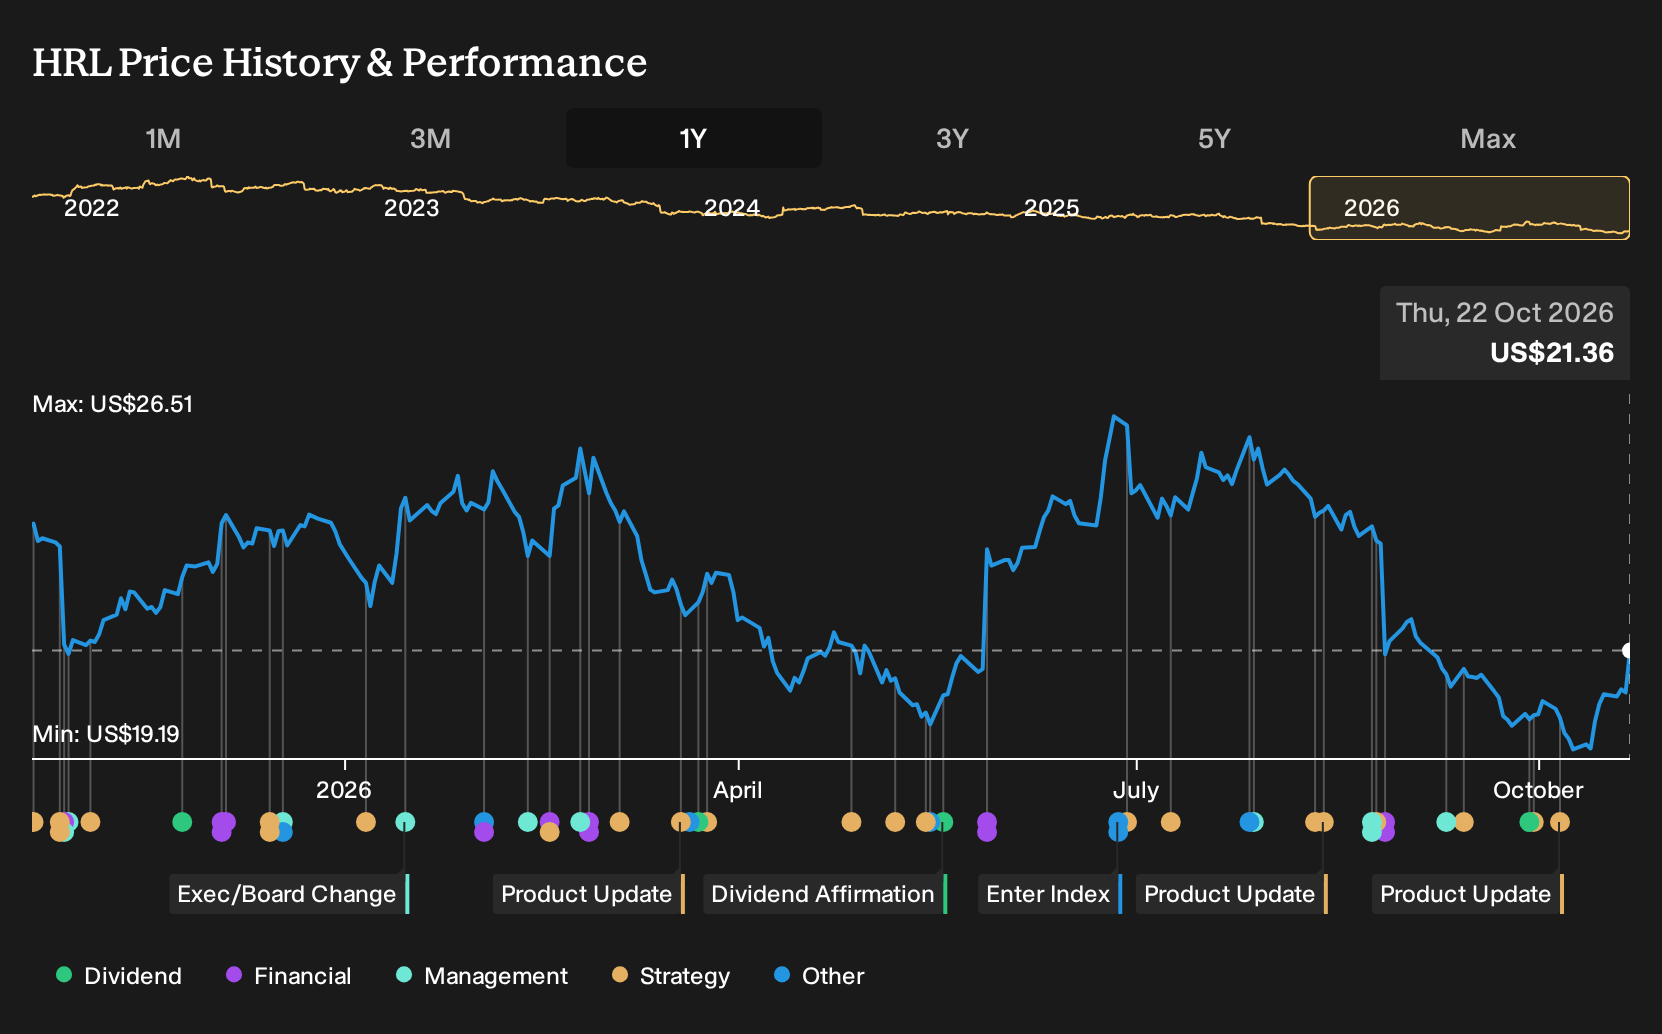
If Brakebush adds the expected US$1.2b of net sales in 2026 and lifts higher margin chicken toward 13% of the protein mix, execution will matter more than any single product. The lens on the bacon rollout is really about whether Hormel Foods can repeatedly execute on product development, pricing and mix so that margin pressure, dividend coverage concerns and recent return underperformance gradually ease.
Hormel Foods' consensus setup assumes revenue of US$12.6b and earnings of US$1.3b by 2029, with analysts building in 1.2% yearly revenue growth and an earnings increase of about US$957m from current earnings of US$342.7m.
Uncover why Hormel Foods' fair value indicates a 19% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community span roughly US$25.31 to US$47.99, so some retail investors see Hormel Foods as significantly undervalued while others set the bar far higher. Set those views against risks around commodity costs and foodservice demand, and consider how these trade offs will shape how you size Hormel Foods in a consumer staples mix.
Explore 2 other Hormel Foods fair value estimates, including one that suggests it could be worth just $25.31.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Hormel Foods research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Hormel Foods. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Hormel Foods' overall financial health at a glance.
Looking For More Investment Ideas Beyond Hormel Foods?
If the Hormel Foods story has you rethinking how you balance quality, income and risk in your portfolio, you can use that momentum to refresh your broader watchlist with a few focused stock searches.
- For investors who want quality at a sensible entry point, consider starting with companies screened for resilient fundamentals and appealing pricing through our 29 high quality undervalued stocks.
- If reliable income matters most to you, focus on businesses that pair higher yields with balance sheet support by reviewing our 6 dividend fortresses.
- When capital preservation is the priority, emphasize sturdier balance sheets and steadier metrics by scanning our 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com