


What A. O. Smith (AOS) Dividend Increase Means For Shareholders
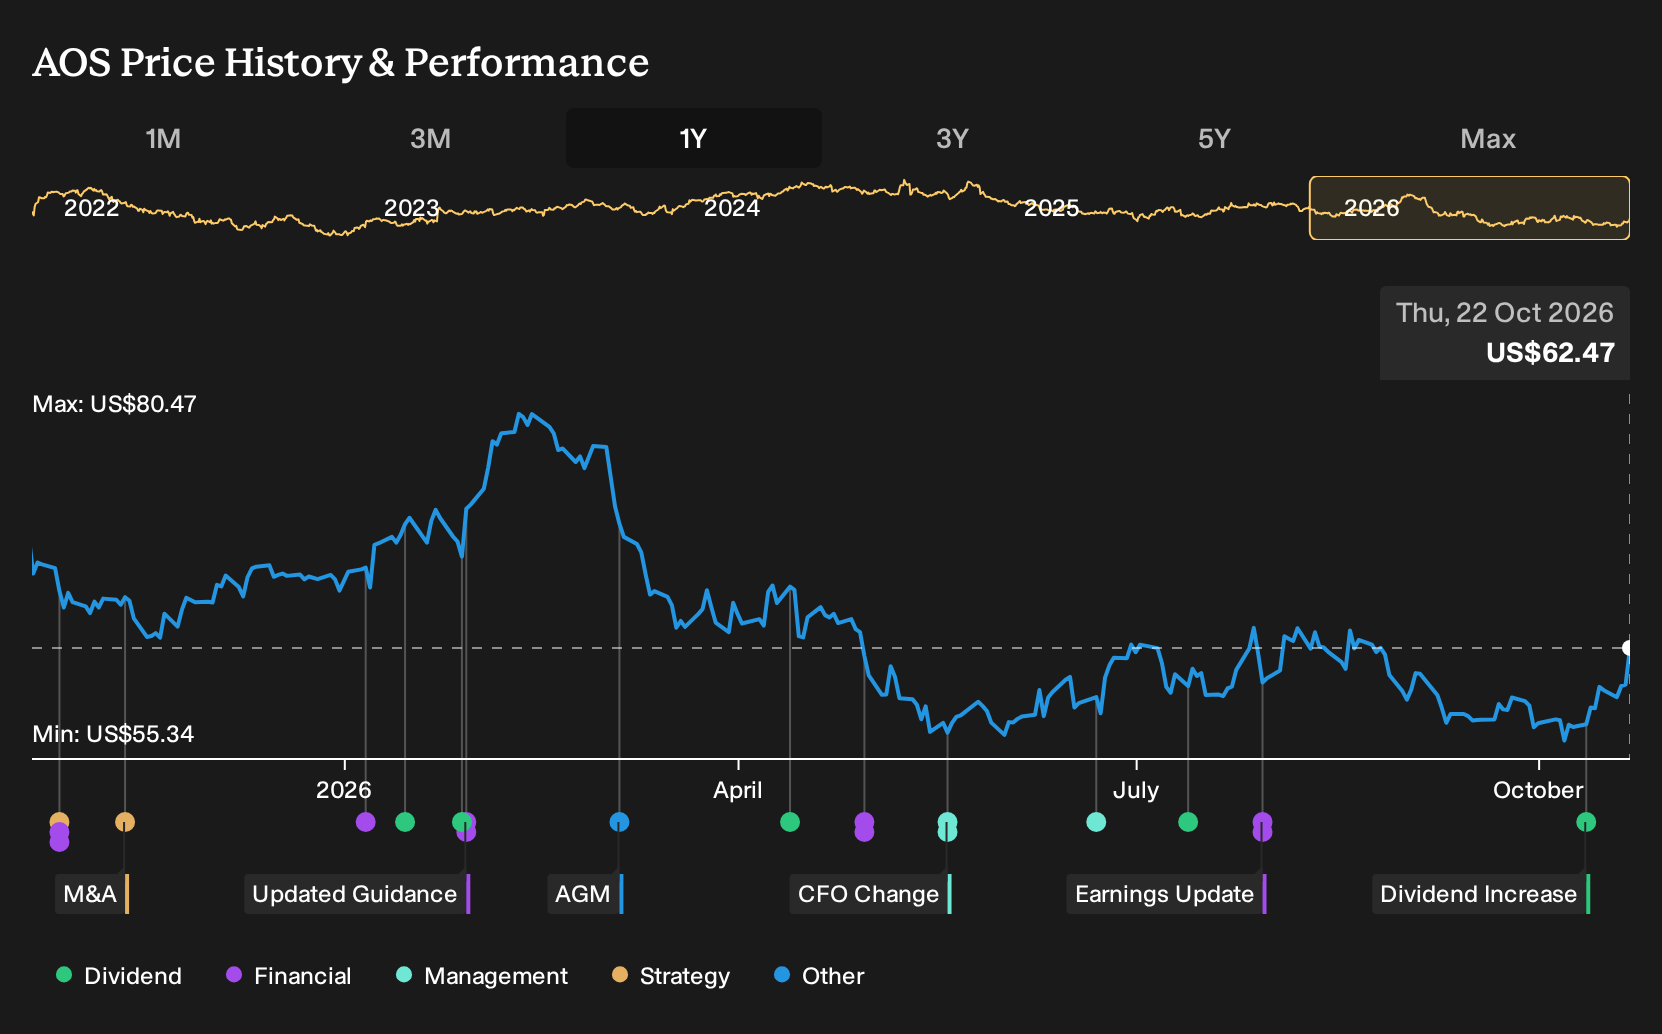
- A. O. Smith's board previously approved a 6% increase in the quarterly cash dividend to $0.38 per share, payable on November 16, 2026, to shareholders of record on October 30.
- The higher payout ties directly into A. O. Smith's focus on cash generation, capital returns, and its shift toward higher value water management platforms.
- We will now look at how this dividend increase could reshape A. O. Smith's investment narrative and long term capital return profile.
Extend the dividend story beyond A. O. Smith by scanning a curated 6 dividend fortresses that echoes the same focus on steady cash returns and balance sheet resilience.
A. O. Smith Investment Narrative Recap
A. O. Smith rewards believers in steady cash generation, disciplined capital returns, and a slow shift toward higher value water management and treatment platforms. To stay comfortable as a shareholder, you need to accept softer residential heater demand in North America and a weaker China business while the product mix tilts toward higher efficiency and connected systems.
The higher dividend points to confidence in free cash flow, but it does not change the near term swing factors. The main upside still comes from efficiency focused products, pricing power, and cost control. The key risk remains further pressure in China or input cost inflation that chips away at margins.
The dividend increase fits neatly with A. O. Smith’s earlier message around strong free cash flow of US$233 million in the first half of 2026 and a modest leverage ratio near 25% debt to total capital. Management has set an expectation that the business can fund growth in water management platforms and still keep returning cash.
For you as an investor, that combination ties the dividend decision to the broader catalyst list. Execution on high efficiency and IoT capable products, along with the North America water treatment realignment that targets US$6 million to US$8 million in annual savings from 2027, becomes even more important because those moves help support both the payout and reinvestment plans if demand stays uneven.
A. O. Smith Dividend Story Through the Analyst Lens
A. O. Smith's dividend increase now sits against analyst expectations that the business can lift both revenue and earnings while keeping capital returns front and center. The forecasts matter because they frame how sustainable that higher payout could be if end markets stay mixed and input costs remain a swing factor.
Consensus numbers anchor the story in a few key assumptions. Revenue is projected to rise by 4.0% per year over the next three years. Profit margins are expected to move from 13.1% today to 14.0% by around 2029. Earnings are forecast to reach US$598.0 million in that year compared with US$500.3 million today, which implies a meaningful step up in profit dollars even before considering any effect from share count reductions.
Those earnings projections sit alongside an expected decline in shares outstanding of 2.39% per year over the same three year stretch. For a dividend focused investor, that pairing of buybacks and higher payouts is important. Fewer shares spread the same cash dividend over a smaller base, which can help support per share income even if operating trends move around from year to year.
Valuation work from analysts ties these operating forecasts into a market view. The current consensus price target of US$66.5, versus a share price of US$58.68 as of the latest report, builds on an outlook where 2029 revenue reaches US$4.3b and earnings hit US$598.0 million. That scenario also assumes A. O. Smith trades on a P/E of 18.0x in 2029, compared with 15.9x today and below the 19.7x multiple cited for the broader US Building industry.
The gap between the most optimistic and most cautious price targets, from US$80.0 down to US$55.0, shows that professional opinion is not uniform. As a shareholder or prospective investor, this spread underlines the need to test how comfortable you feel with the idea that A. O. Smith can grow higher efficiency and water treatment platforms, manage China exposure, and maintain its current approach to cash returns.
A. O. Smith's narrative projects US$4.3b revenue and US$598.0 million earnings by 2029. This assumes 4.0% yearly revenue growth and an earnings increase of about US$97.7 million from US$500.3 million today.
Uncover how A. O. Smith's fair value indicates a 6% potential upside to its current price, which could narrow quickly if A. O. Smith executes cleanly on its plan.
Exploring Other Perspectives
One optimistic twist on A. O. Smith centers on faster adoption of high efficiency commercial heaters and boilers. Bullish analysts were already penciling in revenue of about US$4.4b and earnings of US$636.4 million by 2029 before this 6% dividend increase. That more upbeat story may evolve, and you can weigh how your view compares.
Explore 4 other A. O. Smith fair value estimates, including one that suggests as much as 32% upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your A. O. Smith research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for A. O. Smith. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate A. O. Smith's overall financial health at a glance.
Looking For More Ideas Beyond A. O. Smith?
If A. O. Smith's dividend story has sharpened your focus on income, quality, and balance sheet strength, it can help to line it up against a wider watchlist built around similar themes.
- For investors who want potential upside with strict risk filters, start with a shortlist of 30 resilient stocks with low risk scores that keep volatility and financial stress in check.
- If value and quality are your main filters, widen your opportunity set by reviewing a curated 29 high quality undervalued stocks that blends solid fundamentals with appealing pricing.
- Income focused readers who like A. O. Smith's payout profile can round out their research with a hand picked 6 dividend fortresses that emphasizes durability of cash distributions.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com