


How Investors May Respond To Vistry Group (LSE:VTY) Stronger UK Jobs Data
- Recent UK labour market data showed unemployment falling and wage growth holding steady, which supported sentiment toward Vistry Group and other housebuilders that depend on employment and household income stability.
- The figures reinforced the importance of Vistry Group's partnerships and affordable housing focus, where government support and steady incomes can underpin demand even when private sales are under pressure.
- We will now look at how this stronger labour market backdrop could influence Vistry Group's investment narrative and affordable housing focus.
Scan how Vistry Group’s affordable housing angle compares with other resilient UK-focused opportunities by reviewing the hand-picked 4 resilient stocks with low risk scores that may hold up better when sentiment swings.
Vistry Group Investment Narrative Recap
To own Vistry Group, you need to believe its partnerships and affordable housing model can translate a steadier demand base into healthier margins and consistent cash generation over time. The recent improvement in UK labour data supports that demand backdrop but does not by itself fix execution issues in areas like the South Division or building safety costs.
The main near term swing factor is how well Vistry Group converts its government backed pipeline into profitable Partner Funded projects while keeping work in progress tightly controlled. The biggest risk remains pressure on margins and cash flow if private sales stay soft and high net debt meets any further operational setbacks.
No fresh regulatory filings or trading updates have been flagged alongside this labour market news. The most relevant reference point is still management’s prior commitment to optimise stock levels and work in progress. That operational focus matters more when sentiment turns a little more supportive, because it shapes how much of any revenue tailwind actually reaches the bottom line.
The partnerships strategy, including increased use of timber frame manufacturing and a leaner organisational structure, is central to the current catalyst story. Execution here could influence whether Vistry Group converts affordable housing volume into better net margins, or whether ongoing building safety costs and planned leverage keep dragging on reported earnings even if demand holds up.
Vistry Group's narrative projects £3.7 billion in revenue and £134.9 million in earnings by 2029. This assumes 2.7% yearly revenue growth and an earnings improvement of about £635 million, from a loss of £500.3 million today to the 2029 forecast.
Uncover why Vistry Group's fair value indicates a 16% potential upside to its current price before the discount closes.
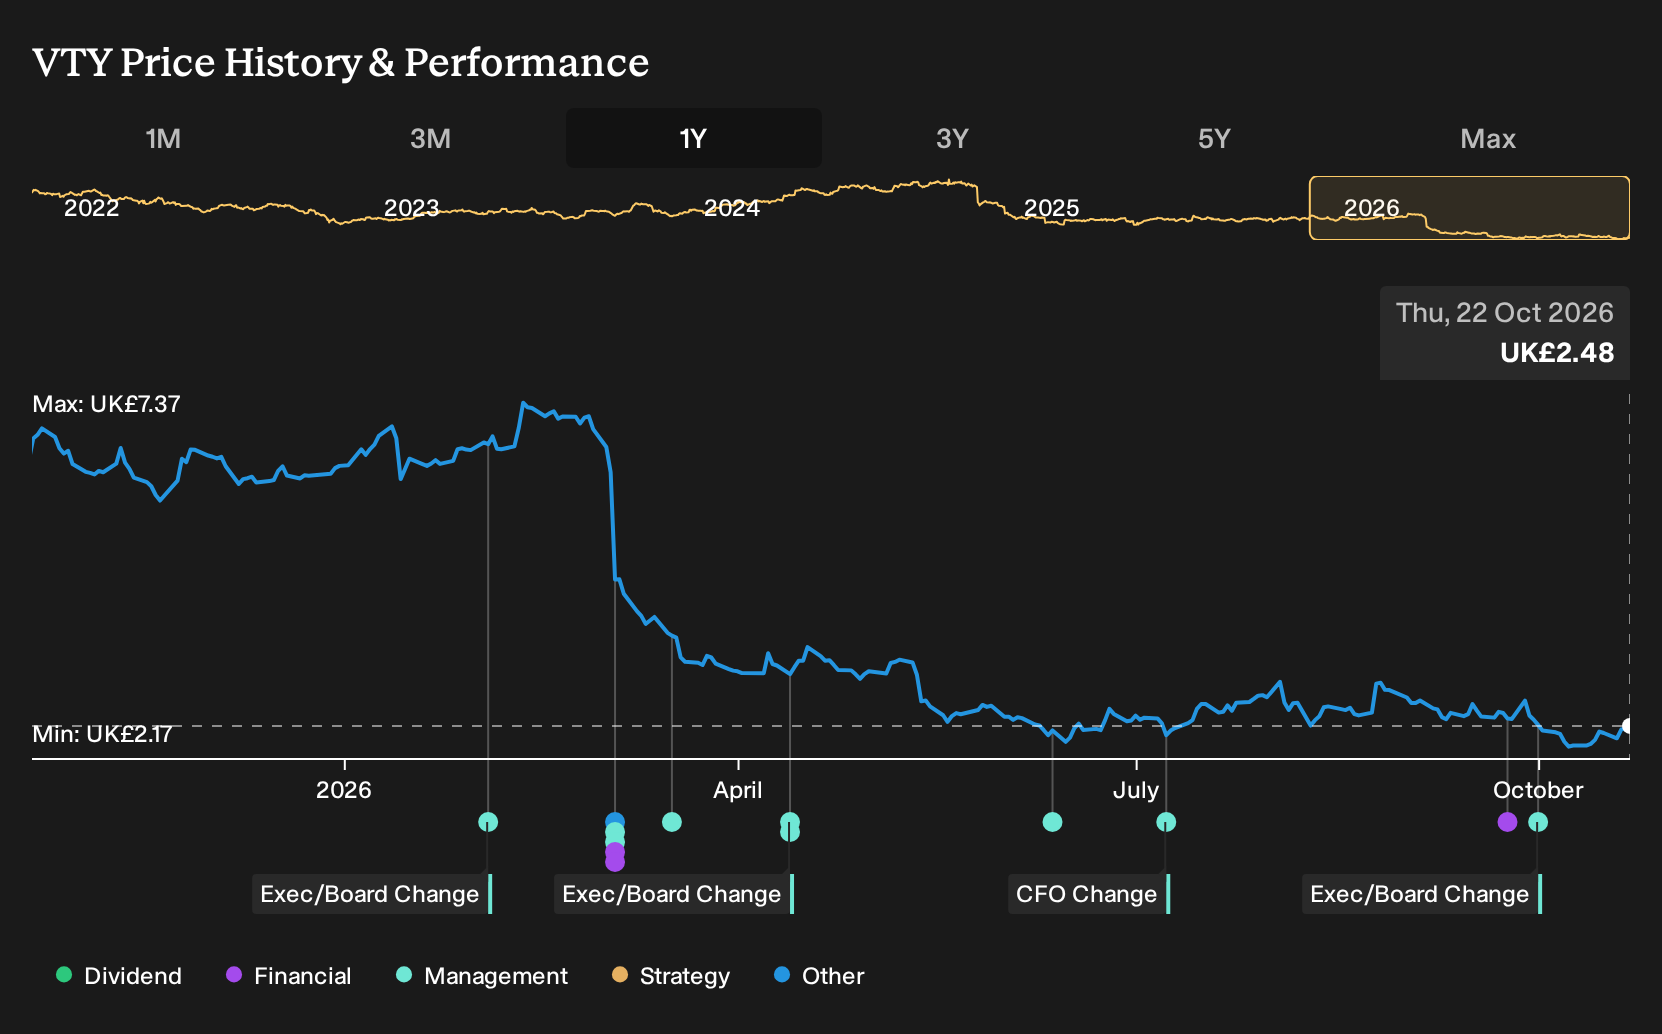
Exploring Other Perspectives
Some of the most optimistic analysts argue the real catalyst for Vistry Group is not the labour data at all but the push toward 12,000 units a year with about £4.8b of revenue and £214.6m in earnings by 2029. Their story is much brighter than consensus, and both views were formed before this latest employment surprise, so you may want to compare these different assumptions yourself.
Explore 4 other Vistry Group fair value estimates, including one that suggests a potential upside of up to 153% from the current price.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Vistry Group research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Vistry Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Vistry Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond Vistry Group?
If Vistry Group has sharpened your focus on risk, income and balance sheet strength, it can help to widen the lens and compare it with other listed businesses that share some of those qualities but operate in different pockets of the market.
- For investors who want potential mispricing with a quality filter, scan through 7 high quality undervalued stocks that already combine stronger fundamentals with attractive pricing signals.
- If reliable income matters most to you, anchor your shortlist with 4 dividend fortresses that aim to pair higher yields with more resilient payout profiles.
- When capital preservation is front of mind, build a watchlist starting from the list of solid balance sheet and fundamentals (9 results) and compare how each business manages debt and liquidity through different conditions.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com