


UCB (ENXTBR:UCB) Jumped, What Is Behind The Fresh Attention?
UCB (ENXTBR:UCB) just received U.S. FDA approval for a once daily self-administered ZILBRYSQ autoinjector for generalized myasthenia gravis, giving gMG patients a new, convenience focused treatment option.
The FDA green light for ZILBRYSQ's autoinjector lands after a sharp swing in market sentiment, with UCB's 1 day share price return of 21.64% and 7 day share price return of 25.78% pointing to strong short term momentum. At the same time, the 5 year total shareholder return of 162.15% indicates that long term holders have already seen substantial gains.
Spot fresh healthcare momentum by lining up UCB's move with hand picked 127 healthcare AI stocks tapping into patient focused treatments and next generation drug platforms.After a 22% one day jump and a 55% modeled intrinsic discount plus a 9% gap to analyst targets, UCB now looks either attractively mispriced or correctly flagged for risk. Which side fits the numbers that follow?
Most Popular Narrative: 13.9% Overvalued
Against UCB's last close at €259.10, the most followed valuation narrative pegs fair value at €227.49, which frames the current enthusiasm as richer than that reference point and puts more weight on how that estimate is built.
The number to watch is the discount rate. This valuation uses a cost of equity of 5,42 %, resting on UCB's own measured beta. The sector-average alternative would imply roughly 9,1 %. That is a wide gap, recorded in my run, not hidden, and it is the single biggest lever in this valuation. At a sector-based discount rate the DCF would be materially lower. Whether UCB's measured low-volatility history or the pharma sector average better describes its risk going forward is a judgement each reader should make consciously.
See why 4 investors see UCB as 14% overvalued.
Result: Fair Value of €227.49 (OVERVALUED)
Still, the overvaluation story could shift quickly if UCB faces pipeline setbacks or if a higher risk premium pushes the cost of equity closer to sector norms.
Find out about the key risks to this UCB narrative.
Another View: UCB Through The SWS DCF Lens
A second yardstick paints a very different picture. Our DCF model values UCB at €580.25 per share, with the current €259.10 price trading 55.3% below that estimate. That points to a wide gap between what cash flows imply and what the market is willing to pay. Which signal do you treat as more credible right now?
Look into how the SWS DCF model arrives at its fair value.
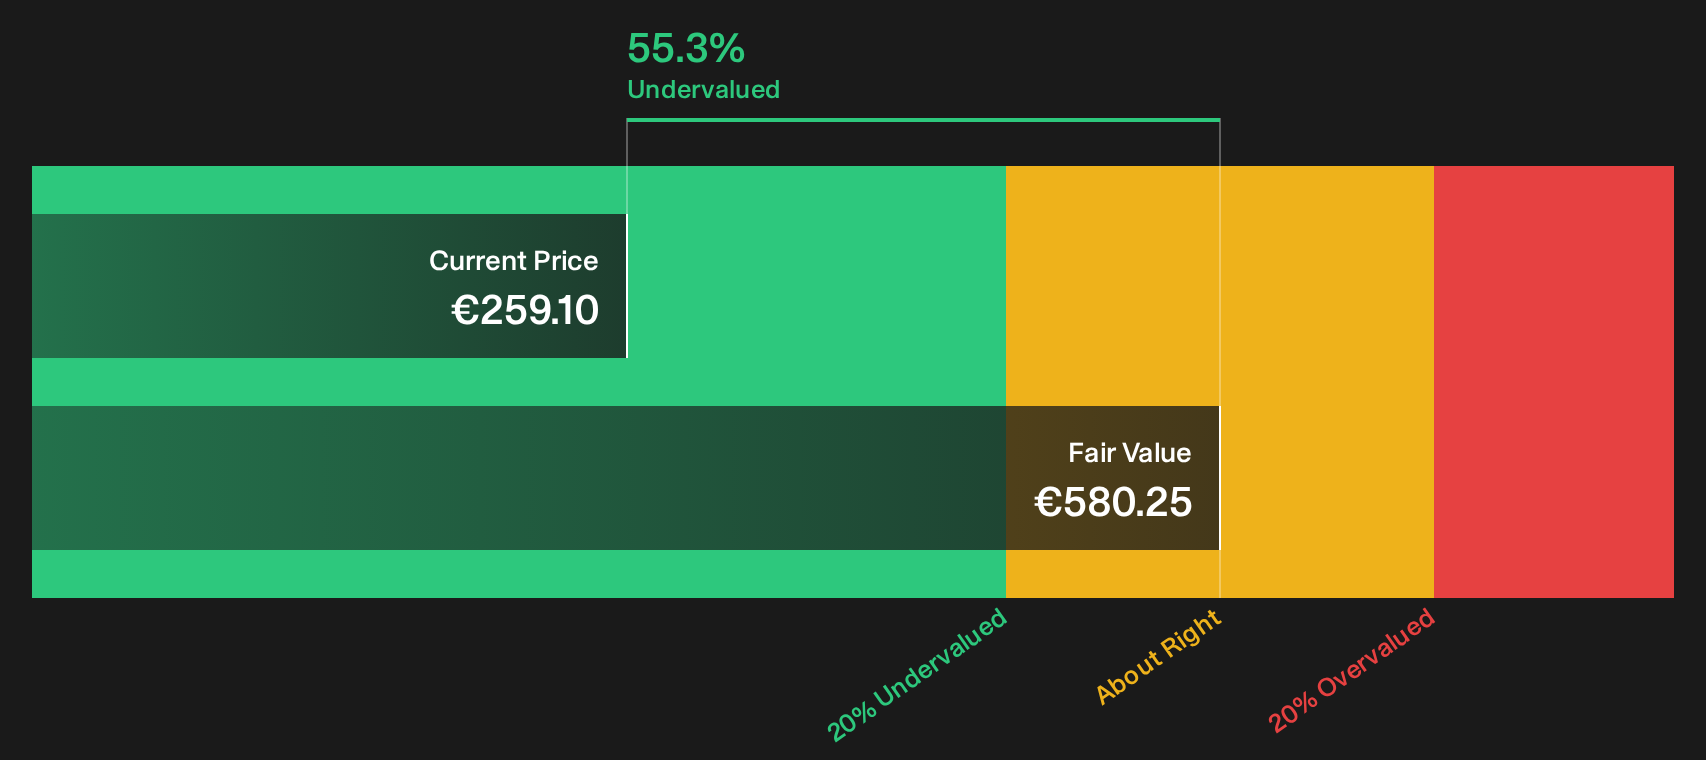
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out UCB for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 191 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Investors who are concerned that the narrative around UCB is being shaped more by headlines than by fundamentals, yet want to assess whether the balance of risk and reward supports the current sentiment, can review the full breakdown and consider both perspectives in detail through 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond UCB?
If UCB has sharpened your focus on quality, do not stop here. Broaden your watchlist now and let data-rich screens surface your next opportunity.
- Target resilient balance sheets by scanning companies on the list of solid balance sheet and fundamentals (203 results) that pair prudent debt levels with grounded fundamentals.
- Hunt for pricing gaps through the 191 high quality undervalued stocks where stronger cash flows and sturdier financial profiles may not yet be fully reflected in market prices.
- Prioritise staying power and quality by tracking the 223 resilient stocks with low risk scores that filters for businesses with lower risk scores and more durable fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com