


JD.com (JD) Stock Could Be A Bargain On Earnings
JD.com has seen its share price under pressure in recent years, which naturally pushes investors to ask whether the current valuation still lines up with what the business is earning. With the stock closing at US$25.68 most recently, the core question is how well that price reflects JD.com’s earnings power today.
- The share price has fallen 62.7% over the past 5 years, which puts the focus squarely on whether the market is now correctly weighing JD.com’s earning capacity.
- The group’s model as a large scale online retailer makes its profit profile highly sensitive to execution on costs, logistics efficiency and take rates, so shifts in those drivers can reshape what a fair earnings multiple looks like.
- Your read on JD.com is one view; the desks covering it have another. See what analysts think JD.com's shares could be worth.
The stock’s next move may depend on whether JD.com’s current earnings are strong and durable enough to justify the price investors are paying today.
If you are questioning whether JD.com’s earnings still justify its current price, it can help to compare that same valuation test across 30 high quality undervalued stocks.
Is JD.com Still Cheap on Earnings?
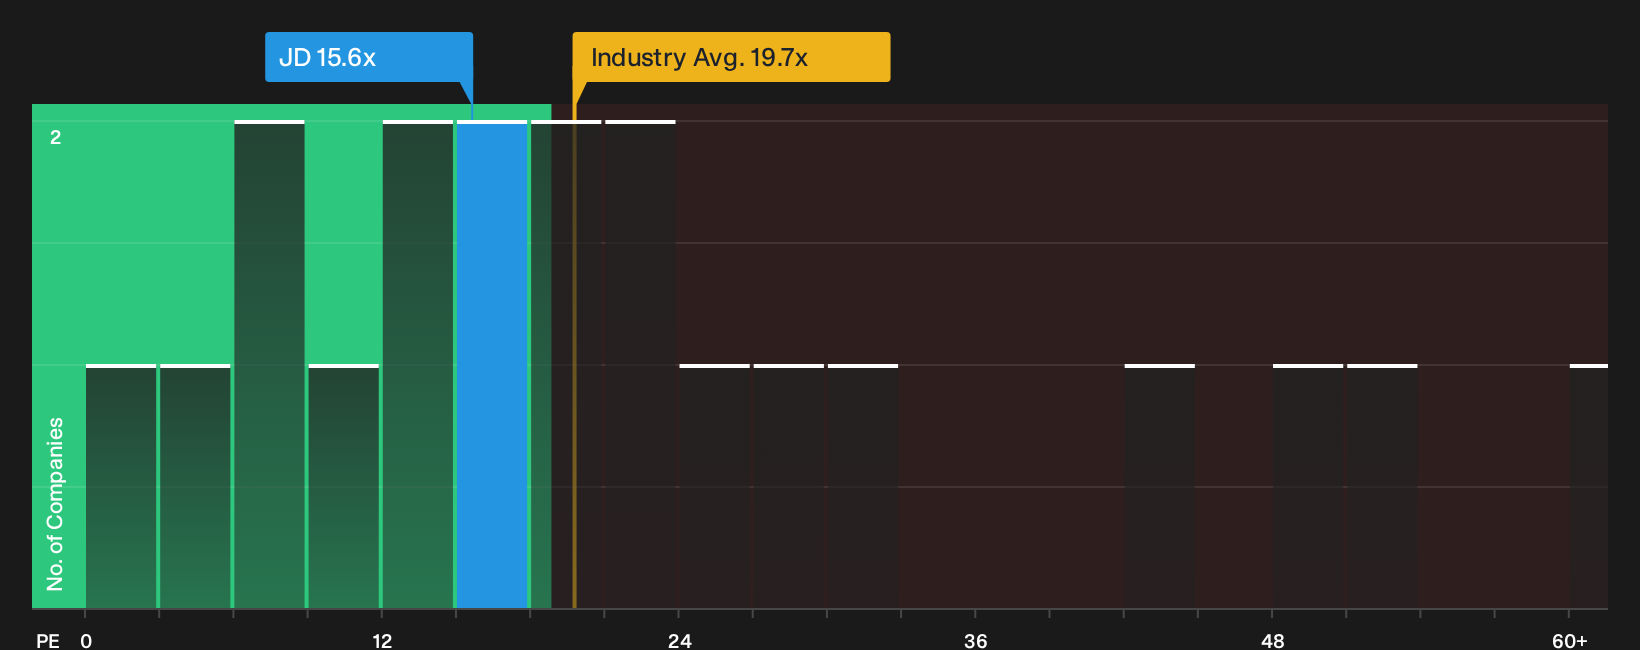
The P/E ratio fits JD.com reasonably well because earnings still sit at the center of how investors frame a large online retailer. On this yardstick, the stock trades at about 15.6x earnings, which is below the broader multiline retail sector on roughly 19.7x and far under the peer group near 29.4x. That gap means the market is attaching a lower price tag to each dollar of JD.com profit than it does to many comparable businesses.
A more tailored yardstick that blends JD.com’s growth profile, profitability, market value and risk suggests the shares could justify a higher P/E than where they are now. Because the current multiple stands below that implied level, the stock screens as undervalued on this specific framework. That still leaves you to judge whether JD.com’s competitive position and earnings quality are strong enough to close any gap the model points to. Explore the numbers behind JD.com's P/E valuation.
The JD.com Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for JD.com extend the valuation puzzle by explaining which future paths for JD.com's growth, margins and earnings would correspond to a meaningfully higher or lower share price than today. These Narratives are available on the platform's Community page. Instead of offering just one output from a ratio or model, they map the set of assumptions that number relies on so you can monitor over time whether those conditions actually play out.
One of the top community narratives on JD.com: 34% undervalued
"The main thing that has to go right is that JD.com continues to expand margins in JD Retail and newer services such as logistics and food delivery…"
Discover why this Narrative puts JD.com at 34% undervalued.
One more JD.com check that sits beside the price tag
Shareholders are not only paying for earnings, they are also trusting the people steering JD.com and the way their rewards line up with long term results. See who runs JD.com and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com