


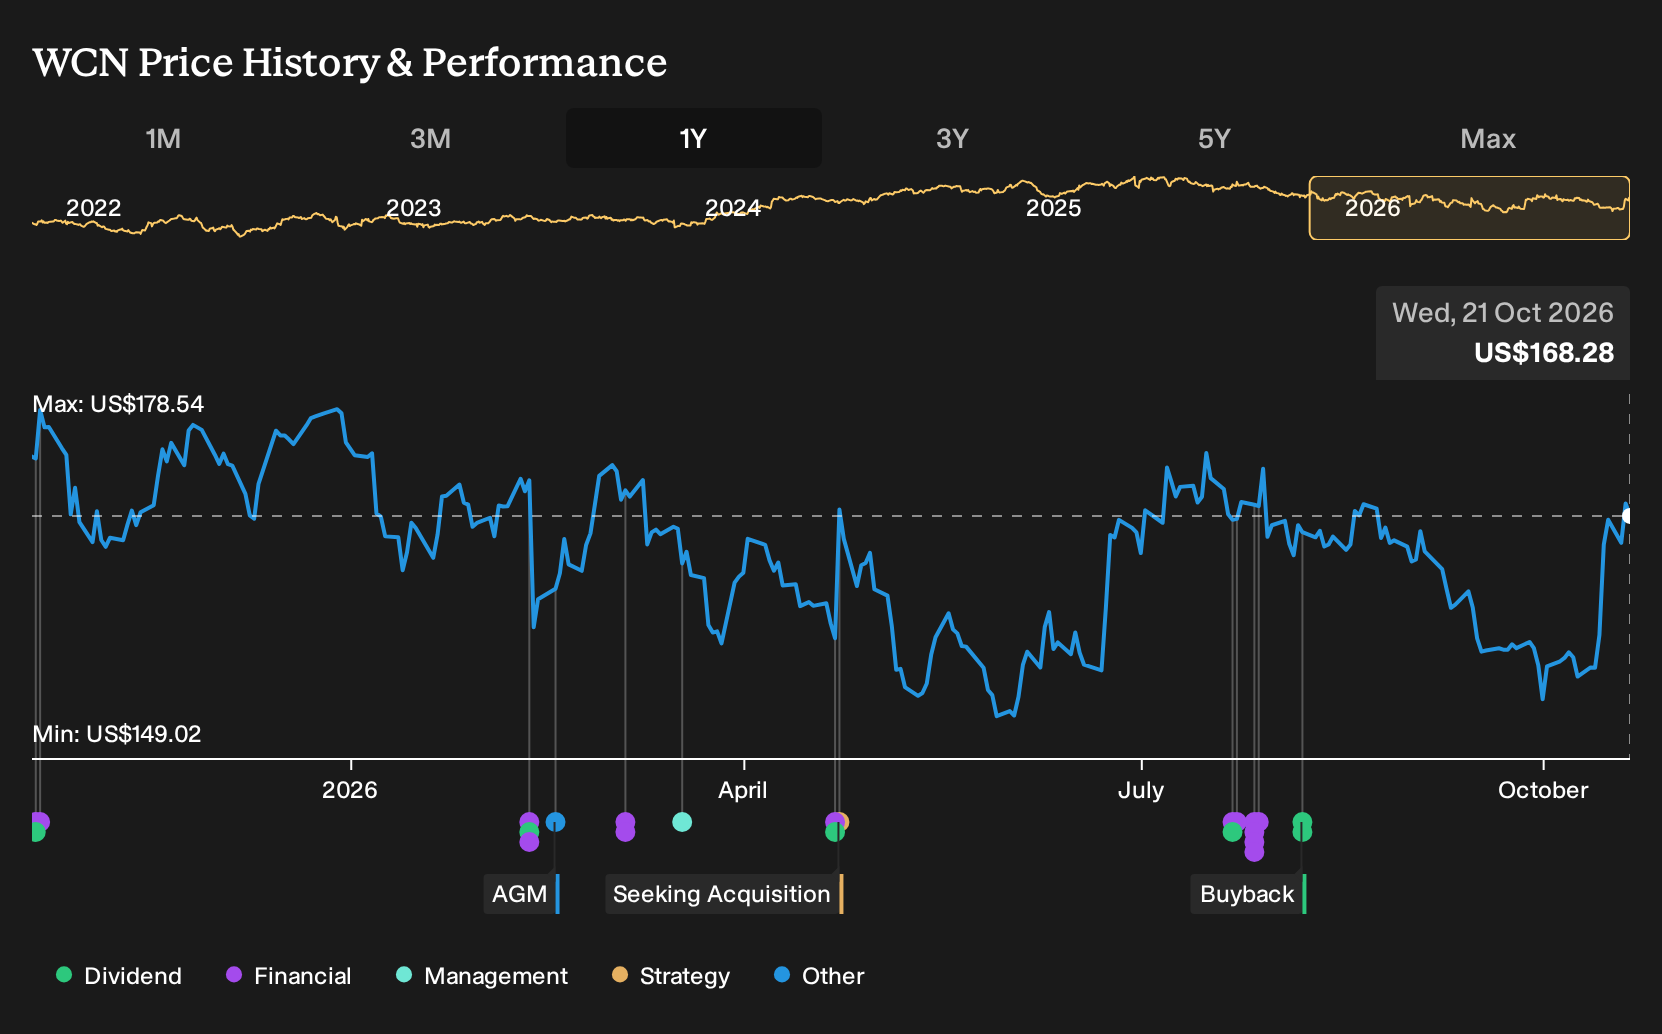
Waste Connections Stock Is Up 9.9% What’s Changed
- Waste Connections reported third quarter 2026 results with US$2.64b in sales, US$359.22m in net income and US$1.43 in diluted EPS from continuing operations, alongside a 10% dividend increase and higher full year revenue and net income guidance.
- The combination of stronger earnings, dividend growth and an upgraded outlook suggests Waste Connections is leaning on operating execution, landfill volumes and commodity related revenue to support both reinvestment and cash returns.
- We will now look at how Waste Connections' upgraded 2026 guidance could reshape the broader investment narrative around the business.
Scan how Waste Connections' earnings, dividend lift and guidance upgrade compare with peers by reviewing our curated 31 resilient stocks with low risk scores featuring resilient balance sheets and steady fundamentals.
Waste Connections Investment Narrative Recap
To own Waste Connections, you need to be comfortable with a story built on steady waste volumes, disciplined pricing and a long build out of AI and digital projects rather than rapid swings. The Q3 beat and higher 2026 guidance support that operating backdrop, but they do not remove the near term drag from Chiquita Canyon remediation or fuel cost pressure.
The key short term swing factor remains how effectively Waste Connections converts higher revenue into cash while Chiquita Canyon consumes US$100m to US$150m in 2026 free cash flow. If those costs creep above the indicated range or run longer, the main risk is a slower improvement in free cash flow than many investors might hope for.
The most relevant update for this story is the new 2026 outlook that pegs revenue at about US$10.09b and net income at roughly US$1.18b. Management backing that view immediately after reporting Q3 sales of US$2.64b and net income of US$359.22m helps tie the recent operating performance to a full year earnings run rate.
For investors, the key consideration is how that guidance sits against the known headwinds and the longer dated margin drivers. Higher fuel costs, Chiquita Canyon spend and the execution risk around US$100m of AI and digital investments are still very present, so the raised outlook mainly reinforces the existing catalyst list rather than changing it.
Waste Connections' outlook indicates projected revenue of US$11.6b and earnings of US$1.6b by 2029. This corresponds to 5.8% annual revenue growth and an earnings increase of about US$500m from the current US$1.1b.
Discover how Waste Connections' fair value indicates a 17% potential upside to its current price that could close more quickly than many investors expect.
Exploring Other Perspectives
You are not alone if you read Waste Connections' Q3 beat and dividend lift as a turning point. The lowest analysts still came in cautious, pencilling in roughly US$11.2b of 2029 revenue and US$1.6b of earnings before this update, and treating slower AI rollout as the swing factor. Their view could shift as fresh numbers filter through. Use this as a prompt to compare multiple narratives before deciding what fits your own expectations.
Explore 2 other Waste Connections fair value estimates, including one that suggests it could be worth just $170.33.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Waste Connections research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Waste Connections. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Waste Connections' overall financial health at a glance.
Looking For More Ideas Beyond Waste Connections?
If Waste Connections has sharpened your view on earnings quality, dividends and guidance, it can be useful to line that up against a broader watchlist built around clear financial traits and risk profiles.
- For investors who want potential mispricing with quality in mind, scan a curated group of financially robust companies through the 33 high quality undervalued stocks.
- If predictable income is a priority, focus on businesses that offer substantial yields by reviewing the 7 dividend fortresses.
- When capital preservation matters just as much as upside, concentrate on sturdier balance sheets using the list of solid balance sheet and fundamentals (25 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com