


Enagás (BME:ENG) 2% Overvalued As Q3 Results Revive Dividend Questions
Enagás (BME:ENG) is back under the microscope after its Q3 2026 update, with nine-month revenue and profit both lower year on year and investors questioning how secure the dividend funding really is.
Recent trading tells a mixed story. The share price is up 29.67% year to date and the 1-year total shareholder return is 28.59%. However, the flat 90-day share price performance hints that enthusiasm around Enagás, Q3 earnings and its hydrogen ambitions is meeting fresh scrutiny over dividend funding and earnings quality.
Pace your income ideas around Enagás by comparing its dividend profile and earnings trends with a curated shortlist of 222 dividend fortresses that also prioritize resilience and cash coverage.With Enagás now trading slightly above the average analyst target yet still flagged as intrinsically cheaper by some models, the real tension is simple: does the current price already capture that gap in views?
Most Popular Narrative: 2% Overvalued
Enagás last closed at €17.33, slightly above the most followed fair value estimate of €17.02. That estimate is built on a €20.38 future cash flow value and a 7.4% discount rate. That small gap leaves the spotlight on whether hydrogen and LNG infrastructure can really carry earnings and support the dividend over time.
The robust policy momentum and increased EU financial commitments to energy security and decarbonization are now reflected in long term LNG regasification bookings in Spain, with unloading slots largely reserved until 2041, which supports visibility for Enagás on future regulated revenue and earnings from its gas network.
Rapid progress in green hydrogen regulation and Spain's leadership in hydrogen production is now matched by concrete investment decisions, with multiple hundred megawatt electrolysis projects reaching final investment decision and billions of euros in public funding awarded, which underpins the case for Enagás to add new hydrogen transport revenue streams and support future margins.
See why 39 investors see Enagás as 2% overvalued.
Result: Fair Value of €17.02 (OVERVALUED)
Still, the Enagás story can crack if regulators cut harder than the current 6.46% draft suggests, or if hydrogen projects face slower offtake and delays.
Find out about the key risks to this Enagás narrative.
Another View: Enagás Through The P/E Lens
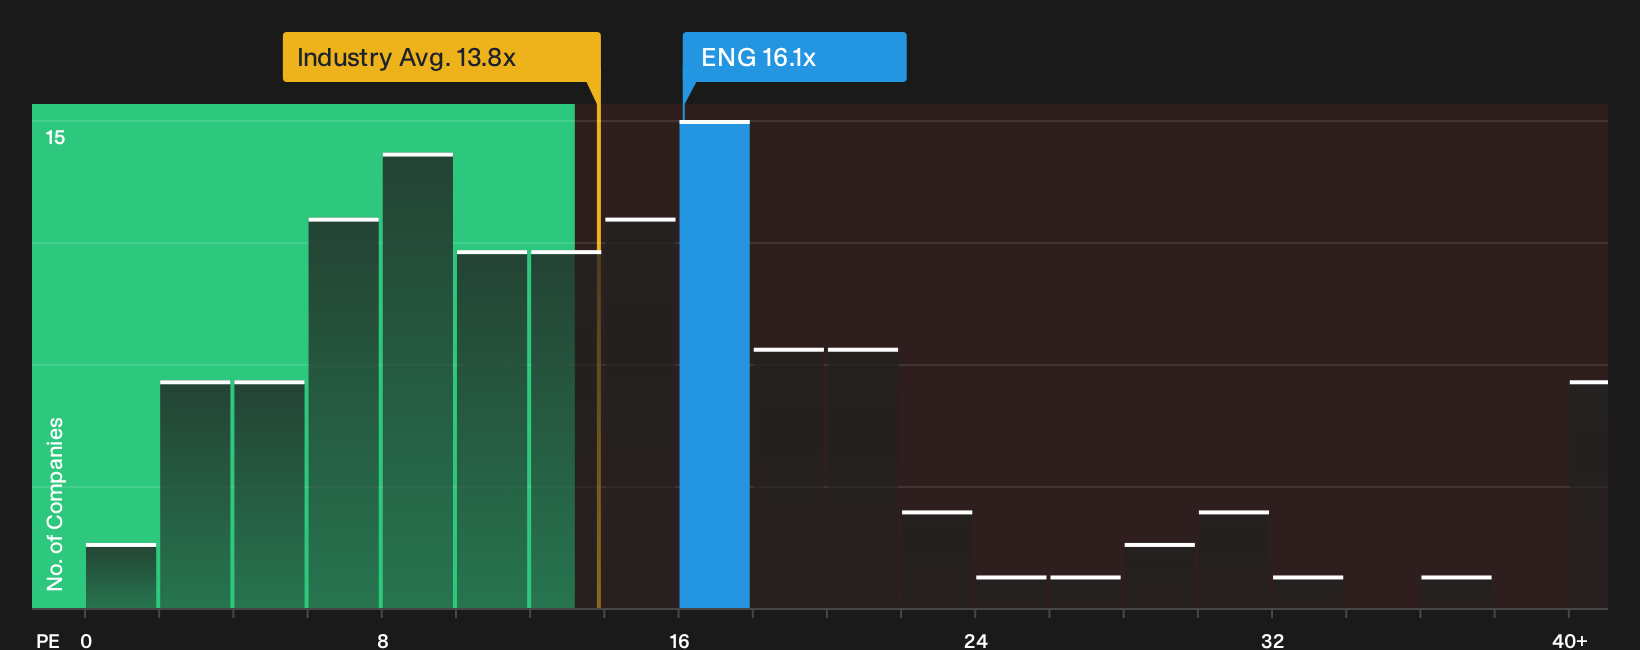
A second look at Enagás uses the P/E ratio instead of future cash flows. The stock trades on 16.1x earnings, above the global gas utilities group at 13.8x, yet below its peer average of 25x and close to a fair ratio of 16.6x. That mix of premium and discount raises a simple question for you: Is the extra price you pay today a cushion or a risk if expectations around hydrogen and regulated returns shift?
See what the numbers say about this price with our valuation breakdown, then compare it with the broader sector using the See what the numbers say about this price — find out in our valuation breakdown..
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Enagás for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 190 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed headlines around Enagás only matter if they change what you do next. Move quickly, dig into the full dataset, and weigh both sides of the story using the 3 key rewards and 2 important warning signs.
Want More Ideas Beyond Enagás?
If you stop with Enagás, you miss the wider opportunity set. Use the screener to spot other candidates that fit your income, quality, and risk preferences.
- Target resilient cash generators by scanning a list of solid balance sheet and fundamentals (203 results) that can help anchor your portfolio when conditions turn tricky.
- Hunt for mispriced quality using a focused 190 high quality undervalued stocks that highlights businesses with strong fundamentals at modest valuations.
- Add fresh growth angles by reviewing a curated 618 high quality undiscovered gems that many investors may not be watching yet.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com