


3 UK Logistics Stocks Worth Watching After The ABP Stake Sale
The £10b stake sale in Associated British Ports has pushed UK infrastructure and logistics operators back into the spotlight, as global capital signals clear interest in assets that keep trade moving. If institutions are reshuffling exposure after the ABP deal, listed port and freight stocks could see fresh attention or fresh scrutiny. This article walks through three UK operators exposed to the same themes to help you stress test your watchlist.
The three stocks covered next are only a sample of what the ABP-driven interest in ports and freight is flushing out, and the full screen surfaced 4 more UK-listed infrastructure and logistics operators with equally solid stories that are not covered here. If you want to immediately identify, compare and analyze UK-listed transport and marine infrastructure plays side by side, head straight into the UK-listed infrastructure and logistics operators screener.
Clarkson (LSE:CKN)
Clarkson is a London based shipping services group that channels global trade flows, fitting the screener’s focus on ports, freight and marine infrastructure exposure. It generates most of its £747 million revenue from Broking at £564 million, with Financial at £79 million, Support at £75 million and Research at £29 million. The stock has a market cap of about £1.6b.
Clarkson gives you exposure to sea freight cycles without owning ports or terminals through broking, logistics support and shipping intelligence that all tie directly into the flow of goods highlighted by the ABP stake sale. Interest in this stock hinges on how one quiet change in trading conditions filters through to pricing power in those service lines.
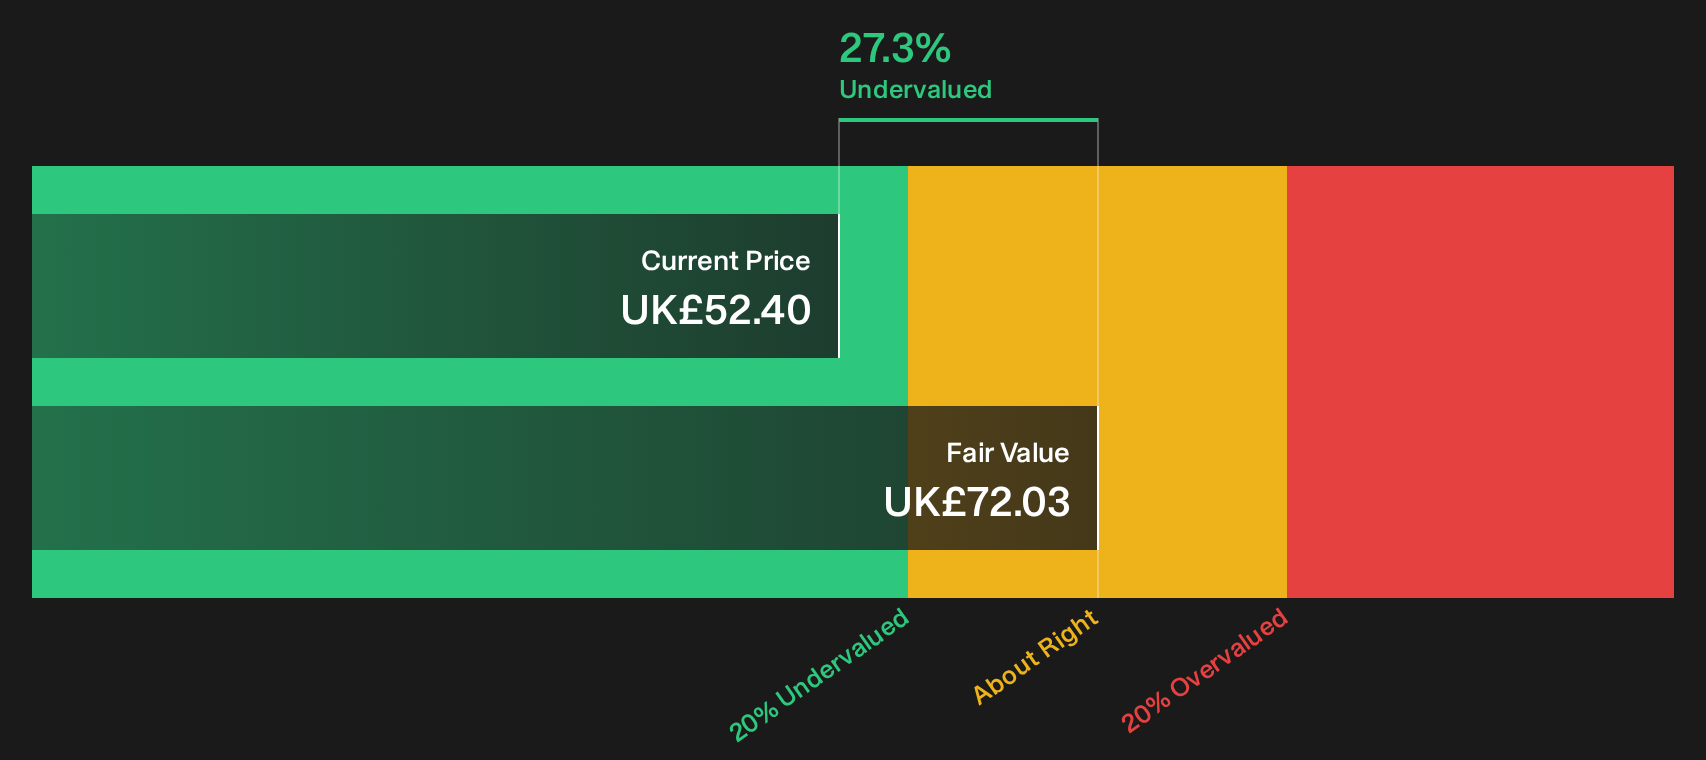
If you want to see how that pricing power story, capital intensity and cash generation fit together, start with the DCF valuation analysis for Clarkson to spot where expectations might be misaligned.
James Fisher and Sons (LSE:FSJ)
James Fisher and Sons plugs into the same UK infrastructure and logistics theme through marine and offshore services, with £141 million from Energy, £105 million from Defence and £153 million from Maritime Transport, and a market value of roughly £230 million anchoring that mix.
James Fisher and Sons provides exposure to the work that keeps ports, offshore platforms and coastal energy logistics running, without owning the physical terminals that headline the ABP story.
"Although the Defense division now has a £315 million order book and a special security agreement in the U.S., contract phasing, intense competition for rising defense budgets and the need to scale local presence could slow how fast these orders convert into revenue and operating profit."
What happens if a single pressure on cash generation and debt costs shifts just as that service pipeline moves from backlog to billed work?
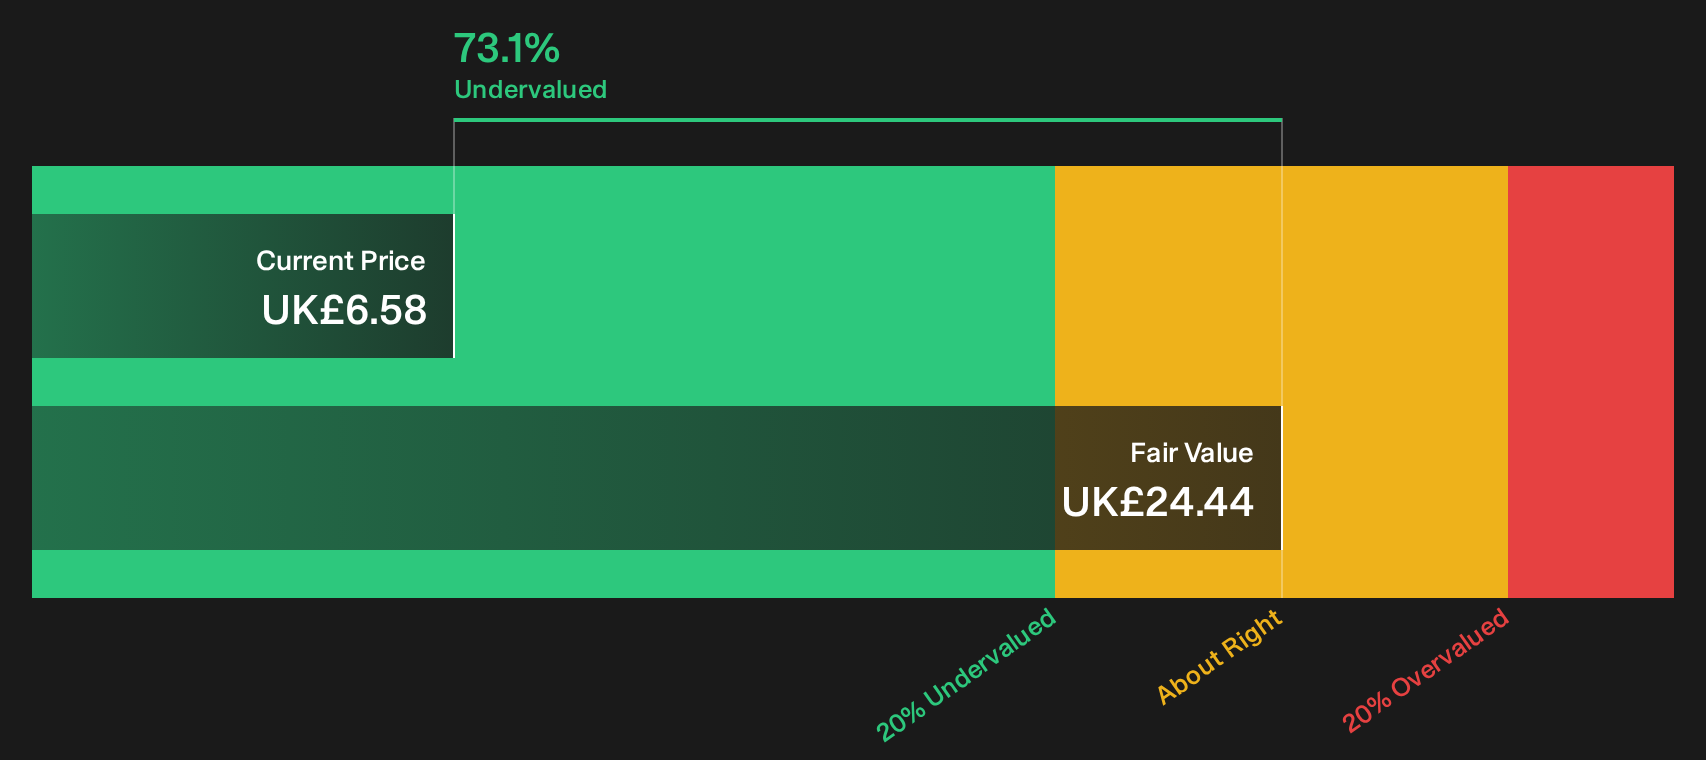
That cash flow question is exactly where the full narrative for James Fisher and Sons shows how James Fisher and Sons could turn contract phasing risk into an accelerating recovery story.

Irish Continental Group (LSE:ICGC)
Irish Continental Group runs ferries and container services that directly link into the UK and European ports and freight infrastructure spotlighted by the ABP stake sale. It generated about €497 million from Ferries and €253 million from Container and Terminal operations, and the stock is valued at roughly £976 million.
Irish Continental Group gives you direct exposure to short sea freight and passenger flows between Ireland, the UK and mainland Europe. Its port linked ferry routes and container terminals convert infrastructure demand into revenue. Earnings growth, high ROE and high quality earnings create an appealing profile for this screener, depending on how one unseen pressure on its leveraged balance sheet plays out.
That unseen pressure on Irish Continental Group’s balance sheet is exactly what the Irish Continental Group financial health report could be masking or amplifying for freight focused investors.
Seeking Fresh Alternatives Before They Fly
Fresh ideas move first. By the time a breakout hits the headlines, the best entry often slipped away. Scan curated lists that are under the radar for now and act while they remain less noticed.
- Target steadier compounding potential with a curated list of solid balance sheet and fundamentals (9 results) that helps you focus on businesses built to handle pressure while weaker peers are still dropping.
- Consider structural momentum as capital chases 55 AI infrastructure stocks supporting data centers and computing demand, before prices fully reflect where the cash is heading.
- Hunt for quiet upside in 5 high quality undiscovered gems that larger funds may not touch yet, then reassess once the crowd finally catches on.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com