


Triumph Financial (TFIN) Earnings Optimism Puts Fair Value Back In Focus
Triumph Financial (TFIN) heads into its Q3 2026 earnings release on October 21 after the market close, with investors focused on the sharp year over year shift in projected profitability.
Recent trading in Triumph Financial reflects this optimism in fits and starts, with a 1 day share price return of 1.27% but a 90 day share price decline of 23.26% from the current US$62.22 level, while the 1 year total shareholder return of 3.63% points to modest long term progress as investors reassess both earnings power and risk.
Scan how Triumph Financial compares with a hand picked 34 high quality undervalued stocks that are also drawing attention ahead of earnings resets and sentiment shifts.
Triumph Financial has slid hard into this print yet still carries fresh optimism on earnings power. Is that recent drop already a fair entry, or does patience for a cheaper setup make more sense as valuation comes into focus?
Most Popular Narrative: 17% Undervalued
Triumph Financial's most followed narrative estimates fair value at $75 versus the last close at $62.22. This focuses sentiment on whether freight focused fee income can account for a larger portion of earnings than traditional banking.
The continued shift in mix from traditional banking toward higher margin fintech and intelligence offerings, which are expected to represent a greater share of Triumph Financial’s revenue base, supports a higher contribution from fee income and potentially stronger returns on assets. Expansion of Triumph Financial’s data and decision support tools such as the Intelligence offerings and RFP Manager, built on a large brokered freight dataset, provides opportunities to grow subscription and analytics revenue and support a second leg of earnings contribution beyond core financial services.
See why 2 investors see Triumph Financial as 17% undervalued.
Result: Fair Value of $75 (UNDERVALUED)
Still, Triumph Financial faces clear pressure points, including weaker core banking revenue and flat Intelligence segment trends that could undermine the higher margin fee income story.
Find out about the key risks to this Triumph Financial narrative.
Another View: Triumph Financial Looks Expensive On Earnings
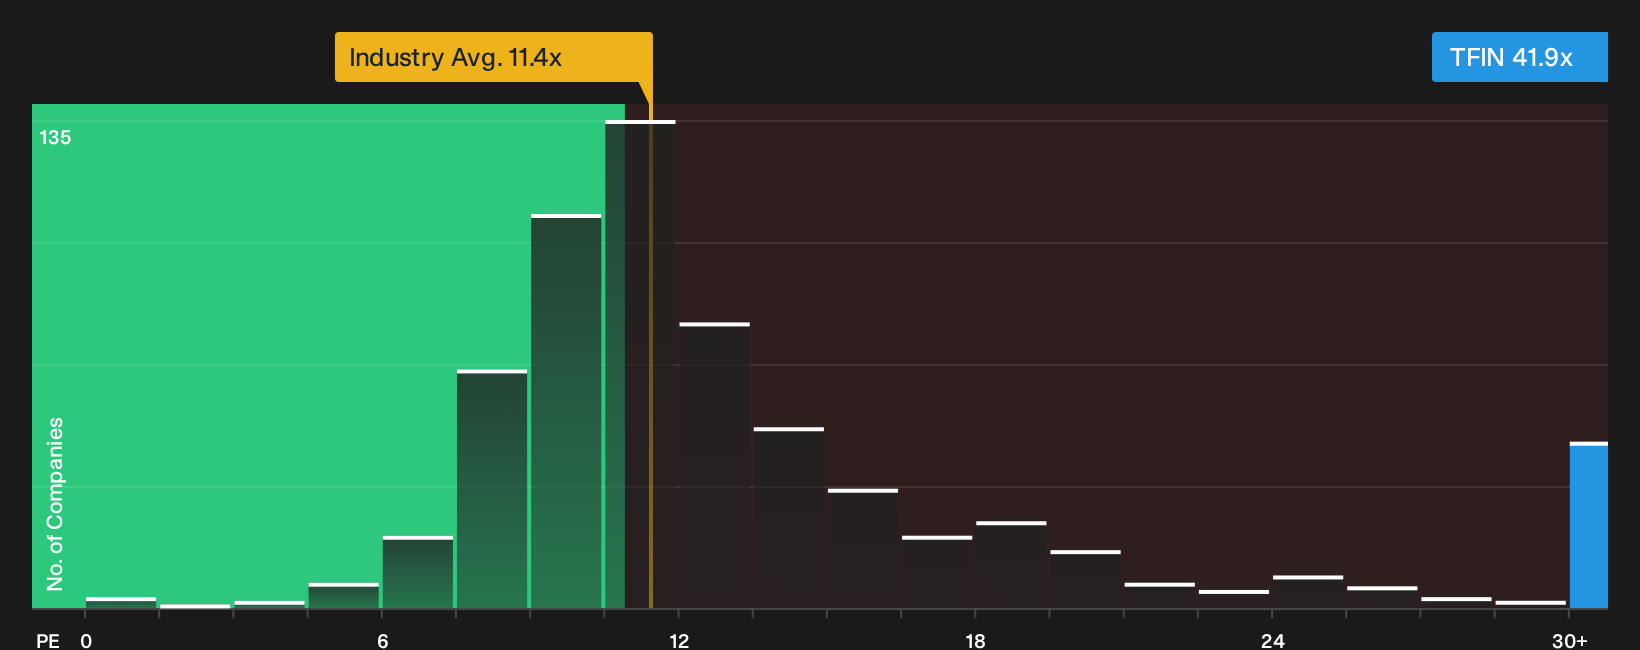
The first narrative paints Triumph Financial as undervalued on its future earnings power. A simple P/E check tells a different story. The stock trades at 41.9x earnings versus a fair ratio of 19.7x, and against 11.4x for US banks and 13.3x for peers, which points to meaningful valuation risk if expectations cool.
For a closer look at how this pricing gap could resolve, including what a move toward the fair ratio might mean for future returns, See what the numbers say about this price — find out in our valuation breakdown..
That context can help you judge whether Triumph Financial is being valued more like a premium fintech or an overextended bank, and whether that premium still feels justified once you see the earnings multiples side by side,
Next Steps
Mixed signals on Triumph Financial's setup can be confusing, so consider quickly reviewing the full picture of both risk and potential upside through 3 key rewards and 3 important warning signs.
Looking for more Triumph Financial sized ideas?
If Triumph Financial has your attention, do not stop here. Use the screener to quickly surface fresh opportunities before others start paying attention.
- Target resilient income by scanning for companies that resemble defensible cash generators and offer steady payouts through the 8 dividend fortresses.
- Hunt for mispriced opportunities where quality and valuation align tightly using the 34 high quality undervalued stocks.
- Prioritise capital preservation by filtering for stocks with stronger balance sheets and healthier fundamentals through the list of solid balance sheet and fundamentals (25 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com