


Globalstar (GSAT) FCC Approval Puts Its Valuation Narrative To The Test
Globalstar (GSAT) is back in focus after the US Federal Communications Commission granted nationwide authority for its third generation C-3 mobile satellite system, clearing the way for broad direct to device smartphone connectivity.
Against this regulatory backdrop, Globalstar’s momentum has been building, with the share price delivering a 30.11% year to date return and contributing to an 87.14% 1 year total shareholder return and a very large 3 year total shareholder return. This reflects how investors have been reassessing both growth potential and risk as the C 3 system moves closer to commercial reality.
Scan Globalstar’s peers riding similar direct to device and satellite connectivity momentum by exploring our hand picked 55 AI infrastructure stocks for potential next candidates on your watchlist.
The recent surge puts Globalstar in a very different place than it was a year ago. The live question now is whether that repricing has captured most of the opportunity or still leaves meaningful upside on the table once valuation is unpacked.
Most Popular Narrative: 7% Undervalued
Globalstar’s most followed valuation storyline pegs fair value at $90 per share, a touch above the recent $83.26 close, so the market is already pricing in much of the expected upside but not all of it.
Ongoing upgrades to ground infrastructure and the deployment of next-generation satellites (C-3 system and new launches with SpaceX) will boost network capacity, reach, and performance, enabling Globalstar to meet rising demand for hybrid and direct-to-device solutions, thus supporting long-term service revenue and higher discretionary earnings.
See why 40 investors see Globalstar as 7% undervalued.
This narrative leans on a 7.108% discount rate and forecasts that Globalstar can grow revenue at about 13.1% a year while lifting net profit margin to roughly 15.7%. Those inputs feed into an expected earnings profile that supports a fair value of $90, which is modestly above where the stock last traded and implies some residual upside if the thesis plays out as modeled.
The same storyline assumes a very high future P/E multiple of 232.33x on projected 2029 earnings, far above the current 15.6x figure cited for the broader US Telecom industry. That gap highlights how much of the thesis rests on Globalstar successfully scaling its satellite network, monetizing spectrum assets and hitting profitability targets rather than merely keeping pace with sector averages.
Result: Fair Value of $90 (UNDERVALUED)
Still, Globalstar’s story can break the other way if capital intensive satellite projects strain cash flows, or if execution on the Amazon agreement slips against its milestones.
Find out about the key risks to this Globalstar narrative.
Another View: Multiples Paint Globalstar As Expensive
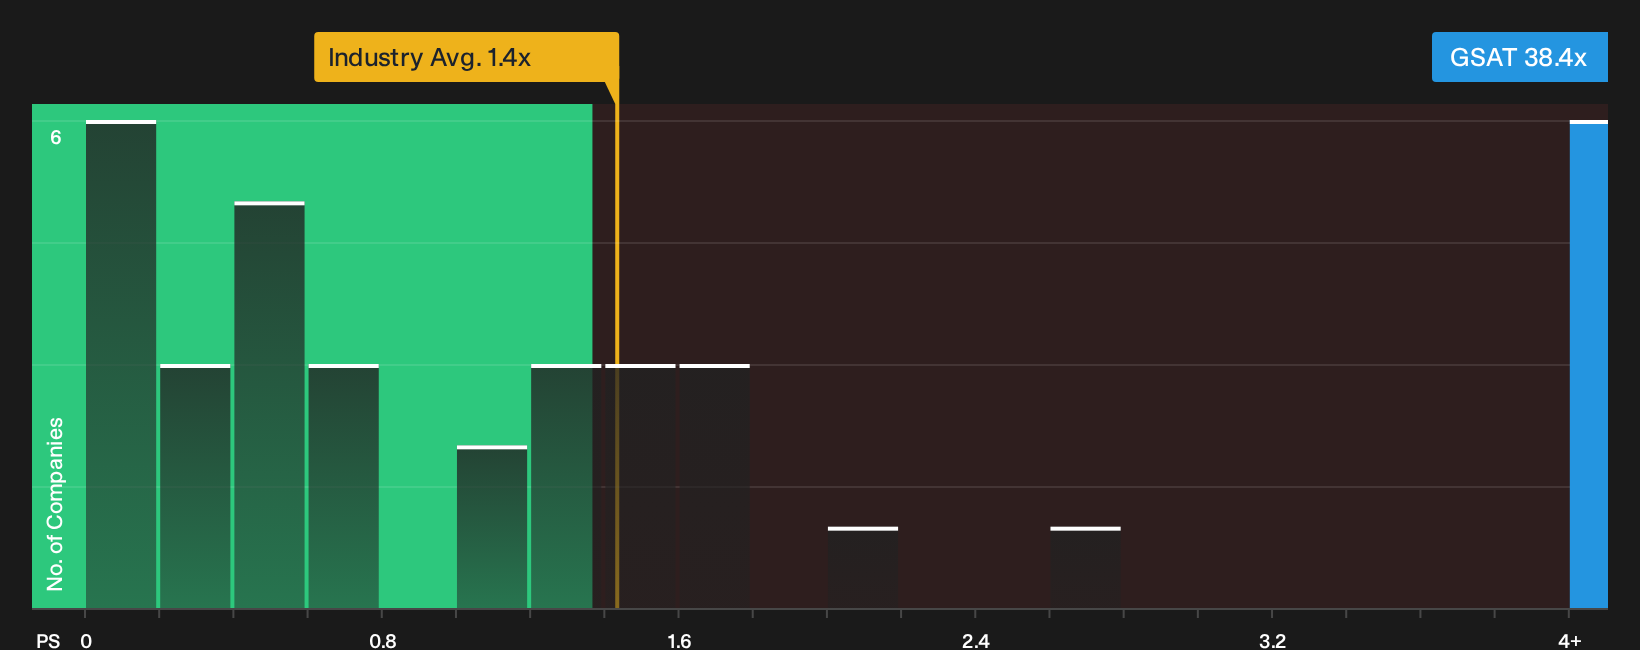
The narrative around Globalstar hinges on a fair value of $90, yet the current P/S of 38.4x sits far above both the US Telecom industry at 1.4x and a fair ratio of 2.6x. That gap signals rich expectations baked into the price, so how comfortable are you paying that kind of premium for growth that still needs to be earned?
For a closer look at how these valuation gaps show up in the numbers and what they could mean for risk, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed feelings about Globalstar’s current pricing and future path. If you want to move fast and rely on your own judgement, start by weighing its 1 key reward and 1 important warning sign.
Looking for more investment ideas beyond Globalstar?
If Globalstar has your attention, do not stop here. Use Simply Wall Street screeners to surface fresh opportunities that fit your style before others move first.
- Target potential value opportunities by reviewing companies in the 35 high quality undervalued stocks that pair quality fundamentals with prices that may not fully reflect them.
- Prioritize resilience by scanning the 32 resilient stocks with low risk scores focused on businesses with sturdier balance sheets and lower overall risk scores.
- Hunt for lesser known prospects through the 20 high quality undiscovered gems that highlights financially solid stocks still flying under most investors' radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com