


What UL Solutions Stock's Expanded Testing Capacity Means For Shareholders
- UL Solutions expanded its HVACR Center of Excellence in Plano, Texas, and introduced advanced testing and modeling services that support manufacturers developing energy efficient cooling and fire resistant building products.
- The combination of larger HVACR testing capacity and a new gypsum board simulation service deepens UL Solutions' role in helping customers manage regulatory complexity, product design risk and time to market.
- Next, the focus shifts to how UL Solutions' expanded HVACR testing capacity could influence the broader investment narrative around the business.
UL Solutions Investment Narrative Recap
To own UL Solutions, you need to believe its testing, inspection and certification platform can keep attracting complex, higher value work even as macro and regulatory cycles shift. The expanded HVACR Center of Excellence fits that view by concentrating more energy efficiency and data center cooling work in one hub. This could support the existing recurring certification base if demand for advanced equipment testing stays firm.
In the near term, the key swing factor is whether these capital intensive expansions translate into enough high margin projects to offset forecast earnings pressure and a higher effective tax rate. The main risk is that global product development or recertification activity slows, leaving UL Solutions with heavier fixed costs and softer revenue growth than expected.
The Plano HVACR expansion is the clearest link to current catalysts because it sits directly on top of the themes analysts are already watching, such as sustainable HVAC systems and growing computing infrastructure. This facility increases UL Solutions’ capacity to test heat pumps, chillers and data center cooling units under a wide range of conditions, which gives the business more ways to win complex testing mandates.
Execution still matters. Higher capex can weigh on free cash flow if volumes or pricing disappoint, and earnings forecasts already imply pressure over the next three years. For you as an investor, the practical question is whether this new HVACR capacity, paired with the global lab network, supports enough long run test and certification demand to justify UL Solutions’ current P/E premium to the wider professional services group.
UL Solutions' current revenue outlook reflects analyst assumptions of 6.1% yearly top line growth, with expectations that revenues reach about $3.8 billion and earnings come to roughly $492.1 million by 2029, compared with earnings of $506.0 million today. This implies an earnings decline of $13.9 million over that period.
Uncover why UL Solutions' fair value indicates a 35% potential upside to its current price that may not last much longer.
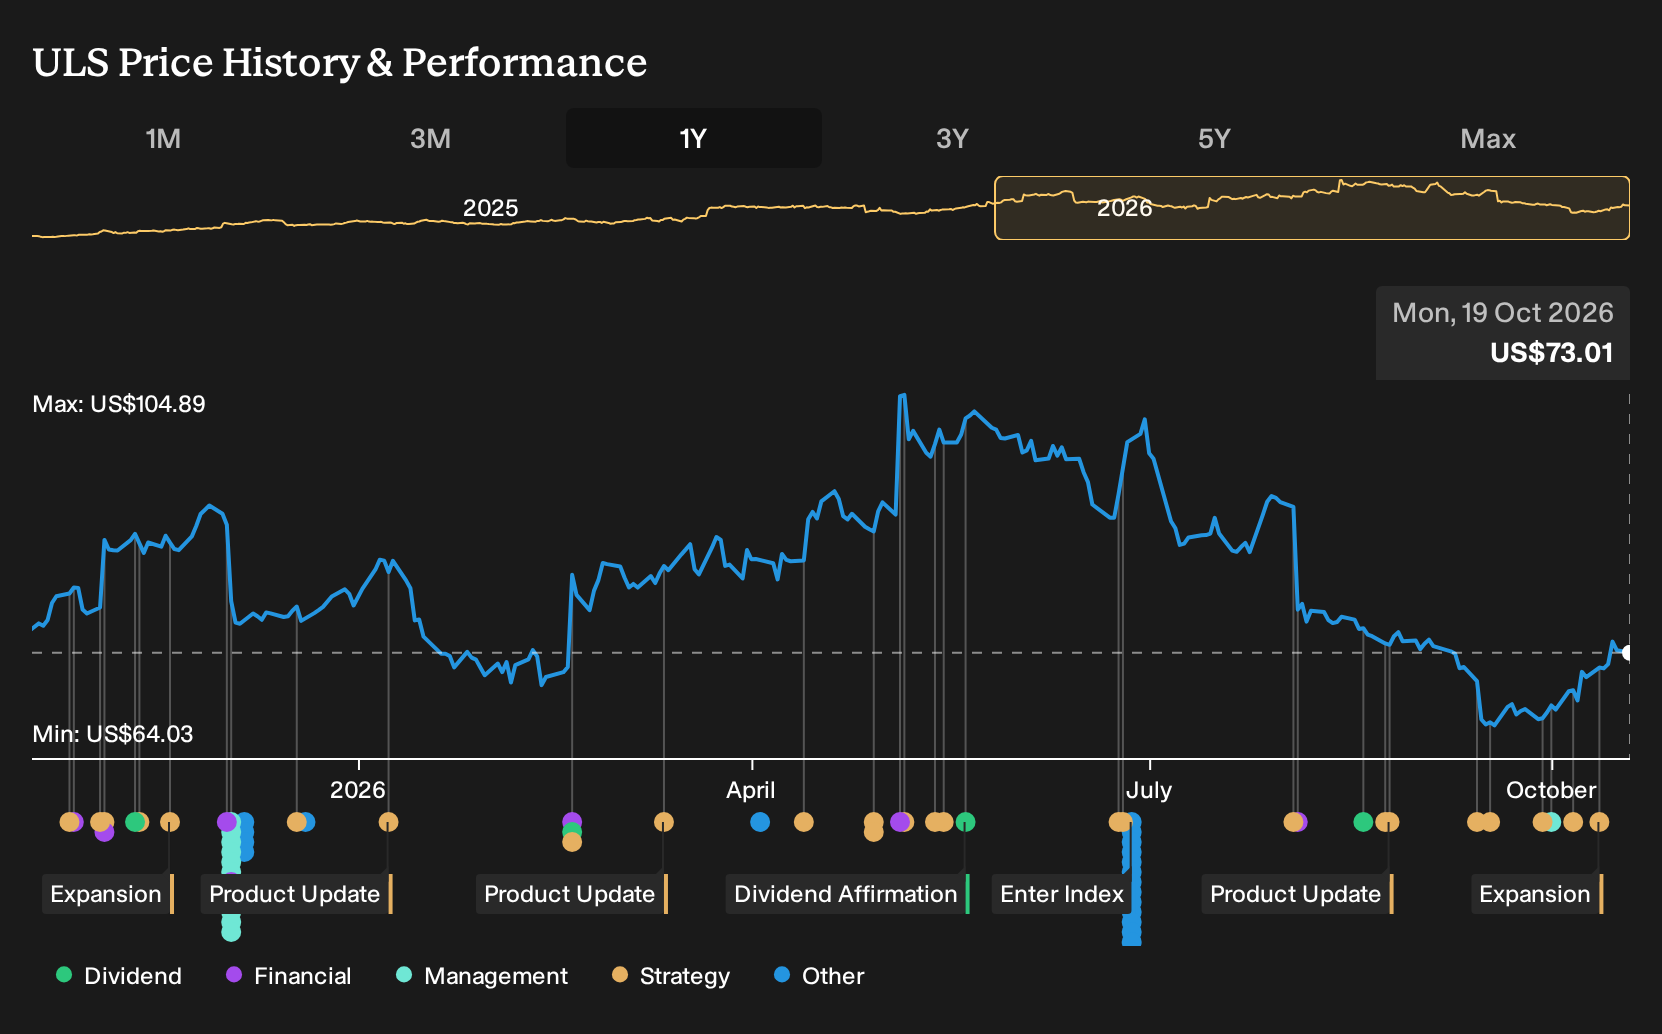
Exploring Other Perspectives
Some of the most optimistic analysts frame the Plano expansion as proof that UL Solutions can lean harder into energy transition and data center themes, which they already modeled as supporting about 8% yearly revenue growth to roughly US$4.0b and earnings of US$535.2m by 2029. You may see those views shift as this new capacity beds in, so it helps to compare several narratives before deciding how much weight to give this news.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own independent view.
- A great starting point for your UL Solutions research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for UL Solutions. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate UL Solutions' overall financial health at a glance.
Looking For More Investment Ideas Beyond UL Solutions?
Once you have a handle on UL Solutions, it can help to widen the lens and see which other listed businesses line up with the type of risk profile or income potential you want in your portfolio. The Simply Wall St screener is built for exactly that job and lets you filter by quality, valuation, financial strength and more in a few clicks.
- If you care most about finding resilient balance sheets and steady fundamentals, start with this curated list of solid balance sheet and fundamentals (25 results) that filters for companies with stronger financial footing.
- For investors hunting for mispriced opportunities, a focused 35 high quality undervalued stocks can surface stocks where fundamentals and current pricing appear out of sync.
- Income focused readers can scan a targeted 8 dividend fortresses to spot companies offering higher yields that may align with a long term payout approach.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com