


The Call ESCO Technologies Bulls Got Right
If ESCO Technologies sat on your watchlist instead of in your account, the outcome over this stretch may feel expensive. Holding ESCO Technologies from the start of the year would have returned 26.2%, including dividends. That kind of move invites a blunt question. Before the Megger deal headlines and fresh earnings coverage, what in the early electrification and grid modernization story could have signalled that recurring utility demand, not just aerospace backlog strength, might be the crucial assumption to test?
The move put ESCO Technologies in the middle of this trade. Scan 42 power grid technology and infrastructure stocks for other companies exposed to it.
The Argument You Would Have Been Weighing Up On ESCO Technologies
The shares cost US$195 at the start of the period, which left you choosing between two very different stories for ESCO Technologies.
The bullish view put a Fair Value of US$225, an implied upside based on its own assumptions about the future, on the stock and leaned on recurring utility demand. That case rested on revenue expanding 9.3% a year with profit margins reaching 13.2% and a future P/E of 36.6x as electrification and grid modernization supported recurring software and diagnostic sales.
The bearish narrative pinned Fair Value at US$168 and focused on cost friction. It assumed 10.6% annual revenue growth and a 13.3% margin, yet argued that rising supply chain and regulatory expenses, plus exposure to government contracts, could leave a future P/E closer to 26.4x.
What The Results Changed For ESCO Technologies
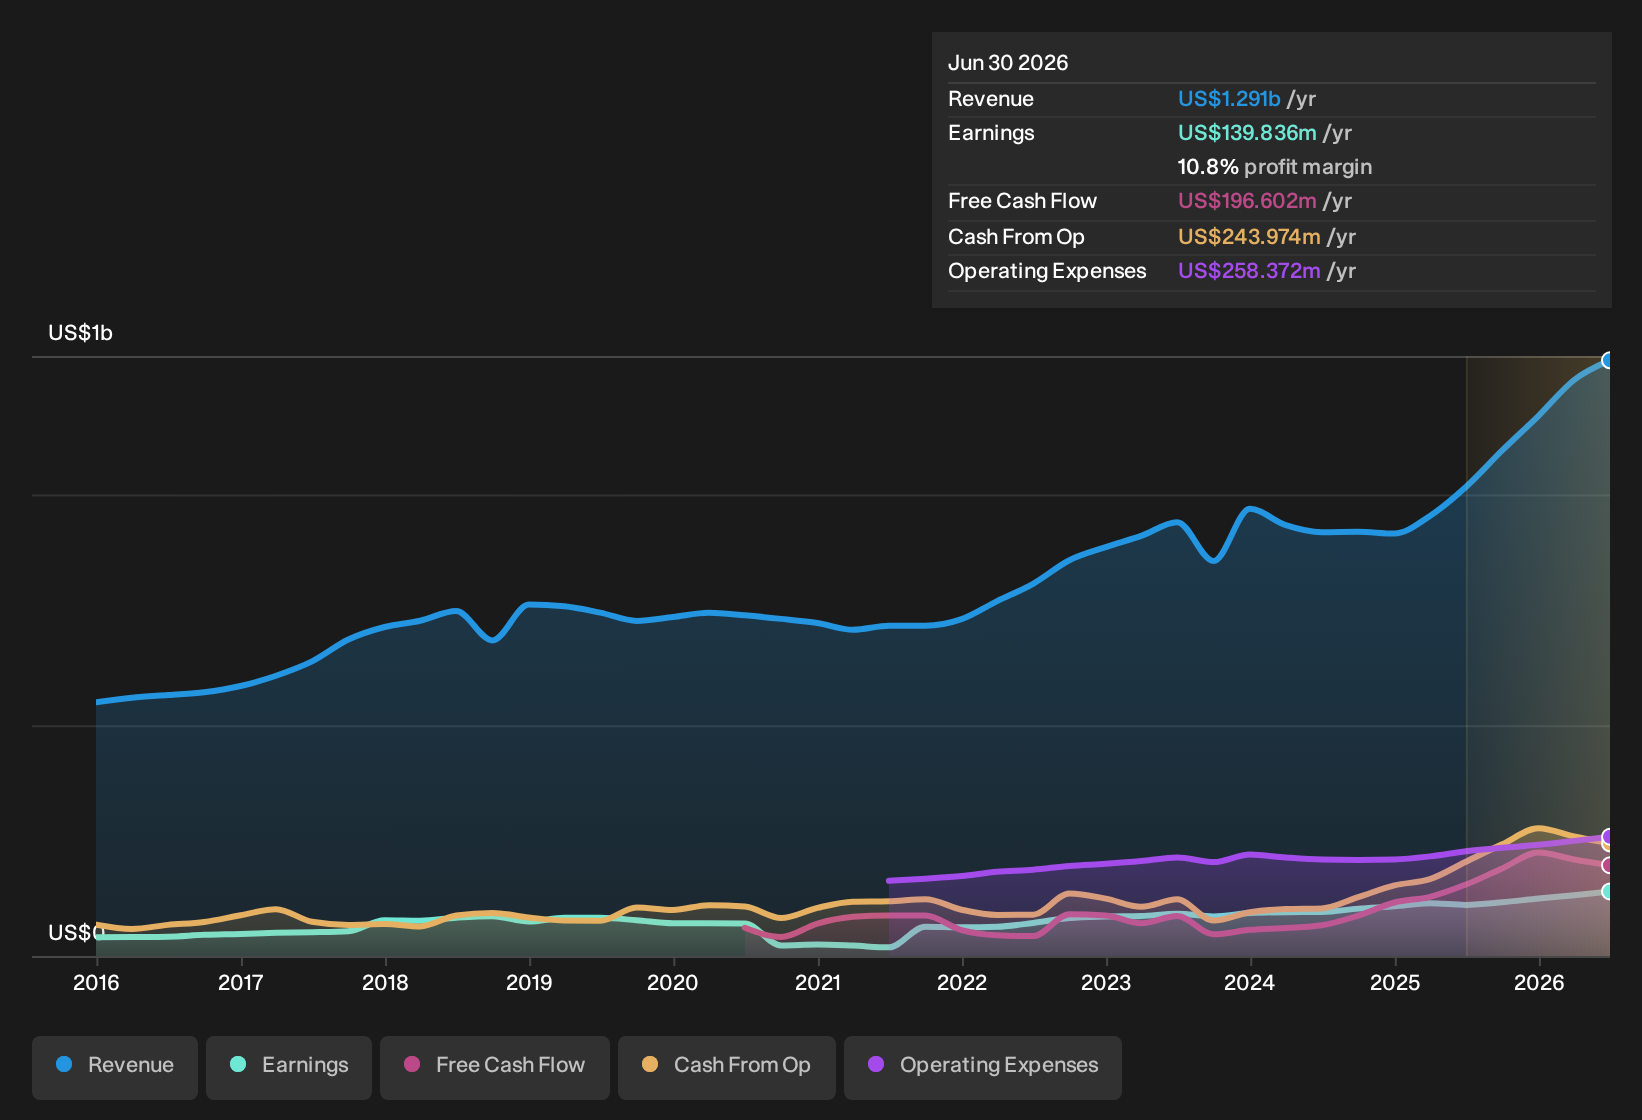
The Megger acquisition agreement and new US$1.5b credit facilities gave ESCO Technologies fresh support for the bullish view that recurring utility demand could scale, while the larger balance sheet pointed to a more cautious stance on cost and leverage. Q3 2026 revenue of US$339.0m and net income of US$32.7m were higher than Q3 2025, and net margin improved to 9.7%. The evidence supported both interpretations.
The useful takeaway is clear. When an investment thesis leans on recurring infrastructure demand, track order backlog, segment mix and margin direction in each report, then decide whether the higher capital commitment still matches your tolerance for balance sheet risk.
What ESCO Technologies' Run Up 26% Now Prices In
Today ESCO Technologies trades at US$249, with the selected Narrative arguing that its Fair Value still sits above that level based on current backlog and execution assumptions.
The Narrative focuses on how effectively ESCO turns long cycle aerospace, naval, grid and Megger related orders into earnings, and argues that today’s price still does not fully credit successful execution on that conversion and integration.
"Despite ESCO Technologies reporting record backlog and a book to bill comfortably above 1.0, the recent quarter where revenue of US$309.3 million grew 33.5% yet still fell about 3.4% short of expectations suggests execution or timing risk on long cycle aerospace, naval and grid programs that could leave future revenue and earnings below what the current backlog implies."
One Narrative disagrees with today's price. → See where this Narrative says ESCO Technologies should trade
Where ESCO’s Theme Connects Next
ESCO shows how critical infrastructure spending can hinge on reliability, not hype. You can also look one step away from grids.
Every AI data hall and trading system depends on power that stays clean and cool. That need does not disappear when workloads spike.
Another business designs the hardware and services that keep those facilities powered, cooled and continuously running. Its gear helps operators keep digital infrastructure available when demand is heaviest.
As more workloads move into dense data centers, the role of that quiet infrastructure layer can change. At some point, reliability itself starts to look like the scarce resource.
One Narrative has already put a figure on it. → Uncover the company trading 49% below one Narrative's Fair Value
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com