


Exploring 3 Undervalued Small Caps With Insider Action Across Regions
Over the last 7 days, the United States market has experienced a 2.6% decline, although it has risen by 11% over the past year with earnings forecasted to grow by 17% annually. In this context, identifying small-cap stocks that are potentially undervalued and have notable insider activity can offer intriguing opportunities for investors seeking to capitalize on these market dynamics.
Top 10 Undervalued Small Caps With Insider Buying In The United States
| Name | PE | PS | Discount to Fair Value | Value Rating |
|---|---|---|---|---|
| Regional Management | 6.8x | 0.5x | 28.45% | ★★★★★★ |
| Enovis | NA | 0.5x | 41.39% | ★★★★★☆ |
| Bank of Marin Bancorp | NA | 7.0x | 34.72% | ★★★★☆☆ |
| Bank of the James Financial Group | 10.6x | 2.4x | 28.39% | ★★★★☆☆ |
| Tilray Brands | NA | 0.5x | 9.19% | ★★★★☆☆ |
| German American Bancorp | 13.2x | 4.9x | 25.30% | ★★★☆☆☆ |
| Franklin Financial Services | 11.5x | 3.1x | -43.14% | ★★★☆☆☆ |
| Citizens Community Bancorp | 16.0x | 3.5x | 11.03% | ★★★☆☆☆ |
| New Peoples Bankshares | 9.5x | 2.6x | 8.21% | ★★★☆☆☆ |
| Orion Group Holdings | 95.8x | 0.4x | 48.94% | ★★★☆☆☆ |
Here's a peek at a few of the choices from the screener.
Caledonia Mining (CMCL)
Simply Wall St Value Rating: ★★★★☆☆
Overview: Caledonia Mining is a mining company primarily focused on the Blanket gold mine in Zimbabwe, with additional operations in South Africa and the Bilboes Oxide Mine, and it has a market capitalization of approximately $200 million.
Operations: The primary revenue stream for Caledonia Mining is from its Blanket operations, contributing significantly to the company's total income. The cost of goods sold (COGS) has been a substantial expense, impacting the gross profit margin which reached 60.19% in recent periods. Operating expenses and non-operating expenses also play a role in determining net income margins, which have shown variability over time.
PE: 7.0x
Caledonia Mining, a smaller U.S.-based company, shows potential despite recent challenges. Their Q3 2026 gold production dipped to 17,030 ounces from the previous year's 19,106 ounces. However, insider confidence is evident with significant share purchases in recent months. The maiden resource estimate at Motapa reveals promising mineralization near their Bilboes project. Despite reduced full-year guidance due to lower-than-expected Q4 output, future synergies and exploration prospects offer growth opportunities for this undervalued player in the industry.
- Click here and access our complete valuation analysis report to understand the dynamics of Caledonia Mining.
Assess Caledonia Mining's past performance with our detailed historical performance reports.
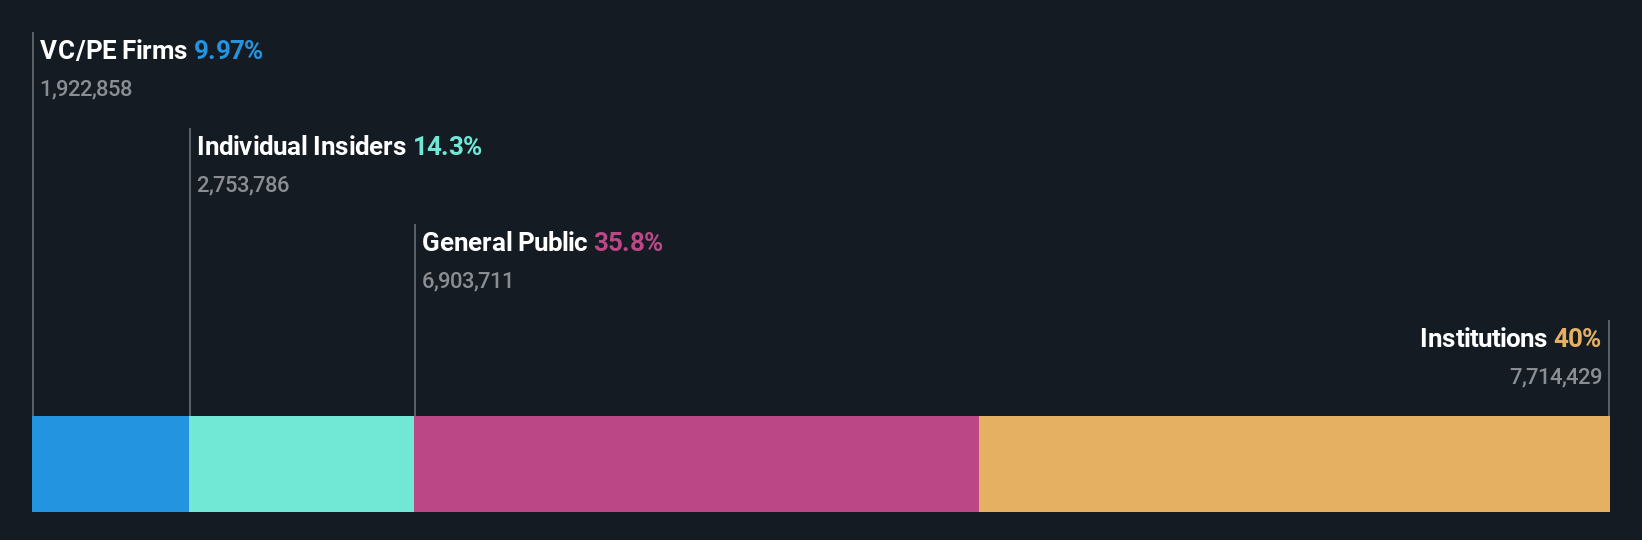
Colony Bankcorp (CBAN)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: Colony Bankcorp operates as a financial institution with divisions in banking, mortgage banking, and small business specialty lending, and has a market capitalization of approximately $0.16 billion.
Operations: The company's revenue is primarily derived from its Banking Division, with additional contributions from the Mortgage Banking and Small Business Specialty Lending Divisions. Operating expenses have shown a noticeable increase over time, impacting net income margins, which reached 22.50% in the latest available period.
PE: 12.8x
Colony Bankcorp, a player in the regional banking sector, recently joined the S&P Regional Banks Select Industry Index, signaling increased recognition. Their net interest income surged to US$29.87 million for Q2 2026 from US$22.39 million the previous year, reflecting strong financial health. Insider confidence is evident as Edward Canup acquired 4,000 shares worth US$86,500 in early 2026. Despite past shareholder dilution concerns and upcoming merger discussions with First Reliance Bancshares, growth prospects remain compelling with earnings projected to rise by 33.84% annually.
- Unlock comprehensive insights into our analysis of Colony Bankcorp stock in this valuation report.
Evaluate Colony Bankcorp's historical performance by accessing our past performance report.
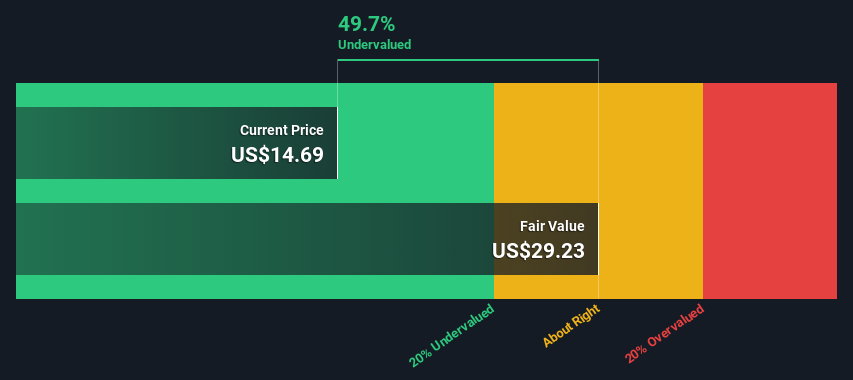
Ethan Allen Interiors (ETD)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: Ethan Allen Interiors is a company specializing in the design, manufacture, and retail of home furnishings and accessories, with a market cap of approximately $0.9 billion.
Operations: Ethan Allen Interiors generates revenue primarily through its Retail and Wholesale segments, with retail contributing $511.20 million and wholesale $330.70 million. The company's gross profit margin has shown variation, reaching 61.22% in recent periods, reflecting the relationship between revenue and cost of goods sold over time.
PE: 12.7x
Ethan Allen Interiors, a company with a rich 90-year heritage, is navigating through significant investor activism. DGB Investment is advocating for board changes, citing two decades of declining revenue and shareholder value. The company's earnings are projected to decline by 11.7% annually over the next three years due to reliance on external borrowing as its sole funding source. Despite these challenges, Ethan Allen's recent opening of a new design center in Aventura shows commitment to expanding customer engagement and enhancing retail experiences.
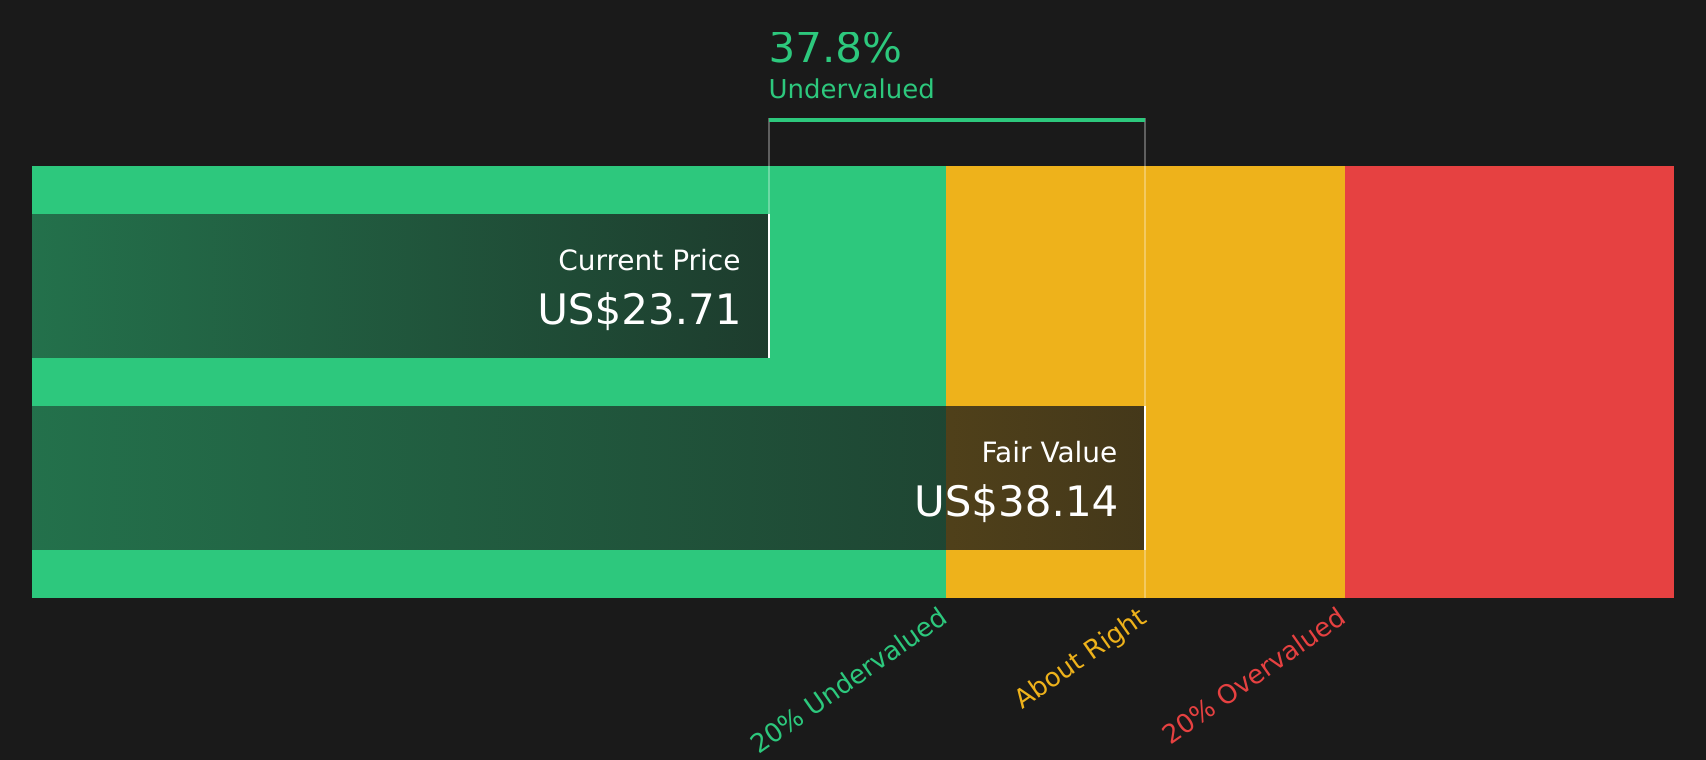
Make It Happen
- Delve into our full catalog of 68 Undervalued US Small Caps With Insider Buying here.
- Are any of these part of your asset mix? Tap into the analytical power of Simply Wall St's portfolio to get a 360-degree view on how they're shaping up.
- Elevate your portfolio with Simply Wall St, the ultimate app for investors seeking global market coverage.
Curious About Other Options?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com