


Is NOF (TSE:4403) Fairly Valued Following Its Recent Share Price Rebound?
NOF (TSE:4403) has caught investor attention after a recent price move, with the stock showing double digit returns over the past week and month, while its year to date performance remains lower.
The recent 1-day share price return of 6.17% and 7-day gain of 10.54% suggest momentum is building for NOF, even though the year to date share price return is down 5.58% and the 1-year total shareholder return of 10.65% points to steadier longer term progress.
Scan how NOF compares with other materials businesses showing fresh momentum and solid fundamentals in our hand picked 73 high quality undiscovered gems list.
NOF now trades at a sizeable discount to both analyst targets and an estimated intrinsic value, even after this sharp rebound. Is the market fairly cautious, or has the recent move only begun to close the gap?
Price-to-Earnings of 16x: Is it justified for NOF?
On earnings, NOF trades on a P/E of 16x, which prices the stock above both the Japanese chemicals average of 13x and an estimated fair P/E of 14.8x, even though it is below the peer group average of 20.7x.
The P/E ratio compares the current share price with per share earnings and gives a quick sense of how much investors are paying for each ¥ of profit. For a diversified chemicals group like NOF, this yardstick helps you gauge how the market is weighing forecast growth against current profitability and sector risks.
With earnings forecast to grow about 5% per year while the broader JP market is projected at 9.5%, a 16x P/E means investors are paying a higher multiple than the modelled fair level of 14.8x. That fair ratio points to a level the market could eventually move toward if sentiment around NOF's growth and returns on equity stays close to current expectations.
Relative to the JP chemicals industry on 13x, NOF changes hands at a clearly richer valuation, which suggests the market is assigning a premium for its profile. Against closer peers on 20.7x, the stock screens as cheaper, so investors comparing within the peer set might still see the current tag as more measured than the wider chemicals basket implies.
Explore the SWS fair ratio for NOF.
Result: Price-to-Earnings of 16x (OVERVALUED).
Still, softer revenue growth of 2.7% and the year to date share price decline of 5.6% could quickly challenge the recent optimism around NOF.
Find out about the key risks to this NOF narrative.
Another View: What NOF's Cash Flows Suggest
The P/E framework flags NOF as slightly expensive, yet the SWS DCF model points in the opposite direction. At ¥2,832.5, the shares trade about 19.9% below an estimated future cash flow value of ¥3,538.13, which frames the recent rebound as potentially still short of what its cash generation might support.
That gap can cut both ways for investors, since it either reflects an opening created by weak sentiment or a market that is unconvinced the forecast cash flows will fully materialise.
Look into how the SWS DCF model arrives at its fair value.
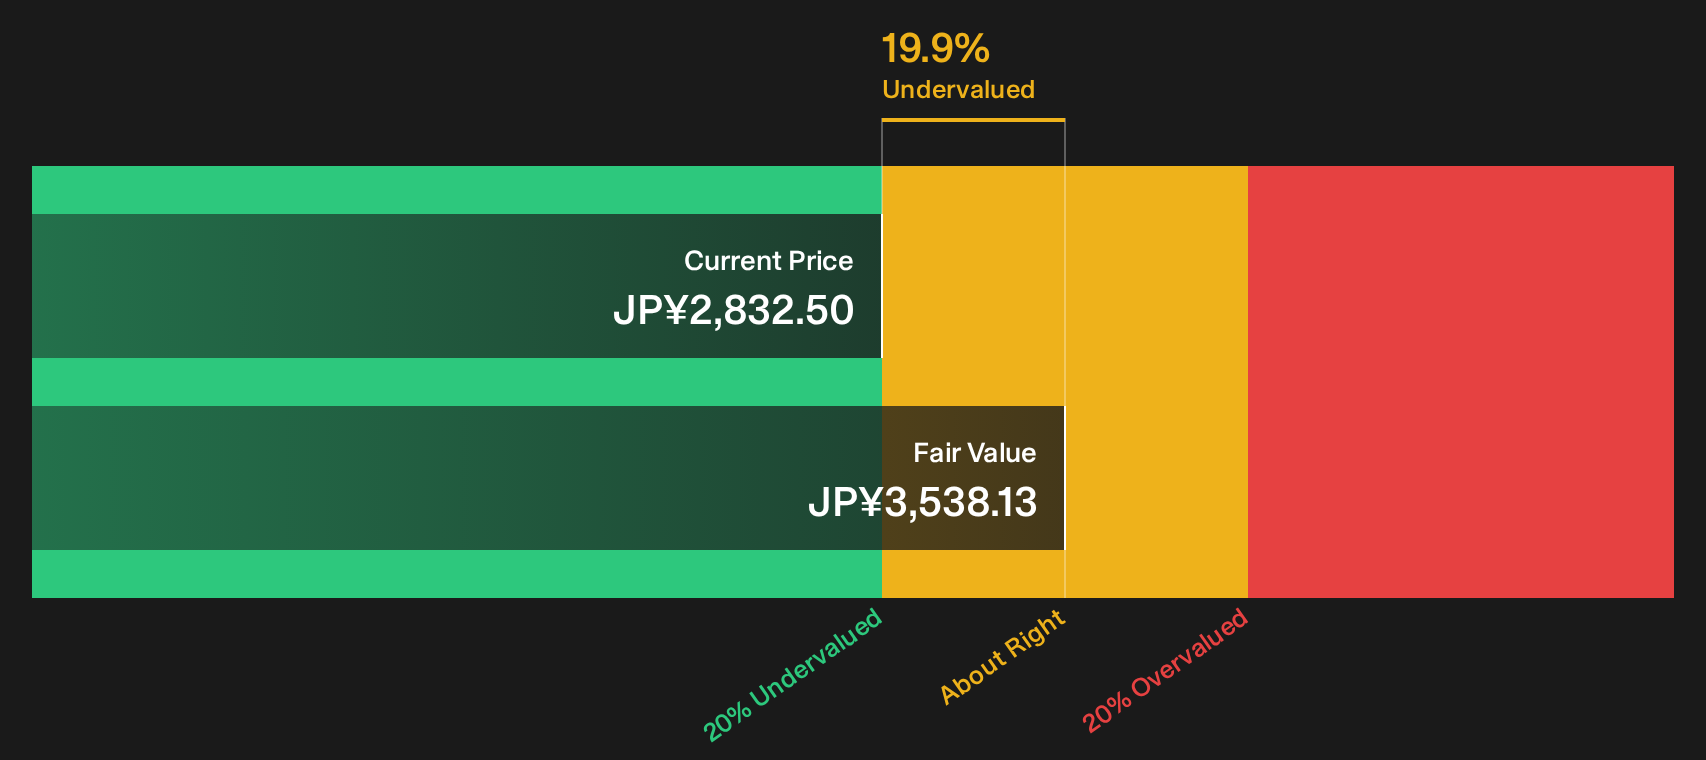
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out NOF for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 13 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Feeling that the NOF story could go either way based on these signals. Act while the data is fresh and review the company's 5 key rewards.
Looking for more investment ideas beyond NOF?
If NOF has your attention, do not stop there. Broaden your watchlist now so you are not relying on a single opportunity.
- Target stronger upside potential by focusing on high quality companies trading below estimated value through our 13 high quality undervalued stocks.
- Strengthen portfolio resilience by concentrating on businesses with healthier finances using the list of solid balance sheet and fundamentals (22 results).
- Build a steadier income stream by zeroing in on companies offering higher yields through our 29 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com