


Why Did Challenger (ASX:CGF) Move Today?
Challenger (ASX:CGF) has been in focus after its on market share buyback and cancellation program, together with new retirement income regulations that support wider use of its lifetime income products.
At A$9.85, Challenger’s recent share price has eased over the past month and quarter, even though the 1-year total shareholder return of 15.03% and 3-year total shareholder return of 83.91% point to momentum that has built over a longer stretch.
Scan how Challenger compares to other financials reshaping retirement income and capital returns by reviewing our hand picked list of 5 high quality undervalued stocks.
After a strong multi year run and a recent pullback to A$9.85, the question around Challenger now is simple. Is the meaningful upside still in front of holders, or has most of it already played out in the price?
Most Popular Narrative: 4.5% Undervalued
On the most followed view, Challenger’s A$10.32 fair value sits modestly above the A$9.85 last close. This frames a gap that hinges on how retirement income tailwinds and execution risks play out over time.
The expected APRA capital standard reforms are set to meaningfully reduce capital intensity and volatility, lowering Challenger's cost of capital and enabling greater flexibility to grow its annuity business, which should support higher earnings and potential increases in ROE.
Aging demographics and the continued expansion of the retirement phase in superannuation are driving robust, long-term demand for retirement income products, expanding Challenger's addressable market and supporting future revenue growth.
See why 15 investors see Challenger as 5% undervalued.
Result: Fair Value of A$10.32 (UNDERVALUED)
Still, the narrative around Challenger can be knocked off course if annuity roll offs outpace new inflows, or if delays in digital transformation keep costs higher for longer.
Find out about the key risks to this Challenger narrative.
Another View On Challenger’s Valuation
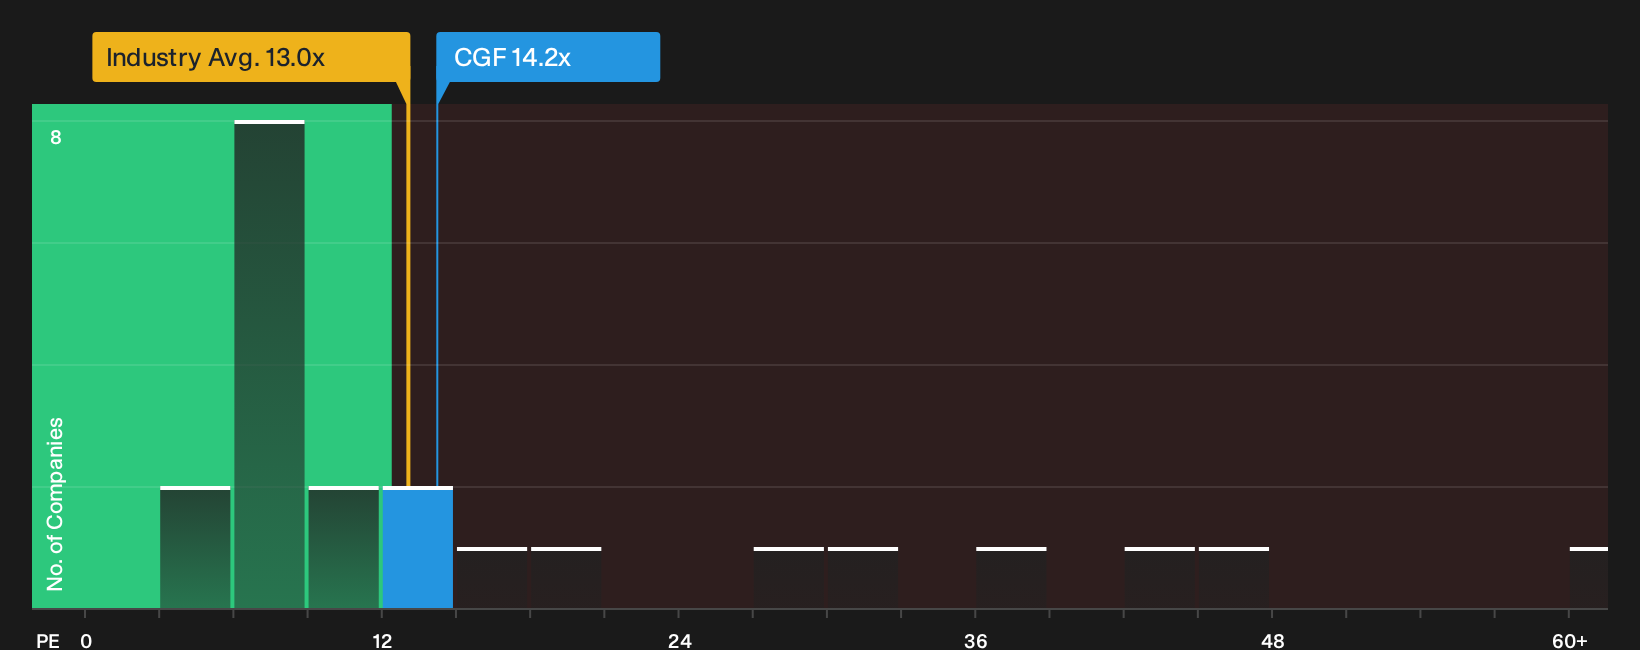
On simple earnings multiples, Challenger looks mixed. The stock trades on a P/E of 14.2x, which is higher than the global diversified financials average of 13x, yet well below the peer group near 32.1x and under a fair ratio of 16.4x that the market could move toward. Is that a safety margin or a sign investors are still cautious?
To see how those P/E gaps could matter for your risk and return trade off, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed sentiment around Challenger’s valuation and business risks does not need to leave you on the fence. Act while the details are fresh and weigh both sides by reviewing 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Challenger?
If you stop with Challenger, you miss a wider field of opportunities. Let the Simply Wall Street Screener surface fresh angles while you stay focused on decisions.
- Target potential upside by reviewing companies that combine quality fundamentals with attractive pricing through the 15 high quality undiscovered gems.
- Prioritise resilience and seek out businesses with stronger financial foundations using the list of solid balance sheet and fundamentals (12 results).
- Dial down portfolio stress and focus on steadier profiles by screening for 6 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com