


Targa Resources (TRGP) Raises Its Dividend, Is The Stock Priced For Perfection?
Targa Resources (TRGP) set its next cash payout in motion after the board declared a quarterly dividend of $1.25 per share for the third quarter of 2026, payable on November 17.
The dividend decision lands after a strong run in Targa Resources’ shares, with a 1-day share price return of 4.37% taking the stock to $294.90 and adding to a 57.89% year-to-date share price return and a very large 5-year total shareholder return of 483.01%. This suggests that investors have been steadily repricing both its income stream and business risk profile.
Scan how Targa Resources compares with other income and infrastructure plays by running through our hand picked 8 dividend fortresses alongside this latest dividend move.
After a sharp run and a richer dividend, believers see Targa Resources as a resilient cash generator, while skeptics see a midstream stock priced for perfection. Which case does the valuation math lean toward next?
Most Popular Narrative: 9% Undervalued
On the most followed view, Targa Resources screens as modestly undervalued, with a narrative fair value of $325.14 against a last close of $294.90. This puts the focus on whether its long project slate and contracts justify that gap.
An expanding set of long dated growth projects, including the Speedway NGL system with initial 500,000 barrels per day of capacity, multiple Permian gas plants scheduled through early 2028, a 20 year processing and downstream volume agreement with a large producer and a 230 megawatt behind the meter power deal to support Permian processing, collectively increases Targa’s potential share of basin volumes and can support higher revenue and adjusted EBITDA over time.
See why 18 investors see Targa Resources as 9% undervalued.
Result: Fair Value of $325.14 (UNDERVALUED)
Still, the whole story can change if Permian buildout runs ahead of NGL and LPG demand, or if heavy project spending drags on free cash flow.
Find out about the key risks to this Targa Resources narrative.
Another View: Targa Resources Through The P/E Lens
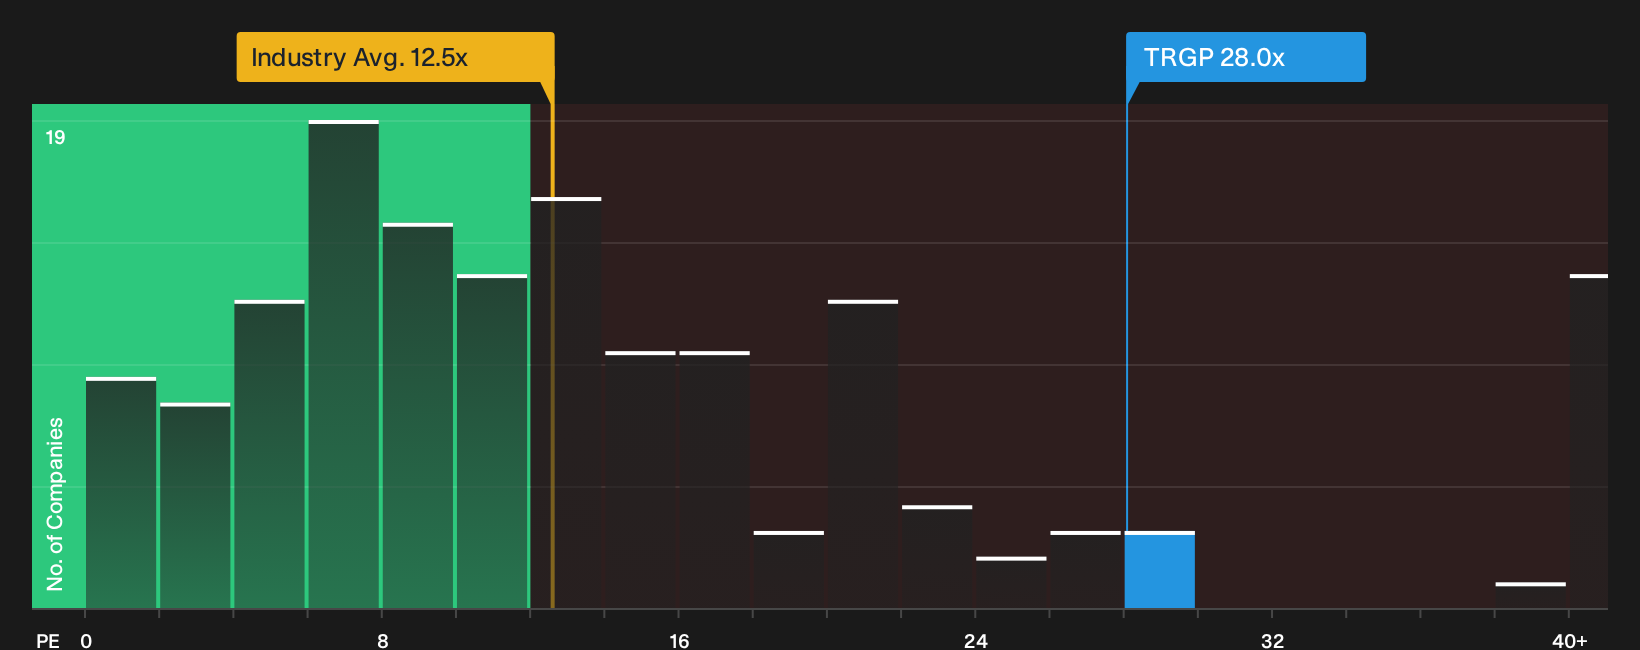
The SWS DCF model points to Targa Resources trading well below an estimated future cash flow value of $541.37, yet the market is already assigning a rich 28x P/E multiple. That is more than double the US Oil and Gas sector on 12.5x, and it is also above both peers at 17.3x and a fair ratio of 22.9x. This raises the question of whether investors are being paid enough for the valuation risk.
See what the numbers say about this price in the valuation breakdown, starting with the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Conflicted about what Targa Resources’ recent run and valuation signals really say? Act while the information is fresh and weigh both sides with the 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Targa Resources?
If Targa Resources has you rethinking what is possible from a single holding, do not stop there. The next opportunity might sit just one screen away.
- Spot overlooked potential by scanning 20 high quality undiscovered gems, which combine solid fundamentals with stories the wider market has not fully priced in yet.
- Focus on resilience by checking 32 resilient stocks with low risk scores, which score well on financial strength so short term volatility does not dominate your portfolio.
- Target quality at a discount through the 33 high quality undervalued stocks, which filter for strong businesses trading below their assessed worth.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com