


Should Council Expansion Require Action From Hancock Whitney Stock Investors?
- Hancock Whitney recently refreshed its Community Development Advisory Council, adding 19 housing, small business, economic development, and media leaders from across the Gulf South to advise on financial and economic health initiatives.
- The mix of council members from organizations such as NAREB, LISC Jacksonville, United Way of Acadiana, and multiple regional housing groups could sharpen how Hancock Whitney targets affordable housing, small business support, and broader community investment programs.
- We will now examine how Hancock Whitney's investment narrative could be influenced by this broader Community Development Advisory Council membership.
Hancock Whitney Investment Narrative Recap
To own Hancock Whitney, you need to be comfortable with a regional bank that is leaning on hired revenue producers, new markets in Texas and Florida, and balance sheet repricing to support future earnings. The short term swing factor is whether those 42 new bankers and the One Florida Bank integration translate into steady loan and fee volumes without straining credit quality.
The biggest near term risk is that recent revenue and profit declines, along with weaker efficiency metrics, signal deeper operating issues that do not heal quickly even as management reprices assets and trims costs. The expanded Community Development Advisory Council looks directionally positive for outreach, but it does not materially shift that core earnings and efficiency equation in the near term.
The refreshed Community Development Advisory Council is the clearest recent move that connects directly to Hancock Whitney’s growth and risk profile. The council’s housing and small business expertise lines up with the bank’s push into higher touch commercial and small business relationships in the Gulf South, where new bankers and the One Florida Bank deal are already increasing exposure.
For you as a shareholder, the practical question is whether this council helps sharpen where capital and lending capacity are directed, so that loan growth from Texas, Florida and community development efforts is both sustainable and within the bank’s existing risk appetite. Execution on that front matters because loan quality, operating efficiency, and balance sheet repricing remain the key catalysts investors are watching.
Hancock Whitney's consensus outlook ties together revenue and profit in a single line of sight. Analysts see revenues at about $2.0b and earnings of $659.6m by 2029, which implies 12.6% yearly revenue growth and an earnings increase of roughly $233.7m from $425.9m today.
Uncover why Hancock Whitney's fair value indicates a 16% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
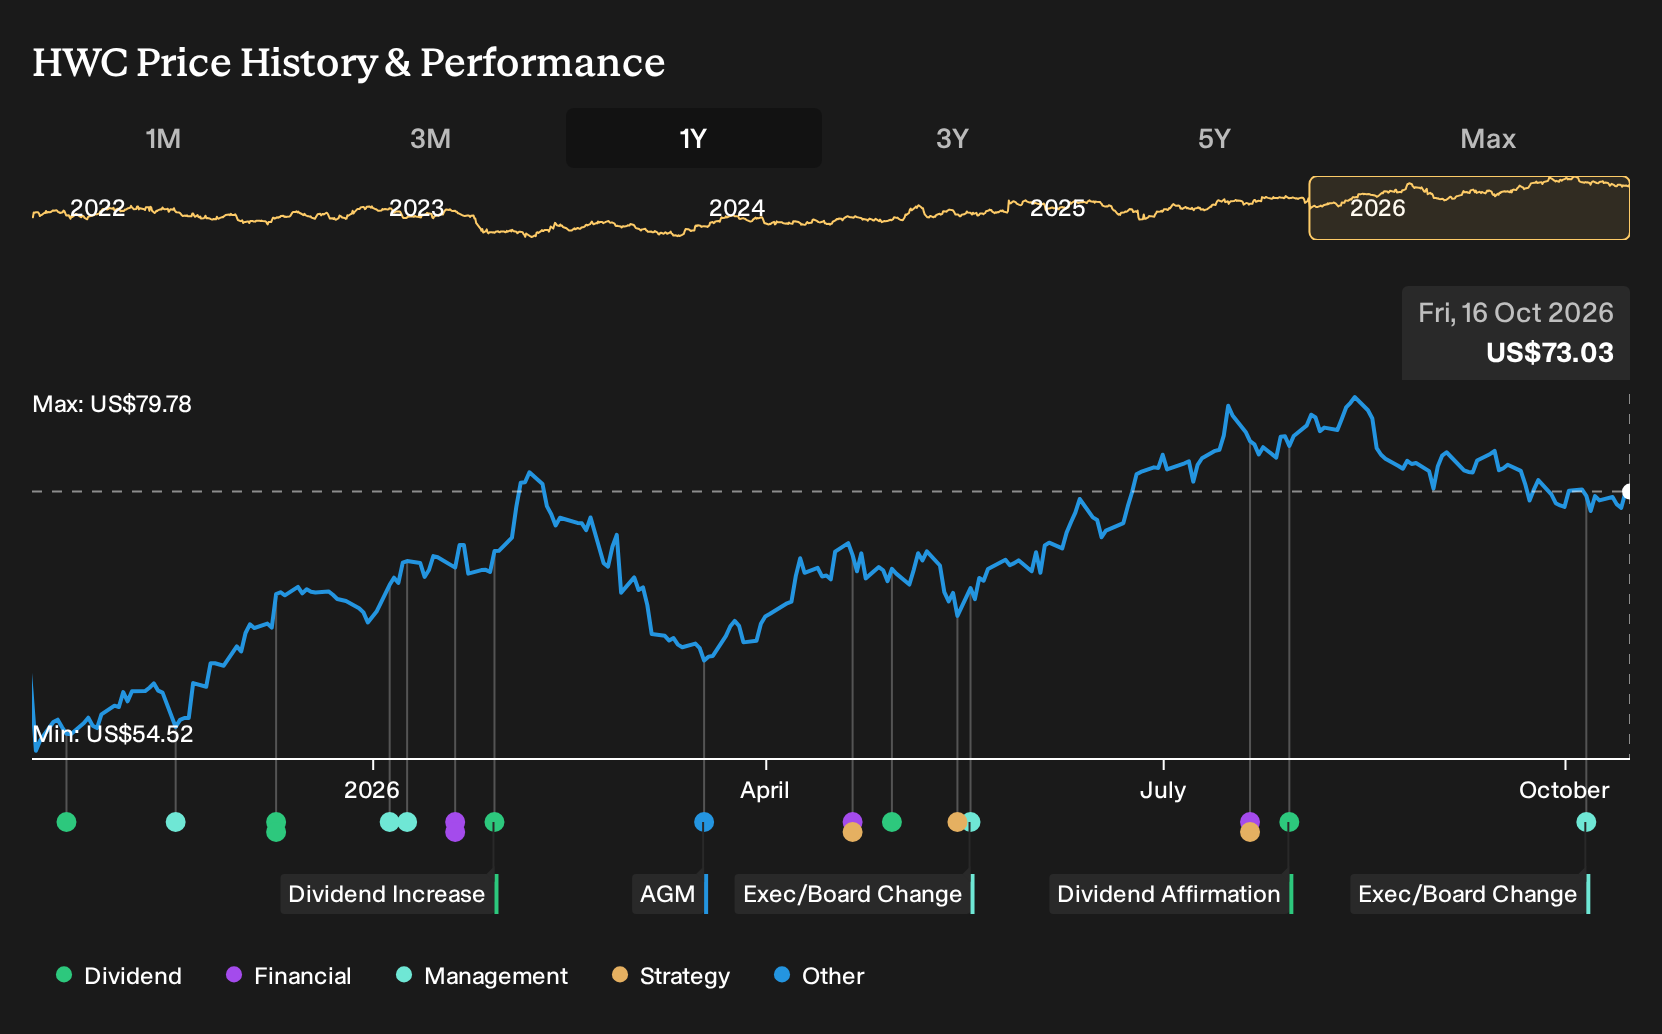
Two fair value estimates from the Simply Wall St Community span roughly US$84.53 to US$139.08 per share, which is a wide band for Hancock Whitney. That spread sits against pressure from the June 2026 revenue and profit declines, but also against catalysts like balance sheet repricing and the One Florida Bank integration. You can use that contrast as a prompt to compare several alternative viewpoints before deciding how Hancock Whitney fits into your own thesis.
Explore another Hancock Whitney fair value estimate, including one that suggests it could be worth just $84.52.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis carefully.
- A great starting point for your Hancock Whitney research is our analysis highlighting 3 key rewards and 1 important warning sign that could inform your investment decision.
- See our latest analysis for Hancock Whitney. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to review Hancock Whitney's overall financial health at a glance.
Looking for more Hancock Whitney investment ideas?
If the Hancock Whitney story has you thinking about portfolio balance, it can help to compare it with other opportunities with different risk, income, and quality profiles using the Simply Wall St Screener.
- For investors who want staying power and lower volatility, review a 32 resilient stocks with low risk scores that may fit a more defensive allocation.
- If value is your focus, compare Hancock Whitney against a 33 high quality undervalued stocks that combine solid fundamentals with more attractive pricing.
- For those building an income oriented portfolio, scan a 8 dividend fortresses that might complement or contrast with Hancock Whitney's role in your holdings.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com