


TX Group (SWX:TXGN) Could Be 58% Undervalued On Cash Flow Debate
Fresh discussion around TX Group (SWX:TXGN) focuses on whether recent share gains align with its cash generation, as DCF work, cost cuts, and solid net liquidity put the current valuation under the spotlight.
Recent momentum in TX Group’s share price has been strong, with a 36.23% 90-day share price return and a 13.22% 30-day move, even though the 1-year total shareholder return is down 4.35%. The 3-year total shareholder return of 141.06% points to a much stronger longer-run journey.
Scan beyond TX Group and review a curated group of cash-generative value ideas with resilient fundamentals in our 189 high quality undervalued stocks.
TX Group has already delivered a powerful rebound, yet the recent 90 day surge and modest discount to analyst targets suggest investors still debate the real upside. How much of the value story is already in the price?
Preferred Price-to-Sales of 2.2x: Is it justified?
On current numbers, TX Group is priced on a P/S of 2.2x, which lines up with a share price of CHF185 that screens as expensive against the wider European media pack but cheaper than its closer peer group.
The P/S ratio compares the company’s market value with its revenue and helps you see how much investors are paying for each franc of sales. For a diversified media and platforms group like TX Group, where earnings are currently in the red and revenue is forecast to decline by 4.7% per year over the next 3 years, this type of sales-based gauge often becomes a primary reference point.
Relative to the European Media sector average of 0.6x, the current 2.2x multiple looks heavy and signals that the market is attaching a richer tag to TX Group’s revenue than to the typical peer. Yet when set against the peer subset on 3x, the same 2.2x starts to look more measured. It also sits slightly above an estimated fair P/S of 2x that our work suggests the price could eventually gravitate towards if expectations reset.
Explore the SWS fair ratio for TX Group.
Result: Price-to-Sales of 2.2x (OVERVALUED).
Still, TX Group’s loss of CHF8.5m and revenue decline of 4.7% a year raise questions about whether the recent share price surge can hold.
Find out about the key risks to this TX Group narrative.
Another view on TX Group’s value
A different lens gives a very different message. Our DCF model values TX Group at CHF291.52 a share, which is well above the current CHF185 price and points to a stock that screens as undervalued on this cash flow view.
That kind of gap can indicate a potential difference between our assumptions and those reflected in the market. It leaves a practical question for you as an investor. Which perspective do you rely on more: the sales multiple or the cash flow model?
Look into how the SWS DCF model arrives at its fair value.
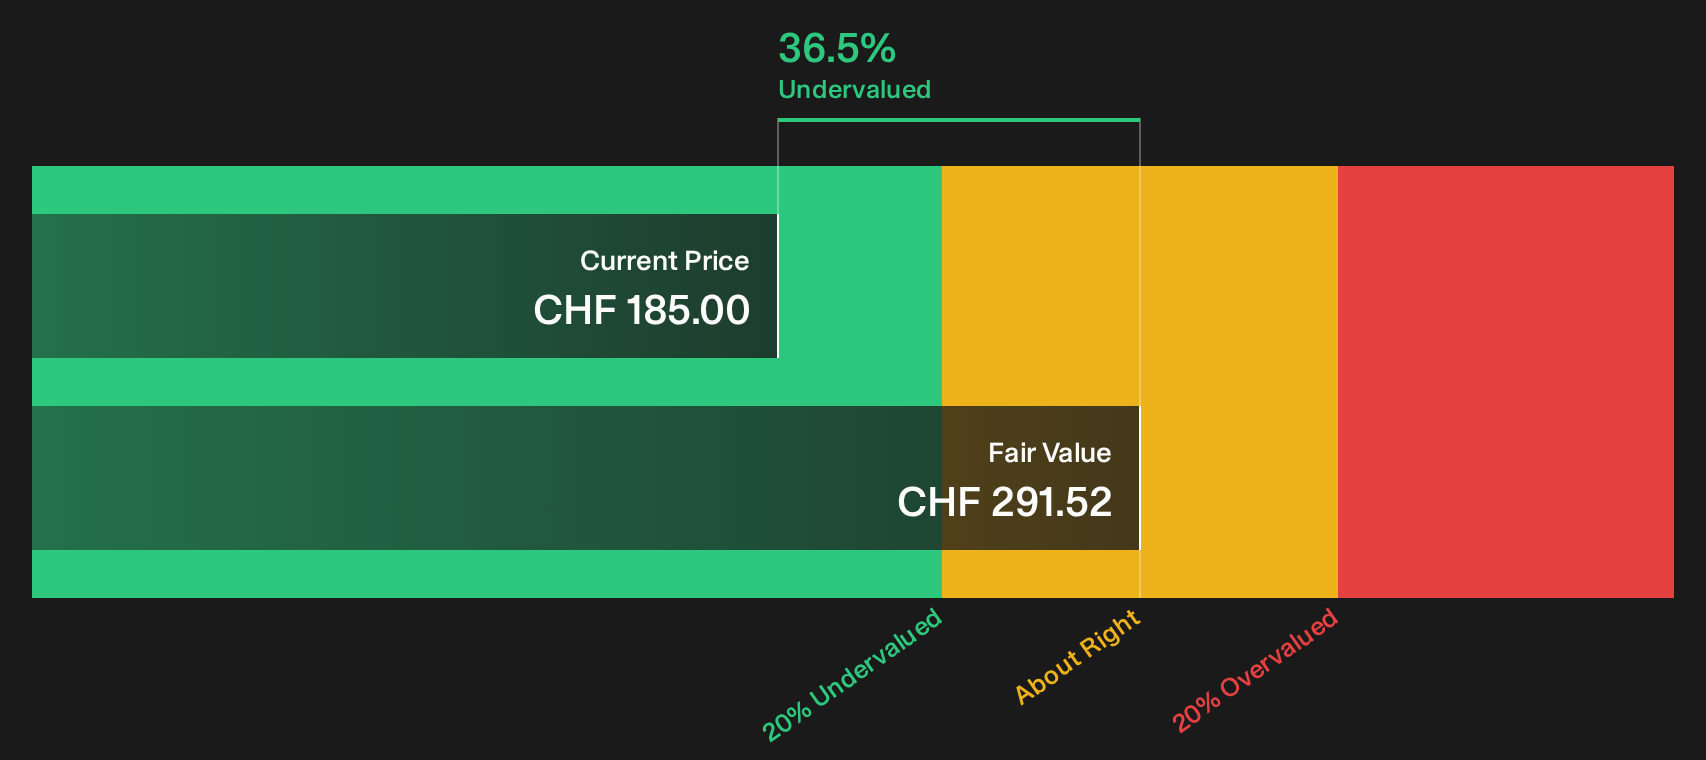
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out TX Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 189 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on TX Group’s value story can be confusing, so move quickly, verify the numbers yourself, and weigh both sides of the argument with the 2 key rewards and 1 important warning sign
Looking for more investment ideas beyond TX Group?
If TX Group has sharpened your focus on value and risk, do not stop here. Broader opportunity often sits in overlooked corners of the market.
- Hunt for mispriced quality by scanning a curated pool of resilient value opportunities through the 189 high quality undervalued stocks.
- Strengthen your portfolio backbone by filtering for companies with sturdy finances and reliable fundamentals using the list of solid balance sheet and fundamentals (204 results).
- Get ahead of the crowd by spotting under-followed potential with the 614 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com