


Tosei (TSE:8923) Just Put Itself Back On Investors’ Radar
Tosei (TSE:8923) just lifted its earnings and dividend forecasts after reporting nine month results, tying the outlook upgrade to steady Japanese real estate demand and stronger contributions from its Revitalization, Rental, and Fund and Consulting operations.
The guidance and dividend upgrade on 5 October landed after a softer patch, with the 90 day share price return declining 3.37%. However, the 7 day share price return of 4.11% and a 1 year total shareholder return of 10.35% suggest momentum is rebuilding off a longer track record of strong compounding over three and five years.
Position Tosei in context and scan a curated 13 high quality undervalued stocks that share a mix of real estate exposure, earnings support and balance sheet strength.Tosei’s share price has started to recover just as earnings guidance and dividends move higher. Is this bounce mostly sentiment, or a reset toward what the current fundamentals already suggest on valuation?
Price-to-Earnings of 10.8x: Is it justified?
Tosei is trading on a P/E of 10.8x, which sits below the broader JP market but above the average for local real estate peers, so the share price reflects a mixed message on valuation.
The P/E ratio compares what investors are paying today for each unit of current earnings. For a diversified property group with Revitalization, Development, Rental, and fee-based Fund and Consulting segments, this measure focuses attention squarely on profit generation rather than asset values alone.
Tosei’s earnings have grown 17.8% per year over the past 5 years, and forecasts point to ongoing profit growth of 9.2% per year and revenue growth of 11.1% per year. Against that backdrop, a P/E of 10.8x sits below the estimated fair P/E of 12.7x. This suggests the multiple could move closer to that fair level if the earnings outlook and balance sheet risks stay broadly in line with current expectations.
Compared with the JP Real Estate industry average P/E of 10.1x, Tosei trades on a slightly higher multiple. This signals the market is already ascribing some premium to its earnings quality and track record, even though that premium is smaller than the gap to the JP market multiple of 14x and the estimated fair P/E of 12.7x.
Explore the SWS fair ratio for Tosei.
Result: Price-to-Earnings of 10.8x (UNDERVALUED)
Still, any stumble in Japanese real estate demand, or a setback in Tosei’s Revitalization pipeline, could quickly challenge the current P/E story.
Find out about the key risks to this Tosei narrative.
Another View: Tosei Through A Cash Flow Lens
Tosei looks inexpensive on a 10.8x P/E, yet the SWS DCF model paints a tougher picture. On that cash flow view, the current share price of ¥1,723 sits above an estimated fair value of ¥1,172.46, which points to the stock as overvalued on this method.
This gap between an apparently cheap earnings multiple and a richer DCF outcome raises a practical question for investors. Which signal should carry more weight: the current profit stream, or the longer term cash flow profile that the model is capturing?
Look into how the SWS DCF model arrives at its fair value.
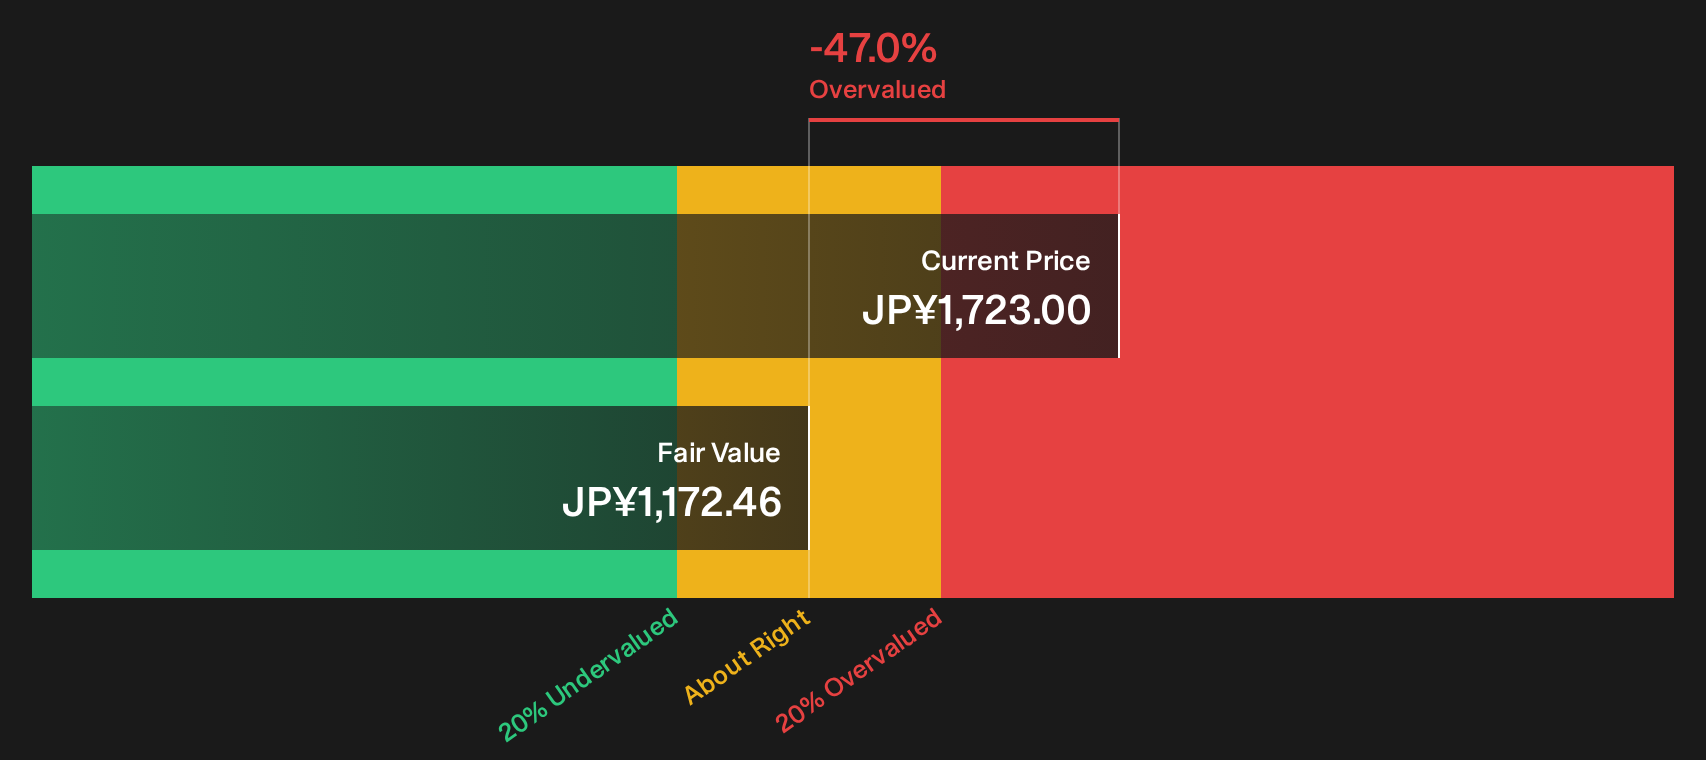
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Tosei for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 13 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the mixed signals around Tosei leave you on the fence, move quickly from headline takeaways to your own scoreboard of risks and upside. Ground that view in the full picture by weighing its 3 key rewards and 2 important warning signs
Looking for more Tosei-sized investment ideas?
If Tosei has you rethinking where value and resilience meet, do not stop at a single ticker. Cast the net wider and give your portfolio more options.
- Target potential mispricing by scanning a focused 13 high quality undervalued stocks that share strong fundamentals and may be trading below what their financials suggest.
- Strengthen capital protection by reviewing a curated 23 resilient stocks with low risk scores that show more resilient risk profiles than the broader market.
- Spot potential early-stage opportunities by checking a handpicked 73 high quality undiscovered gems that combine quality metrics with relatively low investor attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com