


Lovisa Holdings (ASX:LOV) Could Be 10% Below Fair Value After Leadership Changes
Leadership changes put Lovisa Holdings under the microscope
Lovisa Holdings (ASX:LOV) is back in focus after two leadership shifts, with Group CFO Chris Lauder resigning and Deputy Chairman Mark McInnes moving to a non-executive role later this month.
Recent trading has been choppy for Lovisa Holdings, with the share price up 4.47% on the day and an 8.65% 1 month share price return. However, the year to date share price return is down 13.83% and the 1 year total shareholder return has fallen 30.33%. This contrasts with the 3 year total shareholder return of 54.83% and the 5 year total shareholder return of 41.61%, which points to longer term gains but fading momentum into this leadership reshuffle.
Compare how Lovisa Holdings stacks up against other retailers facing leadership shifts and global rollouts by scanning our curated list of list of solid balance sheet and fundamentals (12 results).
Bulls see Lovisa Holdings as a global roll out story with solid recent revenue and profit growth, while bears focus on leadership churn and a falling 1 year return. Which side fits the valuation math that follows?
Most Popular Narrative: 9% Undervalued
Lovisa Holdings closed at A$25.24, while the most followed narrative pegs fair value at A$27.70 using an 8.2% discount rate. That gap leans modestly in favor of the valuation story that underpins the current global rollout.
The market may be embedding overly optimistic assumptions that Lovisa's global store rollout can continue at the current rapid annualized pace (160+ stores per year), despite evidence that such expansion requires ever larger capital investment and rising fixed costs, which are likely to result in diminishing operating leverage and downward pressure on net margins and earnings as the rollout base expands.
See why 33 investors see Lovisa Holdings as 9% undervalued.
Result: Fair Value of A$27.70 (UNDERVALUED)
Still, that story can unravel if Lovisa Holdings struggles to sustain its 82% gross margin, or if heavy global store expansion drags on profitability.
Find out about the key risks to this Lovisa Holdings narrative.
Another View: What Lovisa Holdings’ P/E Is Telling You
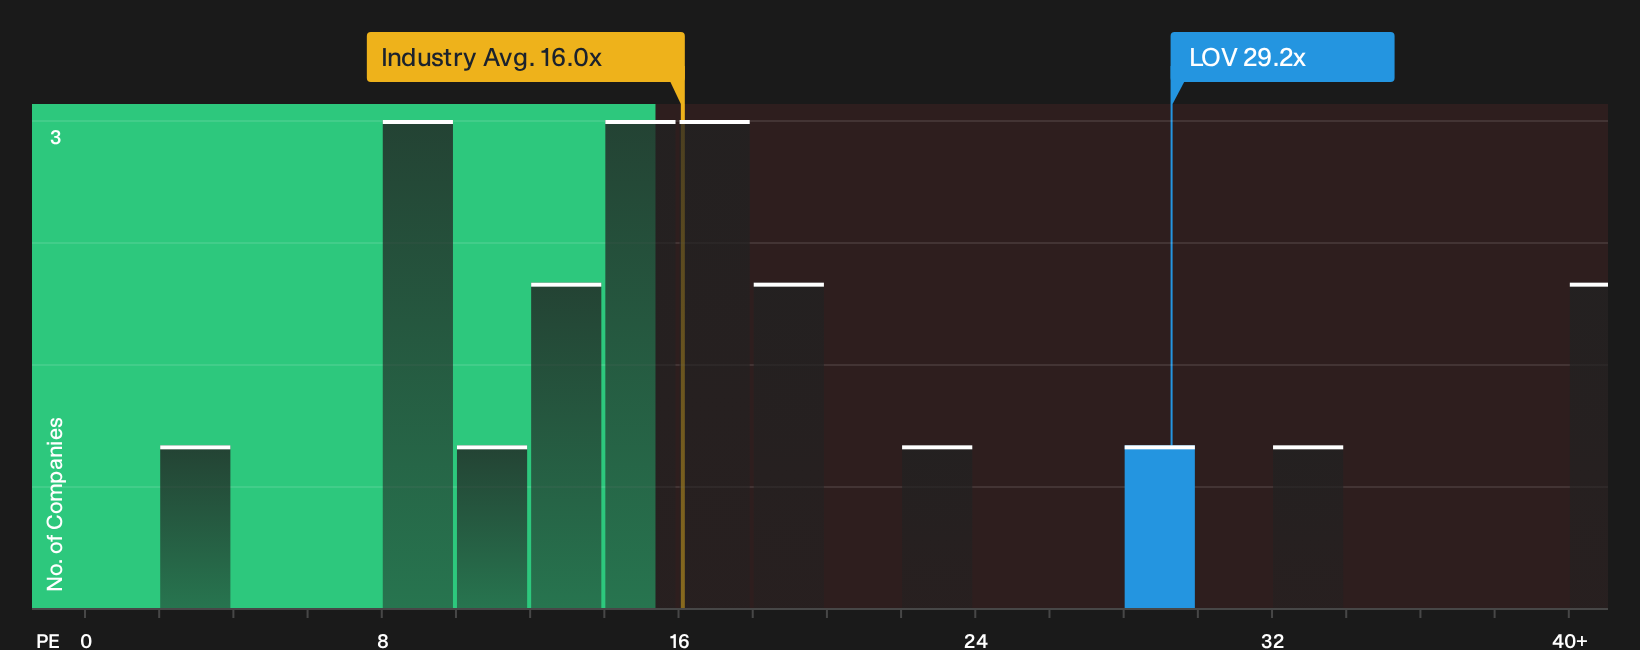
The story looks very different when you swap the narrative fair value for plain P/E math. Lovisa Holdings trades on 29.2x earnings, while peers sit near 13x and the fair ratio is 20.4x. That gap points to a rich valuation and less room for error if growth stumbles.
For a closer look at what this price is baking in, get into the detailed valuation breakdown with See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
If the mixed signals on Lovisa Holdings leave you torn, treat that tension as a cue to inspect the numbers yourself. Move quickly to form an independent view using 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Lovisa Holdings?
If Lovisa Holdings has you thinking harder about price, quality and risk, do not stop here. Broader opportunity often sits just outside your current watchlist.
Use the Simply Wall St Screener to quickly compare potential opportunities and pressure test your thinking before committing any fresh capital.
- Target potential mispricing by scanning companies that combine strong fundamentals with attractive valuations through the 15 high quality undiscovered gems.
- Lock in potential income ideas by reviewing rock-solid payers with resilient balance sheets using the 4 dividend fortresses.
- Dial down risk in your portfolio by focusing on businesses that score well on stability and strength through the 6 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com